₹5000 SIP से ₹10 लाख तक कैसे पहुंचेगा? पूरा Calculation
₹5000 की monthly SIP से ₹10 लाख का corpus बनाया जा सकता है, लेकिन कितने समय में बनेगा यह assumed return पर depend करता है। 6%, 8%, 10%, 12% या 15% annualized return मानने पर ₹10 लाख तक पहुँचने का समय अलग होगा। इस article में इसी target का step-by-step calculation दिया गया है, ताकि आप अपनी SIP planning को आसानी से समझ सकें।
ध्यान रखें कि mutual fund returns fixed नहीं होते। नीचे के numbers illustrative calculations हैं, guaranteed returns नहीं। Actual corpus market performance, fund selection, investment dates और expenses के कारण अलग हो सकता है। AMFI के अनुसार SIP fixed amount को नियमित interval पर invest करने की methodology है और rupee cost averaging profit की guarantee नहीं देता।
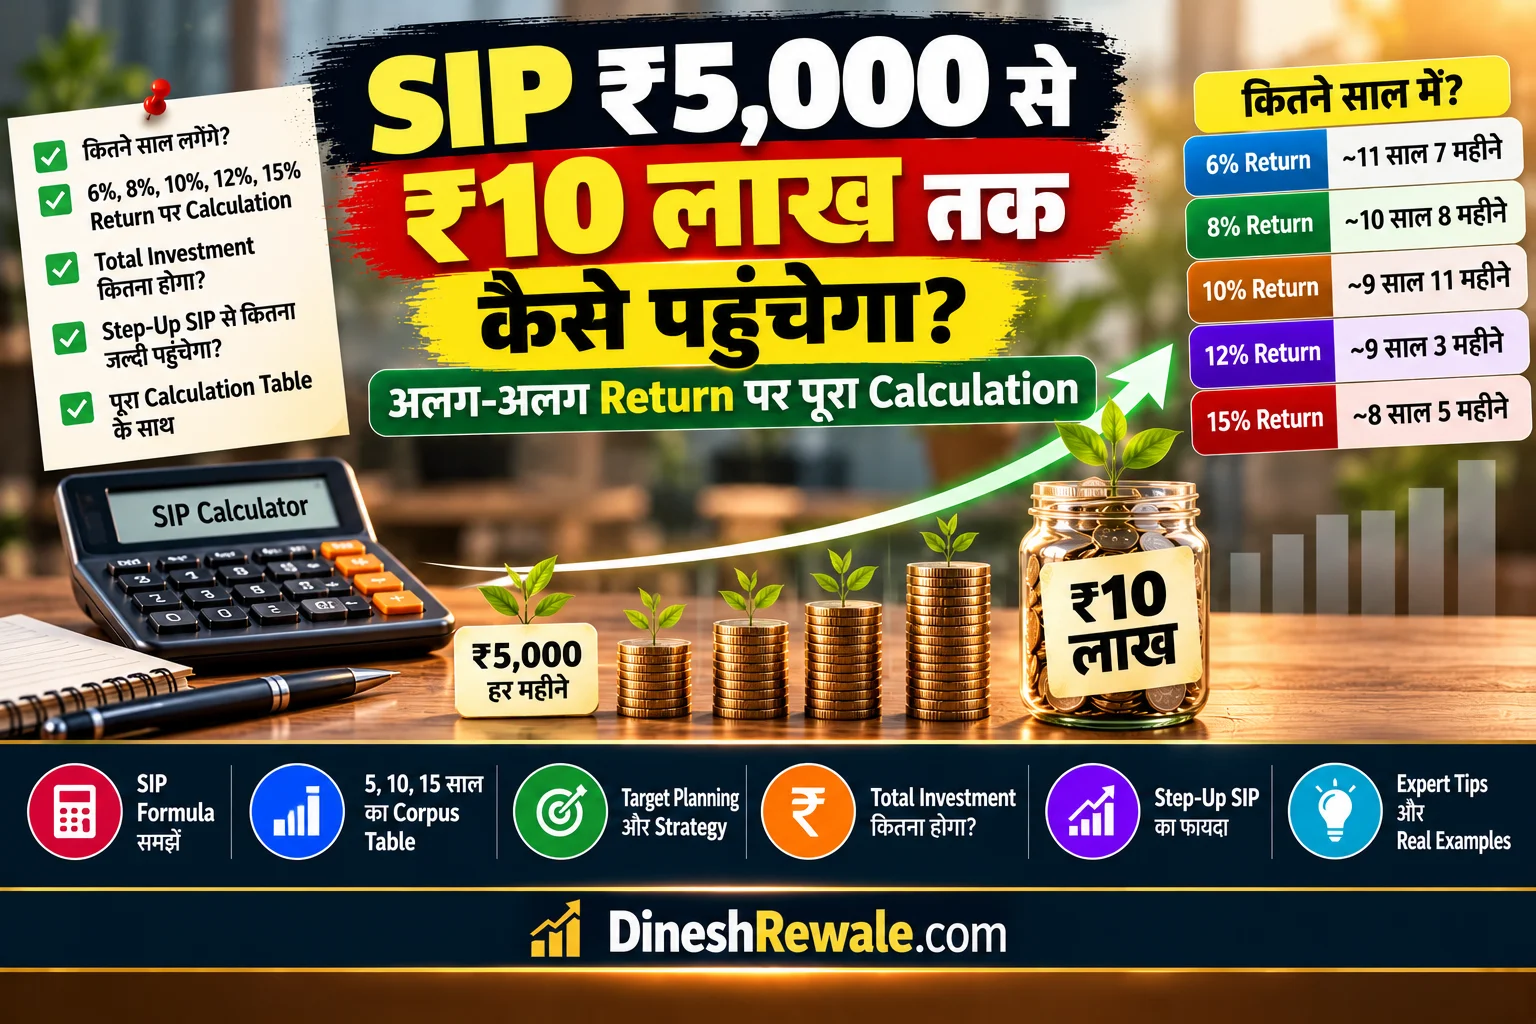
Quick Answer: ₹5,000 monthly SIP को monthly compounding assumption के साथ देखें तो लगभग 10% annual return पर ₹10 लाख तक पहुँचने में करीब 9 साल 11 महीने लग सकते हैं। 8% पर करीब 10 साल 8 महीने और 12% पर करीब 9 साल 3 महीने लग सकते हैं। ये सिर्फ illustrations हैं।
₹5,000 SIP से ₹10 लाख: सबसे पहले basic calculation
हर महीने ₹5,000 invest करने पर एक साल में आपका total contribution ₹60,000 होगा। लेकिन ₹10 लाख तक पहुँचने के लिए सिर्फ contribution जोड़ना काफी नहीं है। Compounding के कारण investment पर समय के साथ return भी जुड़ता है और वही target तक पहुँचने की journey को छोटा कर सकता है।
| Monthly SIP | Yearly Investment | Target Corpus | Main Variable |
|---|---|---|---|
| ₹5,000 | ₹60,000 | ₹10,00,000 | Return + Time |
इसलिए “₹5,000 SIP से ₹10 लाख कब बनेंगे?” का एक ही fixed answer नहीं है। Return assumption बदलते ही target date भी बदल जाती है।
अलग-अलग Return पर ₹10 लाख तक पहुँचने में कितना समय?
नीचे calculation में ₹5,000 monthly SIP और monthly compounding assumption लिया गया है। Target को cross करने वाला पहला पूरा month दिखाया गया है।
| Assumed Annual Return | Approx. Time | Full Months | Total Contribution* |
|---|---|---|---|
| 6% | लगभग 11 साल 7 महीने | 139 | ₹6.95 लाख |
| 8% | लगभग 10 साल 8 महीने | 128 | ₹6.40 लाख |
| 10% | लगभग 9 साल 11 महीने | 119 | ₹5.95 लाख |
| 12% | लगभग 9 साल 3 महीने | 111 | ₹5.55 लाख |
| 15% | लगभग 8 साल 5 महीने | 101 | ₹5.05 लाख |
*Contribution सिर्फ monthly SIP × number of completed months है। Actual market returns अलग होने के कारण real-world result इससे अलग हो सकता है.
10% Return मानें तो ₹5,000 SIP से ₹10 लाख कब?
10% annualized return का illustration लें तो monthly SIP ₹5,000 के साथ लगभग 119 months, यानी करीब 9 साल 11 महीने में corpus ₹10 लाख के आसपास पहुँचता है। 119 महीनों में आपका total contribution ₹5.95 लाख होगा। बाकी हिस्सा investment growth से आता है।
यह example compounding की power समझने के लिए useful है। लेकिन 10% को future return की guarantee मानना गलत होगा। AMFI के investor resources के अनुसार mutual fund returns assured नहीं होते और past performance future performance की guarantee नहीं देती।
5, 10 और 15 साल में ₹5,000 SIP का corpus कितना हो सकता है?
अब target को उल्टा देखें। अगर आप ₹5,000 SIP को fixed रखते हैं, तो अलग-अलग return assumptions पर 5, 10 और 15 साल के illustrative corpus नीचे हैं।
| Return Assumption | 5 Years | 10 Years | 15 Years |
|---|---|---|---|
| 6% | ₹3.49 लाख | ₹8.19 लाख | ₹14.54 लाख |
| 8% | ₹3.67 लाख | ₹9.15 लाख | ₹17.30 लाख |
| 10% | ₹3.87 लाख | ₹10.24 लाख | ₹20.72 लाख |
| 12% | ₹4.08 लाख | ₹11.50 लाख | ₹24.98 लाख |
| 15% | ₹4.43 लाख | ₹13.76 लाख | ₹33.43 लाख |
इस table से एक important point साफ है: time और compounding return दोनों महत्वपूर्ण हैं। लेकिन return assumption को aggressive बनाकर target period छोटा दिखाना planning की safe strategy नहीं है। Real-world planning में conservative assumption के साथ buffer रखना बेहतर है।
₹10 लाख Target के लिए formula क्या है?
Monthly SIP के future value की सामान्य formula है:
FV = P × [((1 + r)n − 1) / r]
जहाँ:
- FV = future value या target corpus
- P = monthly SIP
- r = monthly assumed return
- n = total number of monthly investments
इस article में target ₹10,00,000 और monthly SIP ₹5,000 रखी गई है। Return assumption बदलकर आप approximate target time निकाल सकते हैं। यही logic SIP calculators में भी इस्तेमाल होता है, हालांकि different calculators contribution timing और compounding convention में छोटे differences use कर सकते हैं।
अगर ₹5,000 SIP से जल्दी ₹10 लाख चाहिए तो क्या करें?
Target period कम करने का सबसे practical तरीका सिर्फ higher return assume करना नहीं है। SIP amount बढ़ाना भी powerful lever है। Return predict करने के बजाय contribution increase पर control ज्यादा होता है।
| Approach | फायदा | ध्यान रखने वाली बात |
|---|---|---|
| SIP ₹5,000 पर रखें | Budget आसान | Target में ज्यादा समय लग सकता है |
| Annual step-up करें | Income बढ़ने के साथ investment बढ़ता है | Cash flow का ध्यान रखें |
| Bonus से extra investment | Goal को accelerate कर सकता है | Emergency reserve खाली न करें |
आप ₹10,000 SIP से 15 साल में कितना Corpus बनेगा? वाली calculation guide में SIP amount बढ़ने का long-term impact भी देख सकते हैं।
₹5,000 SIP को Step-Up करने से क्या फर्क पड़ सकता है?
मान लीजिए आपकी current SIP ₹5,000 है और income हर साल बढ़ती है। ऐसे में fixed SIP के बजाय annual step-up strategy अपनाने से contribution धीरे-धीरे बढ़ाया जा सकता है। इससे target corpus तक पहुँचने की speed improve हो सकती है।
लेकिन step-up को blindly high percentage पर set करना जरूरी नहीं। बेहतर है कि salary increment, expenses, emergency fund और existing goals के साथ contribution review करें।
SIP शुरू करने का basic process समझने के लिए SIP कैसे शुरू करें? Beginners के लिए 7 Steps भी पढ़ें।
₹10 लाख Target बनाते समय कौन-सी Return Assumption लें?
यही जगह है जहाँ कई SIP calculations misleading हो सकती हैं। 12% या 15% return देखकर target जल्दी पूरा होता हुआ दिख सकता है, लेकिन actual market return हर साल एक जैसा नहीं रहता। कभी positive return, कभी correction और कभी flat period आ सकता है।
इसलिए planning में एक single optimistic return के बजाय multiple scenarios देखना ज्यादा useful है। उदाहरण के लिए 8%, 10% और 12% के three scenarios से आपको target timeline की range समझ आती है।
AMFI बताता है कि mutual fund schemes guaranteed या assured-return products नहीं हैं और past performance future performance की guarantee नहीं देती।
क्या ₹5,000 SIP से ₹10 लाख Guaranteed बनेंगे?
नहीं। ₹10 लाख एक target है, guaranteed outcome नहीं। Calculation में assumed return डालने पर एक estimated future value या target period मिलता है। Actual market return कम हुआ तो target देर से पूरा हो सकता है। Higher return हुआ तो पहले भी हो सकता है।
SIP market volatility और investment discipline handle करने का एक तरीका हो सकता है, लेकिन यह loss-proof strategy नहीं है। AMFI के अनुसार rupee cost averaging profit assure नहीं करता और declining markets में investment losses से protect नहीं करता।
किसके लिए ₹5,000 से ₹10 लाख का Target Useful है?
| Investor Type | यह calculation क्यों useful है? |
|---|---|
| Beginner | Small monthly amount से target planning समझने के लिए |
| Young investor | Long time horizon और compounding को समझने के लिए |
| Goal-based investor | Target corpus से reverse planning करने के लिए |
| Working professional | Step-up SIP का decision लेने के लिए |
₹10 लाख Target के लिए SIP Plan कैसे बनाएं?
- Target तय करें: आपका target ₹10 लाख है या inflation-adjusted future amount?
- Time horizon तय करें: 5, 10 या 15 साल में target चाहिए?
- Multiple return scenarios देखें: सिर्फ एक optimistic number पर depend न करें।
- Monthly SIP calculate करें: Target और time के हिसाब से contribution तय करें।
- Step-up consider करें: income बढ़ने पर SIP भी बढ़ सकती है।
- Emergency fund अलग रखें: goal investment के लिए emergency cash sacrifice न करें।
- Periodic review करें: goal, risk और fund suitability बदलने पर strategy review करें।
Goal-based investing पर Financial Goals कैसे Set करें? और asset allocation पर Asset Allocation by Age & Salary भी useful references हैं।
₹10 लाख आज और ₹10 लाख भविष्य में एक जैसे नहीं
Inflation को ignore करके target बनाना एक common mistake है। अगर आपकी जरूरत कई साल बाद है, तो आज का ₹10 लाख future में उसी purchasing power का नहीं हो सकता। इसलिए long-term goals के लिए केवल nominal corpus target देखने के बजाय inflation-adjusted target पर भी विचार करें।
उदाहरण के तौर पर, अगर कोई goal 10-15 साल दूर है, तो आज का ₹10 लाख target future need को पूरी तरह represent नहीं कर सकता। Practical planning में इस factor को शामिल करना जरूरी है।
₹5,000 SIP में सबसे बड़ी गलती क्या हो सकती है?
सिर्फ calculator के return number पर भरोसा करना। अगर कोई calculation 15% return मानकर target को जल्दी दिखाती है, तो इसका अर्थ यह नहीं कि वही outcome निश्चित रूप से मिलेगा। Goal planning में contribution discipline, time horizon, asset allocation और realistic assumptions ज्यादा important हैं।
दूसरी बड़ी गलती है market गिरते ही SIP बंद करना। SIP का framework regular investing पर आधारित है, लेकिन fund की suitability और आपकी financial situation में बदलाव होने पर review जरूर होना चाहिए।
₹5,000 SIP से ₹10 लाख: Final Takeaway
₹5,000 monthly SIP से ₹10 लाख तक पहुँचने में लगभग 8.4 साल से 11.6 साल के बीच का समय लग सकता है, अगर 15% से 6% annual return के अलग-अलग illustrative assumptions लिए जाएँ। 10% assumption पर लगभग 9 साल 11 महीने का estimate आता है।
लेकिन इस calculation का सबसे important lesson “कौन-सा return मिलेगा?” नहीं, बल्कि “मैं कितने समय तक disciplined रह सकता हूँ और जरूरत पड़ने पर SIP कितना बढ़ा सकता हूँ?” है। Longer time horizon और higher contribution target achievement पर meaningful difference ला सकते हैं।
FAQs
क्या ₹5,000 SIP से ₹10 लाख 10 साल में बन सकते हैं?
हाँ, कुछ return assumptions पर ₹10 लाख 10 साल के आसपास cross हो सकते हैं। उदाहरण के लिए 10% annualized return assumption पर 10 साल की illustration लगभग ₹10.24 लाख देती है। Actual outcome market performance पर depend करेगा।
₹5,000 SIP से ₹10 लाख बनने में कितने साल लगेंगे?
Assumed return के आधार पर समय बदलता है। इस calculation में 6% पर करीब 11 साल 7 महीने और 15% पर करीब 8 साल 5 महीने का estimate आता है।
क्या 12% return मानना सही है?
12% को calculation scenario के रूप में use किया जा सकता है, लेकिन इसे guaranteed future return नहीं मानना चाहिए। Different scenarios देखना ज्यादा practical है।
क्या SIP की रकम हर साल बढ़ानी चाहिए?
जरूरी नहीं, लेकिन income बढ़ने पर step-up SIP long-term target को accelerate कर सकती है। Amount आपकी affordability और अन्य financial goals के अनुसार तय होनी चाहिए।
क्या ₹10 लाख target के लिए Equity Mutual Fund ही लेना जरूरी है?
नहीं। Product selection goal horizon, risk capacity, asset allocation और financial situation पर depend करता है। Equity mutual funds market-linked होते हैं और higher volatility हो सकती है।
क्या SIP calculator का result exact होता है?
नहीं। Calculator assumed return और contribution timing के आधार पर estimate देता है। Actual market returns अलग होने के कारण final corpus अलग हो सकता है।
Useful Official Resources
और पढ़ें: ₹5,000 SIP से 10 साल में कितना पैसा बनेगा? | SIP में कितने साल तक Invest करना चाहिए? | 2026 में Best SIP चुनने के 7 Rules | SIP कैसे शुरू करें? | ₹10 लाख कहाँ Invest करें? | Financial Goals कैसे Set करें?
Author: Dinesh Rewale
Dinesh Rewale personal finance, investing, business और practical money topics पर reader-focused content लिखते हैं। उनका उद्देश्य complex financial topics को simple और actionable language में समझाना है।
Facebook: Dinesh Rewale
Disclaimer: यह article केवल educational और informational purpose के लिए है। यह personalized investment, tax या financial advice नहीं है। Mutual fund investments market risks के अधीन होते हैं और returns की कोई guarantee नहीं होती। यहाँ दिए गए SIP calculations illustrative हैं और assumed return, contribution timing तथा compounding method पर आधारित हैं। वास्तविक returns अलग हो सकते हैं। किसी भी investment decision से पहले scheme documents, Riskometer, applicable costs और अपनी financial situation को ध्यान में रखें। जरूरत होने पर SEBI-registered investment adviser से personalized सलाह लें।