₹10 लाख कहाँ Invest करें? 5 Practical Options
अगर आपके पास ₹10 लाख की lump-sum रकम है, तो सबसे बड़ा सवाल सिर्फ यह नहीं है कि पैसा कहाँ लगाया जाए। असली सवाल है कि इस रकम को आपके goal, time horizon, risk tolerance और liquidity needs के हिसाब से कैसे बाँटा जाए। पूरी रकम एक ही जगह लगाने से portfolio किसी एक तरह के risk के प्रति ज्यादा exposed हो सकता है.
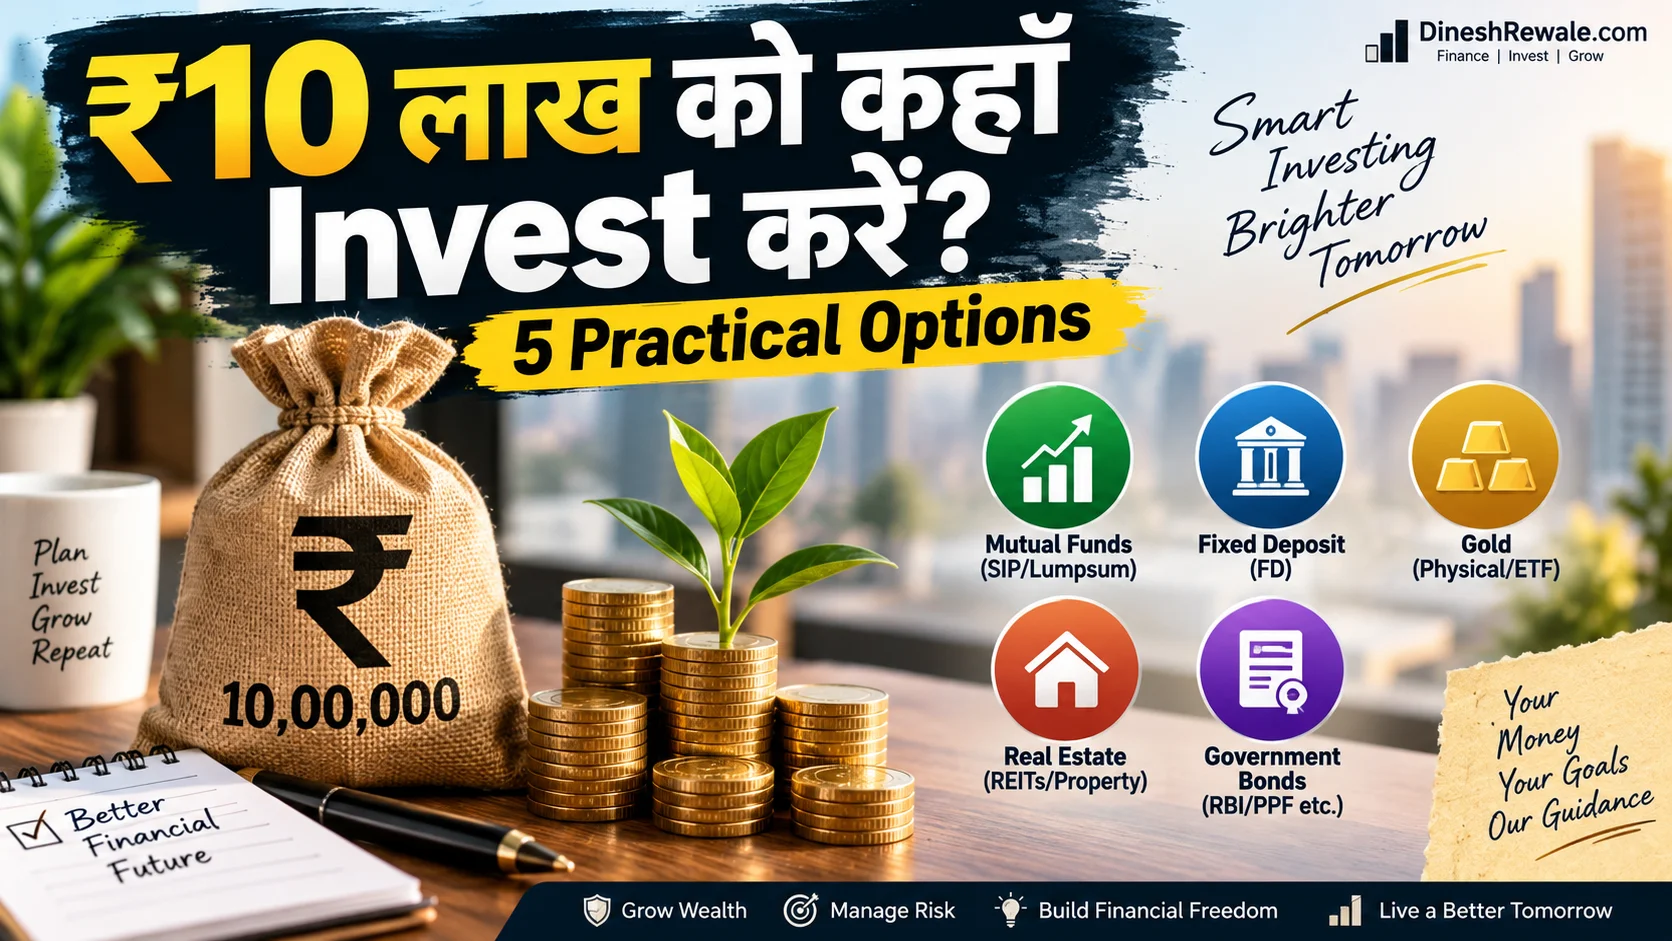
इस guide में हम ₹10 लाख निवेश के 5 practical options समझेंगे: Fixed Deposit, Debt Mutual Funds, Nifty 50 जैसे broad-market Index Funds, Gold ETF और REITs. साथ में एक illustrative allocation भी देखेंगे, ताकि आपको अंदाजा हो सके कि lump-sum को asset classes में कैसे spread किया जा सकता है.
ध्यान दें: नीचे दिए गए returns के examples guaranteed returns नहीं हैं. Actual return market conditions, interest rates, fund performance, charges और taxes के कारण अलग हो सकता है.
₹10 लाख Invest करने से पहले 4 बातें तय करें
निवेश का सही तरीका रकम से कम और आपकी स्थिति से ज्यादा जुड़ा होता है. ₹10 लाख किसी व्यक्ति के लिए retirement corpus का हिस्सा हो सकता है, तो किसी दूसरे के लिए घर की down payment या business capital.
- Goal: पैसा किस काम के लिए है?
- Time Horizon: 1-3 साल, 3-7 साल या 7+ साल?
- Risk: क्या temporary market fall में आप investment hold कर सकते हैं?
- Liquidity: क्या यह पैसा emergency में तुरंत चाहिए हो सकता है?
SEBI की investor education guidance भी निवेश को risk tolerance और investment horizon के साथ match करने और अलग asset classes में diversification पर जोर देती है. SEBI Investor: How to Manage Investment Risks
1. Fixed Deposit (FD): Capital Stability के लिए
अगर आपके ₹10 लाख का कुछ हिस्सा आपको relatively predictable interest और capital stability के लिए चाहिए, तो Bank FD एक practical option हो सकता है.
FD का सबसे बड़ा फायदा simplicity है. आपको पहले से tenure और interest rate पता होता है और maturity तक hold करने पर return market volatility से directly प्रभावित नहीं होता.
₹10 लाख FD में लगाने से क्या समझें?
मान लीजिए किसी bank FD पर illustrative annual interest 7% है और पूरा ₹10 लाख एक साल के लिए लगाया गया. Simple illustration में interest करीब ₹70,000 होगा, हालांकि actual interest calculation, payout mode, compounding, TDS और tax treatment bank और आपकी स्थिति पर निर्भर करेगा.
महत्वपूर्ण: FD interest taxable हो सकता है. इसलिए केवल headline interest rate देखकर comparison न करें, बल्कि post-tax return देखें.
Deposit insurance की बात करें तो DICGC के अनुसार eligible deposits पर principal और interest मिलाकर प्रति depositor, प्रति insured bank अधिकतम ₹5 लाख तक insurance cover है. अलग-अलग branches के deposits को उसी bank के लिए aggregate किया जाता है. DICGC Deposit Insurance FAQs
इसलिए बहुत बड़ी रकम को एक ही bank में रखने से पहले bank-wise deposit exposure को भी समझना उपयोगी है.
किसके लिए: Short-term goals, capital stability और low-volatility preference.
2. Debt Mutual Funds: FD के अलावा एक Flexible Debt Option
अगर आपको debt category में market-linked alternative चाहिए, तो Debt Mutual Funds एक option हो सकते हैं. इनमें investor का पैसा bonds, government securities, money market instruments और दूसरे debt securities में लगाया जा सकता है, scheme के mandate के अनुसार.
यह समझना जरूरी है कि debt mutual fund भी risk-free नहीं होता. Interest-rate movement, credit quality और market conditions के कारण NAV ऊपर-नीचे हो सकती है.
SEBI के investor resources में debt funds, liquid funds, overnight funds और दूसरे mutual fund categories की जानकारी उपलब्ध है. SEBI Investor Education on Mutual Funds
₹10 लाख portfolio में Debt Fund की भूमिका
मान लीजिए आप पूरी रकम equity में नहीं डालना चाहते. ऐसे में ₹2 लाख से ₹3 लाख का debt-oriented allocation portfolio की volatility को कम करने में मदद कर सकता है, लेकिन scheme selection और duration को goal के साथ match करना चाहिए.
Debt fund चुनते समय केवल past return न देखें. Portfolio quality, duration, credit exposure, expense ratio और liquidity को भी समझें.
किसके लिए: Medium-term goals, lower equity exposure और portfolio stability चाहने वाले investors.
3. Nifty 50 Index Fund: Long-Term Growth के लिए
अगर आपका investment horizon लंबा है और आप market volatility सह सकते हैं, तो broad-market Index Fund ₹10 लाख के portfolio का growth engine बन सकता है.
Nifty 50 index fund जैसी passive strategy किसी index को track करने की कोशिश करती है, इसलिए आपको individual stocks चुनने की जरूरत कम हो जाती है. SEBI के अनुसार mutual funds diversification और professional management जैसे benefits दे सकते हैं, जबकि securities-market investments में price fluctuation का risk बना रहता है. SEBI Investor: How to Invest
एक जरूरी सवाल: पूरा ₹10 लाख एक साथ लगाएं?
जरूरी नहीं. Lump-sum market entry में timing risk होता है. अगर बाजार में निवेश के तुरंत बाद बड़ी गिरावट आती है, तो investor को psychological pressure हो सकता है.
ऐसी स्थिति में कुछ investors पूरी रकम एक साथ लगाने के बजाय एक planned deployment strategy इस्तेमाल करते हैं, जैसे कुछ रकम शुरुआत में और बाकी रकम अगले कुछ महीनों में निवेश करना. यह return की guarantee नहीं देता, लेकिन entry timing को लेकर discomfort कम कर सकता है.
आपकी strategy तय करते समय हमारा Index Fund vs Mutual Fund guide और Asset Allocation guide भी देख सकते हैं.
किसके लिए: 7+ साल का horizon, wealth creation और higher market risk सहने की क्षमता.
4. Gold ETF: Portfolio Diversification के लिए
सोना portfolio में diversification देने के लिए इस्तेमाल किया जा सकता है. Physical gold की जगह Gold ETF उन investors के लिए एक market-linked route हो सकता है जो exchange-based format में gold exposure चाहते हैं.
Gold में equity जैसी return pattern नहीं होती. इसलिए इसका practical use portfolio के एक हिस्से को अलग asset behaviour देना है, न कि पूरे ₹10 लाख को gold में डालना.
उदाहरण के तौर पर balanced portfolio में 5% से 15% gold allocation रखा जा सकता है, लेकिन exact percentage आपके overall portfolio और goals पर depend करेगा.
SEBI investor education resources ETFs को ऐसे instruments के रूप में बताते हैं जो stock exchanges पर trade होते हैं और diversification व liquidity प्रदान कर सकते हैं, जबकि price fluctuations का risk बना रहता है. SEBI Investor Education Material
किसके लिए: Diversification चाहने वाले investors जो portfolio में equity के अलावा एक अलग asset class रखना चाहते हैं.
5. REIT: छोटे Ticket Size से Real Estate Exposure
अगर आपको commercial real estate का exposure चाहिए लेकिन physical property खरीदने के लिए करोड़ों की जरूरत या property-management का झंझट नहीं चाहिए, तो REITs एक विकल्प हो सकते हैं.
SEBI के अनुसार REITs ऐसे pooled investment vehicles हैं जो real estate assets में निवेश करते हैं. Listed REIT units stock exchanges पर खरीदे और बेचे जा सकते हैं. Investor returns rental income से होने वाले distributions और unit price appreciation, दोनों के जरिए आ सकते हैं, हालांकि दोनों guaranteed नहीं हैं. SEBI Investor: Understanding REITs and INVITs
REIT में ₹10 लाख का कितना हिस्सा?
₹10 लाख का पूरा पैसा REIT में डालना concentration risk बढ़ा सकता है. Portfolio diversification के लिए 5% से 15% जैसा limited allocation कुछ investors के लिए practical हो सकता है, लेकिन final allocation आपके बाकी investments और real-estate exposure पर निर्भर होना चाहिए.
REIT चुनते समय occupancy, tenant concentration, lease profile, debt, distribution history और valuation जैसे factors देखना जरूरी है.
किसके लिए: Diversification और listed real-estate exposure चाहने वाले investors.
₹10 लाख का एक Practical Balanced Allocation
अब एक example लेते हैं. मान लीजिए investor का horizon लंबा है, emergency fund अलग है, कोई high-cost debt नहीं है और वह moderate volatility सह सकता है. ऐसी स्थिति में एक illustrative allocation इस तरह दिख सकता है:
| Option | Illustrative Allocation | Amount | Portfolio Role |
|---|---|---|---|
| Bank FD | 30% | ₹3,00,000 | Stability और liquidity bucket |
| Debt Mutual Fund | 20% | ₹2,00,000 | Debt diversification |
| Nifty 50 Index Fund | 30% | ₹3,00,000 | Long-term growth |
| Gold ETF | 10% | ₹1,00,000 | Diversification |
| REIT | 10% | ₹1,00,000 | Listed real-estate exposure |
| Total | 100% | ₹10,00,000 |
यह allocation किसी व्यक्ति के लिए fixed recommendation नहीं है. उदाहरण के लिए, अगर आपको अगले दो साल में घर खरीदना है, तो equity, Gold ETF और REIT का allocation कम रखना और required money को safer/liquid instruments में रखना ज्यादा relevant हो सकता है.
Goal के हिसाब से ₹10 लाख कैसे सोचें?
| आपकी स्थिति | General Approach |
|---|---|
| 1-3 साल में पैसा चाहिए | Safer और liquid options पर ज्यादा focus |
| 3-7 साल का horizon | Debt + moderate equity mix पर विचार |
| 7+ साल का horizon | Growth assets का proportion बढ़ सकता है |
| High volatility पसंद नहीं | Equity exposure कम रखना बेहतर हो सकता है |
| Real estate already ज्यादा है | REIT allocation को सीमित रखने पर विचार करें |
₹10 लाख Invest करते समय किन गलतियों से बचें?
- पूरी रकम एक ही asset में डालना: Concentration risk बढ़ सकता है.
- सिर्फ past returns देखना: पिछला performance future return की guarantee नहीं है.
- Emergency fund भूल जाना: Invest करने से पहले immediate cash needs अलग रखना जरूरी है.
- Tax ignore करना: FD interest और capital gains के tax impact के बाद actual return कम हो सकता है.
- Market fall में panic selling: Long-term investments में volatility सामान्य हो सकती है, इसलिए horizon पहले तय करें.
- Random stock tips पर पूरी रकम लगाना: ₹10 लाख जैसी बड़ी रकम में capital preservation और diversification महत्वपूर्ण हैं.
भारत में capital gains taxation asset और transaction के प्रकार पर निर्भर करती है. Equity-oriented listed assets के लिए current rules में section 112A के तहत long-term capital gains पर ₹1.25 लाख तक की annual exemption limit और उससे ऊपर 12.5% tax rate का framework लागू है, जबकि short-term specified financial assets पर 20% rate लागू हो सकता है. दूसरी asset classes पर अलग rules हो सकते हैं. इसलिए investment बेचने से पहले applicable tax treatment को current Income Tax Department guidance से verify करें. Income Tax Department: AY 2026-27 guidance
क्या ₹10 लाख को SIP में Convert करना चाहिए?
SIP technically future regular investments के लिए है, लेकिन lump-sum amount को एक साथ equity market में डालने में hesitation हो तो investor कुछ समय के लिए suitable low-volatility parking option में रखकर planned monthly deployment कर सकता है.
यह approach market timing को eliminate नहीं करती. इसका फायदा मुख्य रूप से behavioural comfort और phased entry में हो सकता है. आपके लिए कौन-सा approach suitable है, यह market view से ज्यादा goal, horizon और risk capacity पर depend करना चाहिए.
आप हमारी SIP क्या है? Beginners Guide और SIP में कितने साल तक Invest करना चाहिए? वाली guides भी पढ़ सकते हैं.
₹10 लाख Investment का Simple Rule
एक simple framework याद रखें:
पहले safety, फिर liquidity, फिर growth और उसके बाद diversification.
इसका मतलब यह नहीं कि हर investor को exactly इसी order में पैसा लगाना चाहिए. लेकिन emergency fund और expensive debt की स्थिति clear किए बिना पूरा lump-sum invest करना avoid करना practical हो सकता है.
इसी तरह portfolio में बहुत सारे products भर देना भी diversification नहीं है. अगर आपके पास 10 अलग mutual funds हैं लेकिन सभी लगभग एक जैसे large-cap stocks hold करते हैं, तो actual diversification सीमित हो सकती है.
Frequently Asked Questions
₹10 लाख कहाँ Invest करना सबसे सही है?
एक single “best” option सभी के लिए नहीं होता. Goal और time horizon के आधार पर FD, debt funds, index funds, Gold ETF और REIT जैसे options को अलग-अलग proportions में इस्तेमाल किया जा सकता है.
क्या ₹10 लाख पूरा FD में रखना safe है?
FD में market volatility नहीं होती, लेकिन deposit insurance की सीमा और bank concentration को समझना जरूरी है. DICGC eligible deposits पर एक depositor को एक insured bank में principal और interest मिलाकर अधिकतम ₹5 लाख तक cover देता है.
क्या ₹10 लाख Index Fund में लगा सकते हैं?
लंबे horizon और high market-volatility सहने की क्षमता वाले investor के लिए index fund portfolio का growth portion हो सकता है. Short-term goals के लिए equity exposure अलग तरीके से देखना चाहिए.
Gold ETF में कितना पैसा रखें?
Gold allocation portfolio diversification के लिए रखा जाता है. Exact percentage तय करने से पहले देखें कि आपके पास physical gold, SGB या दूसरे gold-linked assets पहले से कितने हैं.
REIT में ₹1 लाख लगाना कैसा है?
REIT listed real-estate exposure दे सकता है, लेकिन unit prices और distributions दोनों में बदलाव संभव है. REIT को fixed-income product की तरह न देखें.
क्या ₹10 लाख एक साथ invest करना चाहिए?
अगर long-term goal और risk capacity clear है, lump-sum investing एक possible route है. लेकिन market-entry risk से uncomfortable investor phased deployment पर भी विचार कर सकता है.
निष्कर्ष
₹10 लाख को कहाँ Invest करें? इसका जवाब सिर्फ एक product का नाम नहीं है. एक practical portfolio में safety, liquidity, growth और diversification चारों की जरूरत हो सकती है.
FD stability दे सकता है, debt funds portfolio के debt हिस्से को diversify कर सकते हैं, Index Funds long-term growth exposure दे सकते हैं, Gold ETF diversification में मदद कर सकता है और REIT listed real-estate exposure दे सकता है. लेकिन इन सभी investments में risk, liquidity और tax treatment अलग-अलग हैं.
निवेश शुरू करने से पहले अपने goal और time horizon लिखें, emergency money अलग रखें और फिर asset allocation तय करें. जरूरत होने पर SEBI-registered investment adviser से personalised advice लेना उचित हो सकता है.
यह भी पढ़ें: Asset Allocation: उम्र और Salary के हिसाब से Investment | Emergency Fund के बाद पैसा कहाँ Invest करें? | Direct vs Regular Mutual Fund | Index Fund vs Mutual Fund
मुख्य स्रोत: SEBI Investor | DICGC | Income Tax Department
Disclaimer: यह लेख केवल सामान्य सूचनात्मक और शैक्षिक उद्देश्य के लिए है। Mutual Funds, Index Funds, Gold ETF, REITs और अन्य market-linked investments में market risk होता है और returns की कोई guarantee नहीं है। FD interest, capital gains, taxation और निवेश नियम आपकी स्थिति और समय के अनुसार बदल सकते हैं। निवेश से पहले संबंधित product के latest official documents, disclosures और tax rules देखें। यह article व्यक्तिगत investment advice नहीं है। जरूरत होने पर SEBI-registered investment adviser से सलाह लें.