Financial Goals कैसे Set करें? Short, Medium और Long Term Goals का पूरा Guide (2026)
क्या आप हर महीने saving और investing तो करते हैं, लेकिन आपको यह साफ नहीं है कि पैसा आखिर किस लक्ष्य के लिए है? यही वह जगह है जहाँ Financial Goals आपकी personal finance strategy को direction देते हैं। बिना goal के investment अक्सर सिर्फ अलग-अलग products खरीदने तक सीमित रह जाता है। Goal-based planning में आप पहले तय करते हैं कि पैसा किस काम के लिए, कितनी रकम में और कब चाहिए, फिर उसी हिसाब से saving और investment strategy बनाते हैं।
SEBI की investor education guidance भी financial goals को स्पष्ट और time-bound बनाने, उन्हें short, medium और long term में classify करने तथा goal के time horizon और risk appetite के हिसाब से investment plan करने पर जोर देती है।
Financial Goals क्या होते हैं?
Financial goal वह specific आर्थिक target है जिसे आप अपनी income, saving और investments की मदद से भविष्य में हासिल करना चाहते हैं। जैसे emergency fund बनाना, vacation के लिए पैसा जमा करना, higher education के लिए corpus बनाना, घर खरीदना या retirement के लिए wealth create करना।
एक useful financial goal सिर्फ “मुझे ज्यादा पैसा बचाना है” नहीं होता। बेहतर goal ऐसा होता है: “मुझे दिसंबर 2027 तक ₹3 लाख का education fund बनाना है।” इसमें amount और deadline दोनों clear हैं।
Financial Goals Set करना क्यों जरूरी है?
1. आपको investment की सही दिशा मिलती है
जब goal clear होता है तो आप तय कर सकते हैं कि पैसा किस तरह के asset में और कितने समय के लिए लगाना है। SEBI भी goal, investment horizon और risk appetite को साथ में evaluate करने की सलाह देता है।
2. Saving में consistency आती है
“बाद में बचा हुआ पैसा invest करूंगा” की जगह आप हर महीने एक तय रकम अपने goal के लिए अलग करते हैं। इससे saving habit ज्यादा disciplined बनती है।
3. आप short-term और long-term money को mix नहीं करते
दो साल बाद चाहिए पैसे को बहुत volatile investment में रखना और 15 साल बाद के retirement goal को सिर्फ short-term savings में रखना दोनों ही गलत हो सकते हैं। SEBI की guidance स्पष्ट करती है कि short-term goals को inherently long-term और risky avenues पर निर्भर नहीं करना चाहिए, जबकि long-term goals के लिए केवल short-term avenues पर्याप्त growth नहीं दे सकते।
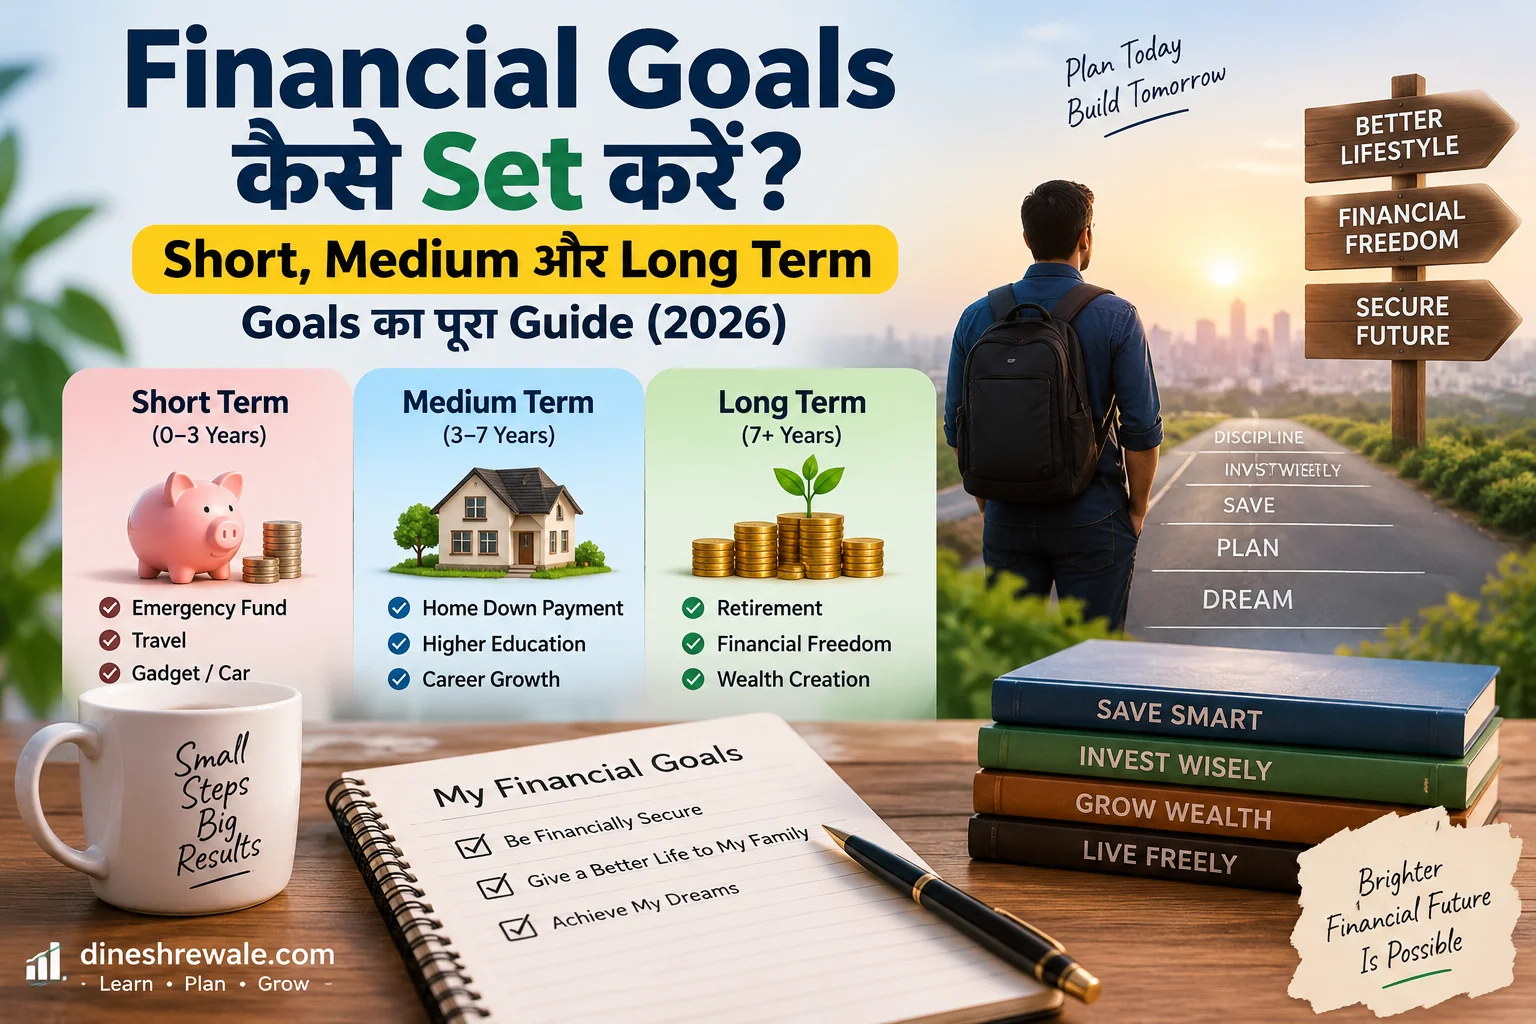
Short, Medium और Long Term Financial Goals क्या हैं?
SEBI की financial education material के अनुसार short-term goals आम तौर पर कुछ महीनों से 1 साल तक, medium-term goals लगभग 1 से 8 साल और long-term goals 8 साल या उससे अधिक horizon वाले हो सकते हैं।
Short-Term Goals: कुछ महीने से 1 साल
इन goals का पैसा जल्दी चाहिए होता है, इसलिए capital safety और liquidity ज्यादा महत्वपूर्ण रहती है। उदाहरण के लिए annual insurance premium, short trip, laptop purchase या छोटा cash buffer।
Medium-Term Goals: 1 से 8 साल
इनमें amount बड़ा हो सकता है और आपके पास compounding के लिए कुछ साल होते हैं। उदाहरण: professional course, car down payment, business setup या property down payment।
Long-Term Goals: 8 साल या उससे अधिक
Retirement, child education, long-term wealth creation और बड़े legacy goals इसके उदाहरण हैं। लंबा horizon volatility को absorb करने की क्षमता दे सकता है, लेकिन इसका मतलब यह नहीं कि हर long-term goal के लिए कोई भी equity investment सही है। Risk आपकी capacity, financial situation और goal timeline से match होना चाहिए।
Financial Goals कैसे Set करें? Step-by-Step Framework
Step 1: सबसे पहले goals की पूरी list बनाएं
अभी के लिए “छोटा-बड़ा” decide करने की जरूरत नहीं है। बस सभी goals लिखें। जैसे emergency fund, vacation, car, home, education, retirement और debt repayment।
Step 2: हर goal को SMART बनाएं
S = Specific: goal स्पष्ट होना चाहिए।
M = Measurable: रकम measurable हो।
A = Achievable: income और current obligations के हिसाब से realistic हो।
R = Realistic: goal आपके available resources से जुड़ा हो।
T = Time-Bound: deadline तय हो।
उदाहरण: “मुझे wealth बनानी है” vague goal है। “मुझे 5 साल में ₹10 लाख का home down-payment corpus बनाना है” ज्यादा useful goal है। SEBI financial education material SMART approach और time-bound targets को स्पष्ट रूप से उपयोगी बताता है।
Step 3: Future cost का अंदाजा लगाएं
आज किसी goal की cost ₹5 लाख है तो जरूरी नहीं कि 5 या 10 साल बाद भी वही रहे। Inflation के कारण future cost बढ़ सकती है। इसलिए long-term goal के लिए current cost के साथ expected inflation को consider करना जरूरी है।
एक simple approximation के लिए future cost = current cost × (1 + inflation rate)years इस्तेमाल किया जा सकता है। उदाहरण के लिए ₹5 लाख का goal 7% annual inflation पर 10 साल में लगभग ₹9.84 लाख हो सकता है। यह illustration है, actual inflation अलग हो सकती है।
Step 4: Goal की deadline तय करें
Deadline तय होते ही monthly saving requirement को calculate करना आसान हो जाता है। ₹3 लाख 3 साल में चाहिए और वही रकम 7 साल में चाहिए, तो दोनों के लिए monthly investment requirement बहुत अलग होगी।
Step 5: Priority तय करें
हर goal equally urgent नहीं होता। पहले essential और protection-oriented goals रखें, फिर lifestyle और aspirational goals। Emergency fund और high-cost debt management जैसी foundations को ignore करके luxury goal fund बनाना practical नहीं है।
Step 6: हर goal का separate funding plan बनाएं
एक single “investment bucket” की जगह goal-wise buckets बनाना tracking को आसान बनाता है। उदाहरण के लिए vacation fund, education fund और retirement corpus को अलग-अलग track करें।
Step 7: Risk को time horizon के साथ match करें
Goal जितना पास होता जाता है, capital protection का महत्व बढ़ता है। Long-term goals volatility को ज्यादा समय तक absorb कर सकते हैं, लेकिन allocation हमेशा आपकी risk tolerance और capacity से match होना चाहिए। SEBI goal-based investing में age, risk appetite, financial situation और investment horizon को ध्यान में रखने की बात करता है।
Step 8: हर साल review और rebalance करें
Income, expenses, family responsibilities और goal amount समय के साथ बदल सकते हैं। इसलिए साल में कम से कम एक बार goals review करें। Salary बढ़ने पर contribution बढ़ाना, deadline बदलने पर allocation adjust करना और portfolio rebalance करना strategy को current रखता है। SEBI financial planning framework में periodic review और rebalancing भी शामिल है।
एक Practical Financial Goals Example
मान लीजिए आपकी monthly take-home income ₹75,000 है। आपके goals हैं:
- 8 महीने में ₹60,000 का laptop
- 3 साल में ₹3 लाख का car down payment
- 7 साल में ₹10 लाख का business corpus
- 20+ साल में retirement corpus
इन चारों goals को एक ही investment strategy से handle करना sensible नहीं होगा। Laptop goal के लिए liquidity और capital stability ज्यादा important होगी। Car और business goals के लिए time horizon के अनुसार conservative से moderate allocation बनाया जा सकता है। Retirement जैसे very long-term goal के लिए growth assets की भूमिका ज्यादा हो सकती है, लेकिन overall portfolio को आपकी risk profile के अनुसार structure करना होगा।
Financial Goal के लिए कितनी Saving करनी चाहिए?
Basic formula है:
Required monthly contribution ≈ Goal amount ÷ remaining months
यह simple division return को ignore करता है, इसलिए investment return applicable होने पर actual required SIP इससे कम हो सकती है। लेकिन planning की शुरुआत के लिए यह quick baseline देता है।
उदाहरण के लिए ₹3 लाख का goal 36 महीने दूर है:
₹3,00,000 ÷ 36 = लगभग ₹8,333 प्रति माह।
अब अगर आपका goal future inflation से बढ़कर ₹3.5 लाख हो जाता है, तो required monthly contribution भी बढ़ेगा। इसीलिए सिर्फ current price देखकर planning करना पर्याप्त नहीं है।
Goals बनाते समय होने वाली 7 Common Mistakes
- बहुत vague goals बनाना
- deadline तय न करना
- inflation ignore करना
- हर goal के लिए same investment product use करना
- short-term money को unnecessarily high-risk assets में रखना
- goal progress को track न करना
- salary या life changes के बाद goals update न करना
Goal Planning को अपने Monthly Budget से कैसे जोड़ें?
Financial goals अलग spreadsheet में रखकर भूल जाने के बजाय उन्हें monthly budget का हिस्सा बनाइए। आपकी take-home income आते ही goal contributions को automate करना आसान तरीका है। उदाहरण के लिए पहले emergency fund और essential obligations, फिर short- और medium-term goals, और साथ में long-term retirement investing। आपकी actual income, debts, family responsibilities और risk capacity के अनुसार proportions बदलेंगे।
इस विषय पर आप dineshrewale.com के Monthly Budget Guide, Emergency Fund Guide, Asset Allocation Guide और Financial Freedom Guide भी पढ़ सकते हैं।
Financial Goals Track करने का Simple Template
एक simple table बनाकर हर goal के लिए ये fields रखें: Goal Name, Current Cost, Future Cost, Target Date, Priority, Current Corpus, Monthly Contribution, Investment Type और Progress %.
हर महीने सिर्फ एक बार update करना भी काफी है। इससे आपको पता रहेगा कि कौन सा goal track पर है और कहाँ contribution बढ़ाने की जरूरत है।
क्या आपको Financial Goals के लिए Financial Advisor की जरूरत है?
Simple goals और straightforward cash-flow situation होने पर आप खुद basic goal planning कर सकते हैं। लेकिन multiple goals, complex tax situations, business income, large inheritance, retirement planning या major asset allocation decisions में qualified professional की independent advice useful हो सकती है। SEBI investor site भी investment decisions में due diligence और registered intermediaries की verification पर जोर देती है।
Final Checklist: आपका Financial Goal सही है या नहीं?
- क्या goal specific है?
- क्या future amount का estimate किया है?
- क्या deadline तय है?
- क्या monthly contribution affordable है?
- क्या goal को सही time horizon में रखा है?
- क्या investment risk goal timeline के अनुसार है?
- क्या आप इसे कम से कम साल में एक बार review करेंगे?
निष्कर्ष
Financial Goals set करना personal finance की सबसे important habits में से एक है। जब आपको पता होता है कि कितना पैसा, किस तारीख तक और किस उद्देश्य के लिए चाहिए, तब budgeting, saving और investing तीनों ज्यादा meaningful हो जाते हैं। शुरुआत perfect plan से नहीं, clear goals की छोटी list से करें। फिर उन्हें Short, Medium और Long Term में classify करें, inflation और timeline को factor करें, हर goal को अलग funding plan दें और समय-समय पर review करें।
सबसे जरूरी बात यह है कि financial planning का उद्देश्य सिर्फ ज्यादा returns कमाना नहीं, बल्कि आपके पैसे को आपकी जिंदगी के जरूरी goals के साथ align करना है।
Disclaimer: यह article केवल educational purpose के लिए है। किसी investment product में पैसा लगाने से पहले उसके risks, costs, suitability और अपने financial circumstances को समझें। जरूरत पड़ने पर SEBI-registered investment professional से सलाह लें।