NPS vs PPF: Retirement के लिए कौन बेहतर? 7 फर्क
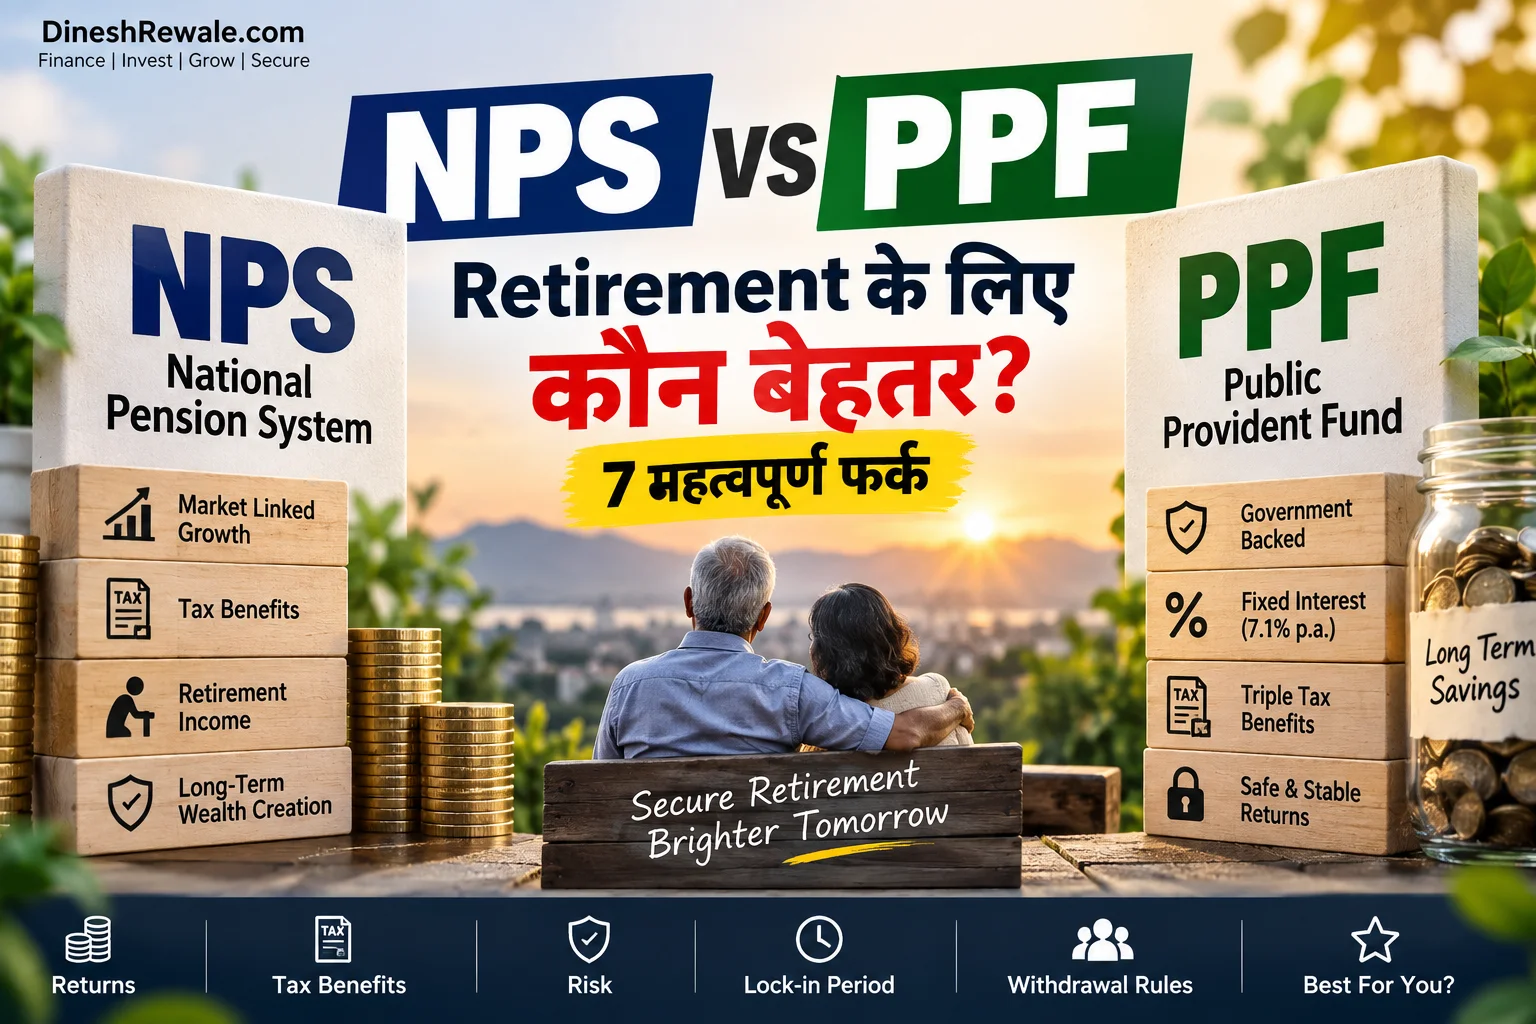
Retirement की planning करते समय अक्सर दो नाम सामने आते हैं: NPS और PPF। दोनों long-term savings के लिए उपयोगी हैं, लेकिन दोनों का काम एक जैसा नहीं है। एक तरफ NPS retirement corpus के साथ pension-oriented structure देता है, जबकि PPF government-backed small savings framework में government-declared interest के साथ long-term wealth building का विकल्प देता है।
इसलिए NPS vs PPF में सवाल सिर्फ यह नहीं है कि कौन ज्यादा return दे सकता है। असली सवाल है कि आपके retirement goal, risk comfort, tax planning, liquidity और retirement के बाद income की जरूरत क्या है।
इस guide में आप दोनों की interest/returns, risk, tax benefits, lock-in, withdrawal rules, retirement income और contribution limits को एक साथ समझेंगे, ताकि अपने portfolio में इनकी भूमिका तय करना आसान हो।
एक नजर में: PPF का focus capital preservation, tax-efficient long-term saving और predictable government-declared interest पर है। NPS का focus retirement accumulation और annuity-based income structure पर है। इसलिए दोनों को एक ही category का product मानना सही नहीं होगा।
NPS क्या है?
National Pension System (NPS) एक defined-contribution retirement savings system है जिसे PFRDA regulate करता है। NPS में आपका पैसा अलग-अलग asset classes और pension fund schemes के माध्यम से invest होता है, इसलिए इसका value market performance से जुड़ा रहता है।
20 जुलाई 2026 के बाद लागू current framework के अनुसार, All Citizen Model में सामान्य exit पर आम तौर पर अधिकतम 80% lump sum लिया जा सकता है और कम-से-कम 20% annuity के लिए इस्तेमाल होता है। कुछ corpus slabs के लिए अलग withdrawal options भी दिए गए हैं। इसलिए exit के समय लागू PFRDA rules को verify करना जरूरी है।
NPS की एक खास बात यह है कि normal exit के लिए eligible होने के बाद भी account को 85 वर्ष की उम्र तक continue किया जा सकता है, applicable rules के अनुसार।
आप पहले से प्रकाशित NPS क्या है? Retirement के लिए कितना निवेश करें? लेख में NPS के basics, contribution और retirement planning को और विस्तार से पढ़ सकते हैं।
PPF क्या है?
Public Provident Fund (PPF) एक long-term government small savings scheme है। वर्तमान में PPF पर 7.1% सालाना ब्याज दर उपलब्ध है। Small savings rates सरकार द्वारा समय-समय पर तय की जाती हैं, इसलिए future rate आज से guaranteed नहीं माना जाना चाहिए।
PPF account की मूल अवधि 15 साल है। इसके बाद इसे 5-5 साल के blocks में extend किया जा सकता है। एक financial year में PPF में अधिकतम ₹1.50 लाख जमा किए जा सकते हैं।
PPF की बड़ी विशेषता इसका tax treatment है। Income Tax Department के अनुसार PPF को Section 10(11) के तहत exempt income framework में रखा गया है और eligible contribution को Section 80C के तहत deduction मिल सकता है, subject to the applicable tax regime and limits.
PPF की basic जानकारी, interest, tax और maturity पर हमारा PPF क्या है? Interest, Tax और Maturity पूरी जानकारी लेख उपयोगी रहेगा।
NPS vs PPF: 7 बड़े फर्क
| पैरामीटर | NPS | PPF |
|---|---|---|
| मुख्य उद्देश्य | Retirement corpus + pension-oriented income | Long-term, relatively stable savings |
| Return nature | Market-linked | Government-declared interest rate |
| Risk | Market risk मौजूद | Market-linked equity risk नहीं |
| Time horizon | Retirement-focused, long term | 15 years + 5-year extensions |
| Retirement exit structure | Normal exit में current framework के अनुसार up to 80% lump sum + at least 20% annuity; कुछ corpus slabs के लिए अलग options उपलब्ध | Maturity पर पूरा balance निकाला जा सकता है; annuity खरीदना जरूरी नहीं |
| Annual contribution cap | PPF जैसी ₹1.50 लाख annual cap नहीं | ₹1.50 लाख प्रति financial year |
| Tax features | Applicable sections के तहत retirement-focused deductions; 80CCD(1B) में ₹50,000 तक extra deduction old-regime conditions में उपलब्ध | Eligible contribution under 80C; interest और qualifying maturity proceeds exempt framework में |
1. Return और interest में सबसे बड़ा फर्क
PPF में return कैसे तय होता है?
PPF का interest market return की तरह ऊपर-नीचे नहीं होता। यह सरकार द्वारा घोषित rate framework पर आधारित है। वर्तमान published information में PPF rate 7.1% प्रति वर्ष है। यह rate भविष्य के लिए fixed promise नहीं है, इसलिए 15 या 20 साल की planning में आज की rate को हमेशा के लिए मान लेना सही नहीं होगा।
NPS में return कैसे काम करता है?
NPS market-linked है। आपके selected asset allocation, pension fund और market performance के आधार पर corpus बढ़ या घट सकता है। इसलिए NPS का return किसी fixed interest rate से compare करना सही नहीं है।
यही वजह है कि NPS और PPF की तुलना करते समय “किसमें interest ज्यादा है?” से पहले “मैं कितना market risk ले सकता हूँ?” पूछना ज्यादा उपयोगी है।
2. Risk के मामले में NPS vs PPF
PPF और NPS का risk profile अलग है। PPF market-linked equity investment नहीं है और इसका interest government-declared rate पर मिलता है। दूसरी तरफ NPS में market exposure हो सकता है, इसलिए short-term value fluctuations संभव हैं।
अगर आपका retirement horizon लंबा है, तो NPS का market exposure growth opportunity दे सकता है। लेकिन इसका मतलब यह नहीं कि NPS का return guaranteed है। Retirement के करीब आते समय volatility को समझना और asset allocation की review करना महत्वपूर्ण है।
3. Lock-in और liquidity किसमें कैसी है?
PPF की मूल maturity 15 साल है। हालांकि account rules के तहत कुछ limited liquidity options भी मिलते हैं। Official PPF Scheme के अनुसार, पांच साल पूरे होने के बाद specified withdrawal rules के तहत partial withdrawal किया जा सकता है। Loan facility भी scheme rules के भीतर उपलब्ध है।
NPS retirement-oriented product है, इसलिए इसका withdrawal structure ज्यादा conditional है। Current PFRDA information के अनुसार specified situations में partial withdrawal किया जा सकता है और premature exit में annuity component भी लागू हो सकता है।
इसलिए emergency fund की जगह NPS या PPF का इस्तेमाल करना practical नहीं है। Emergency money को ऐसी जगह रखना बेहतर है जहाँ जरूरत पड़ने पर access सरल हो।
4. Tax benefits में क्या फर्क है?
PPF का tax treatment
PPF के लिए eligible contribution पर Section 80C के तहत deduction मिल सकता है, subject to the applicable tax regime and the combined ₹1.50 lakh limit. PPF का interest और qualifying maturity amount exempt-income framework में आता है, subject to the applicable provisions.
NPS का tax treatment
NPS में tax benefits अलग-अलग provisions के माध्यम से मिल सकते हैं। Income Tax Department की AY 2026-27 guidance के अनुसार, applicable conditions में Section 80CCD(1B) के तहत ₹50,000 तक की अतिरिक्त deduction उपलब्ध है, जो 80CCD(1) की deduction से अलग है। Employer contribution के लिए Section 80CCD(2) का अलग framework है। इन deductions की eligibility tax regime और taxpayer की स्थिति पर निर्भर करती है।
इसका मतलब यह हुआ कि सिर्फ return नहीं, बल्कि आप कौन-सी tax regime चुनते हैं और employer NPS contribution देता है या नहीं, यह भी decision को प्रभावित कर सकता है।
5. Retirement के बाद income की बात करें तो फर्क साफ है
यहाँ NPS और PPF का उद्देश्य सबसे ज्यादा अलग दिखाई देता है।
PPF maturity पर आप accumulated balance को withdraw कर सकते हैं। PPF आपको अपने आप monthly pension देने वाला product नहीं है। Retirement income बनाने के लिए आपको maturity corpus को आगे किसी income-generating strategy में deploy करना पड़ सकता है।
NPS का design retirement income के लिए ज्यादा directly linked है क्योंकि normal exit पर annuity component का प्रावधान है। 20 जुलाई 2026 के बाद के current framework में सामान्य exit पर आम तौर पर 80% तक lump sum और कम-से-कम 20% annuity की व्यवस्था है। कुछ corpus slabs, खासकर ₹12 लाख तक के corpus, के लिए अलग withdrawal options भी उपलब्ध हैं।
ध्यान रखें कि annuity income की taxation अलग से लागू हो सकती है। PFRDA की current FAQ के अनुसार retirement exit पर annuity purchase के लिए उपयोग की गई eligible राशि पर exit time tax treatment अलग है, जबकि बाद में मिलने वाली annuity income applicable slab के अनुसार taxable होती है।
6. कितनी रकम invest कर सकते हैं?
PPF में annual maximum contribution ₹1.50 लाख है। इसका मतलब है कि अगर आप retirement के लिए इससे बहुत बड़ा annual contribution करना चाहते हैं, तो PPF अकेले पर्याप्त vehicle नहीं होगा।
NPS में PPF जैसा ₹1.50 लाख annual contribution ceiling नहीं है। इसलिए higher retirement savings के लिए NPS में बड़े contributions किए जा सकते हैं, हालांकि tax deduction और investment decision को contribution amount से अलग समझना जरूरी है।
उदाहरण के लिए, कोई व्यक्ति PPF का full annual limit भरने के बाद retirement goal के लिए NPS या अन्य diversified investments का उपयोग कर सकता है। यह approach product के बजाय goal के हिसाब से allocation करने की अनुमति देता है।
7. किसके लिए NPS ज्यादा relevant हो सकता है?
ऐसे व्यक्ति जिनका primary objective retirement corpus और post-retirement income structure बनाना है, वे NPS को retirement portfolio के हिस्से के रूप में consider कर सकते हैं। खासकर तब जब लंबी investment horizon हो और market-linked assets के उतार-चढ़ाव को समझते हुए निवेश किया जा रहा हो।
NPS की उपयोगिता employer contribution, tax eligibility, age, retirement horizon और desired pension income से भी प्रभावित होती है।
आपके लिए NPS पर कितना invest करना चाहिए, इसे समझने के लिए NPS retirement investment guide भी पढ़ें।
किसके लिए PPF ज्यादा relevant हो सकता है?
अगर आप long-term savings में stability, government-declared interest framework और tax-efficient accumulation चाहते हैं, तो PPF आपके overall financial plan में उपयोगी हो सकता है। खासकर conservative investors के लिए यह retirement corpus का एक relatively stable हिस्सा बना सकता है।
PPF को सिर्फ retirement के लिए ही नहीं, बल्कि बच्चों के future, long-term goals और 15+ साल के horizon वाले goals के लिए भी इस्तेमाल किया जा सकता है। हालांकि annual contribution cap और long tenure को ध्यान में रखना चाहिए।
PPF में हर महीने ₹5,000 जमा करने के संभावित corpus की समझ के लिए हमारा PPF ₹5,000 monthly calculation लेख देखें।
NPS vs PPF: क्या दोनों में निवेश किया जा सकता है?
हाँ। यह एक practical possibility है, क्योंकि दोनों की भूमिका अलग हो सकती है। एक retirement-oriented market-linked component दे सकता है, जबकि दूसरा long-term stable savings bucket की तरह काम कर सकता है।
उदाहरण के तौर पर कोई investor अपने retirement plan में:
- PPF को stable, tax-efficient long-term bucket के रूप में रख सकता है।
- NPS को retirement corpus और annuity-oriented income के लिए use कर सकता है।
- इसके अलावा EPF, mutual funds, fixed income या अन्य assets को भी goal और risk profile के अनुसार जोड़ सकता है।
ऐसे mix का उद्देश्य किसी एक product को “winner” बनाना नहीं, बल्कि retirement portfolio में अलग-अलग jobs को स्पष्ट करना है।
₹5,000 महीने का उदाहरण कैसे समझें?
मान लीजिए आप हर महीने ₹5,000 retirement planning के लिए अलग रखना चाहते हैं। पूरा ₹5,000 PPF में रखने पर annual contribution ₹60,000 होगा, जो PPF की annual limit के अंदर है। लेकिन PPF rate future में बदल सकती है और 15 साल बाद maturity amount आज की rate पर तय नहीं होगी।
अगर यही ₹5,000 NPS में रखा जाए, तो corpus market performance और selected allocation के अनुसार अलग हो सकता है। इसलिए NPS calculation में assumed return लेना पड़ता है, और यह actual return की guarantee नहीं होती।
इस example से एक बात साफ है: monthly contribution समान होने से products equivalent नहीं हो जाते। उनकी liquidity, risk, tax और retirement-exit structure अलग है।
Decision लेने से पहले 6 सवाल खुद से पूछें
- Retirement तक आपके पास कितने साल बचे हैं?
- आप कितना market risk comfortably ले सकते हैं?
- आपको retirement के बाद lump sum ज्यादा चाहिए या regular income?
- आपकी current tax regime कौन-सी है?
- क्या employer NPS contribution देता है?
- आपके पास EPF, PPF, mutual funds या अन्य retirement assets पहले से कितने हैं?
इन सवालों के जवाब अक्सर यह तय कर देते हैं कि आपको NPS, PPF या दोनों में allocation रखना चाहिए। Goal-setting पर practical framework के लिए Financial Goals कैसे Set करें? भी पढ़ें।
NPS vs PPF: अंतिम निष्कर्ष
NPS vs PPF में एक universal winner नहीं है। दोनों अलग जरूरतों को address करते हैं। NPS retirement-focused, market-linked और annuity-oriented framework है, जबकि PPF long-term savings, government-declared interest और tax-efficient accumulation के लिए जाना जाता है।
अगर आपका सबसे बड़ा focus retirement income structure है, तो NPS की pension-oriented design को समझना जरूरी है। अगर आपका focus stable long-term savings और tax-efficient corpus है, तो PPF relevant हो सकता है। कई investors के लिए दोनों का combination भी practical हो सकता है, बशर्ते overall asset allocation और retirement goal स्पष्ट हो।
सबसे जरूरी बात यह है कि retirement planning किसी एक product के नाम से पूरी नहीं होती। आपका retirement corpus आपकी age, income, savings rate, time horizon, existing assets, inflation और desired lifestyle पर निर्भर करता है।
अक्सर पूछे जाने वाले सवाल
क्या NPS और PPF दोनों में निवेश कर सकते हैं?
हाँ। दोनों की structure और objective अलग हैं, इसलिए eligible investor अपने retirement plan में दोनों का उपयोग कर सकता है।
NPS में retirement पर कितना पैसा lump sum मिलता है?
20 जुलाई 2026 के बाद के current All Citizen Model framework में सामान्य exit पर आम तौर पर अधिकतम 80% lump sum और कम-से-कम 20% annuity की व्यवस्था है। ₹12 लाख तक के corpus के लिए कुछ अलग withdrawal options भी उपलब्ध हैं। लागू exit category और scheme-specific rules के अनुसार प्रावधान अलग हो सकते हैं।
PPF की maturity कितने साल में होती है?
PPF की मूल maturity 15 साल है। इसके बाद account को 5-5 साल के block में extend किया जा सकता है।
क्या PPF का interest हमेशा 7.1% रहेगा?
नहीं। 7.1% current published rate है। Small savings interest rates सरकार द्वारा समय-समय पर तय की जाती हैं, इसलिए future rates बदल सकती हैं।
क्या NPS का return guaranteed है?
नहीं। NPS market-linked है। Actual returns selected scheme, asset allocation और market performance पर निर्भर करते हैं।
क्या PPF retirement के लिए पर्याप्त है?
यह आपके retirement goal और required corpus पर निर्भर करता है। PPF में annual contribution cap ₹1.50 लाख है, इसलिए बड़े retirement goals में इसे दूसरे retirement assets के साथ combine करना पड़ सकता है।
आधिकारिक संदर्भ
PFRDA: NPS All Citizen Model | PFRDA: NPS Exit Regulations, amended 20 July 2026 | India Post: PPF rates and limits | India Post: PPF Scheme 2019 | Income Tax Department: Exempt Income | Income Tax Department: AY 2026-27
Disclaimer: यह लेख केवल सामान्य informational और educational purpose के लिए है। NPS के returns market-linked होते हैं और guaranteed नहीं हैं। PPF की interest rate भी समय-समय पर सरकार द्वारा बदली जा सकती है। Tax rules, exit rules, annuity conditions, contribution provisions और अन्य regulations समय के साथ बदल सकते हैं। किसी investment, tax planning या retirement decision से पहले लागू official rules और अपनी व्यक्तिगत financial स्थिति की समीक्षा करें।