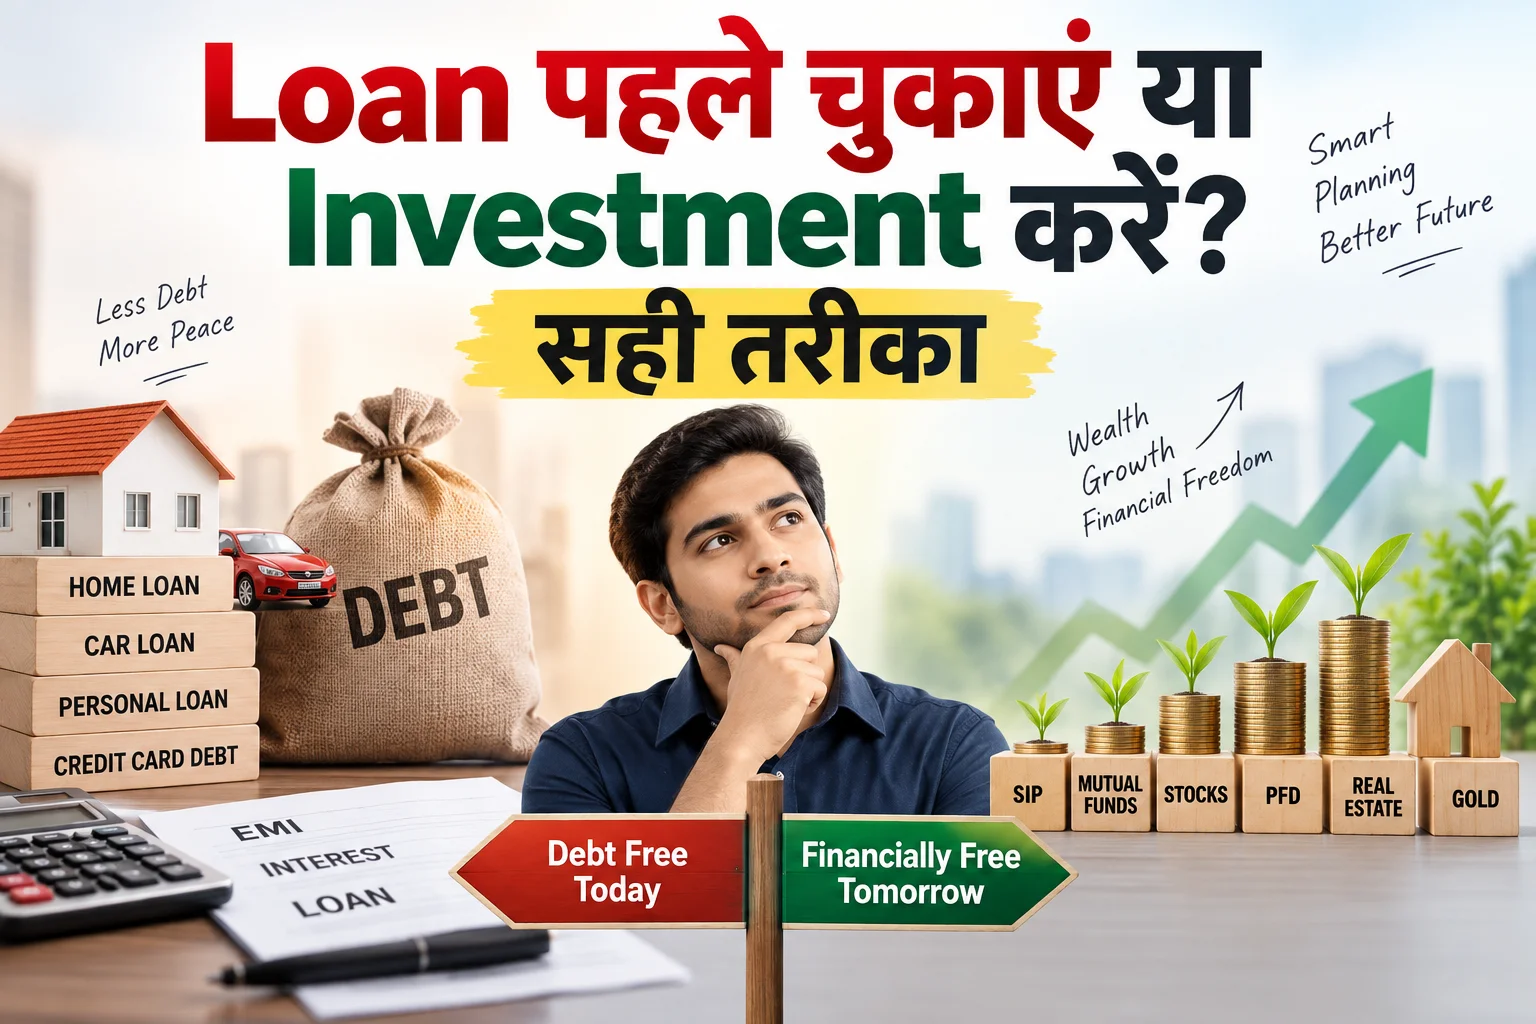
Loan पहले चुकाएं या Investment करें? सही तरीका और Decision Rule
Loan पहले चुकाएं या Investment करें? यह सवाल लगभग हर उस व्यक्ति के सामने आता है जो एक साथ EMI भी भर रहा है और wealth create भी करना चाहता है। इसका कोई एक universal answer नहीं है। सही फैसला आपके loan की effective cost, investment के realistic after-tax return, emergency fund, cash-flow और financial goals को साथ देखकर लिया जाता है।
इस guide में आप एक practical framework सीखेंगे जिससे आप तय कर सकें कि आपकी स्थिति में Debt Repayment बेहतर है, Investment बेहतर है या दोनों का balance रखना चाहिए।
Loan चुकाना और Investment करना एक साथ क्यों मुश्किल लगता है?
मान लीजिए आपके पास हर महीने अतिरिक्त ₹20,000 बचते हैं। आप उस रकम से loan का principal कम कर सकते हैं या SIP/investment शुरू कर सकते हैं। Loan prepayment से आगे का कुछ interest बच सकता है, जबकि investment future wealth बनाने का मौका देता है लेकिन return guaranteed नहीं होता।
यही सबसे महत्वपूर्ण फर्क है: loan prepayment का benefit comparatively predictable है, जबकि investment return uncertain है। SEBI भी निवेश का फैसला risk, time horizon, goals और asset allocation को ध्यान में रखकर लेने की सलाह देता है। Mutual funds में returns assured नहीं होते। SEBI Investor: Investment Risk Management और AMFI: Mutual Fund Risks देखें।
सबसे पहले ये 5 चीजें check करें
1. Loan की interest rate
6.5% से 9% जैसा low-cost long-term home loan और 16% या उससे ज्यादा cost वाला unsecured loan एक जैसी स्थिति नहीं है। जितना महंगा loan, उतनी मजबूत prepayment की priority.
2. Investment का realistic after-tax return
Loan की 10% rate को investment के 12% या 15% expected return से सीधे compare करना सही नहीं है। Investment return को tax, fees, volatility और actual realised return के risk के साथ देखें। Expected return को guaranteed return न मानें।
3. Emergency Fund
अगर आपके पास पर्याप्त emergency fund नहीं है तो पूरा surplus loan prepayment में डालना ठीक नहीं है। Cash buffer के बिना अचानक खर्च आने पर आपको फिर से महंगा debt लेना पड़ सकता है। कुछ महीनों के essential expenses का liquid reserve आपकी income stability और family responsibilities के हिसाब से रखें।
आप Emergency Fund vs FD: पैसा कहाँ रखना बेहतर है? भी पढ़ सकते हैं।
4. Loan का type
Credit card debt, personal loan, consumer loan और home loan को एक ही rule से न देखें। High-cost unsecured debt को wealth building से पहले कम करना अक्सर ज्यादा sensible होता है।
5. Investment goal और time horizon
अगर पैसा 1 से 3 साल में चाहिए तो volatile equity exposure से सावधानी रखें। SEBI के investor guidance के अनुसार short-term goals के लिए high-risk assets से सावधानी और long-term goals के लिए goal-appropriate asset allocation जरूरी है।
सबसे आसान Decision Rule
Loan effective cost > realistic after-tax investment return: loan repayment को priority दें।
Loan effective cost < realistic after-tax investment return: long-term investing जारी रखना reasonable हो सकता है, खासकर low-cost debt और अच्छी risk capacity के साथ।
दोनों करीब हैं: 100% एक तरफ जाने के बजाय split strategy practical हो सकती है।
ध्यान रखें, यह mathematical guarantee नहीं है। Loan interest saving comparatively predictable है, जबकि market-linked investment return नहीं।
Loan Type के हिसाब से सही Priority
| Loan | सामान्य Priority | क्यों? |
|---|---|---|
| Credit card outstanding | बहुत High | Interest cost बहुत ज्यादा हो सकती है और compounding आपके खिलाफ काम करती है। |
| High-cost personal loan | High | Fixed EMI के साथ interest outgo wealth creation को दबा सकता है। |
| Consumer loan | High से Medium | Effective cost और remaining tenure देखकर फैसला करें। |
| Home loan | Medium | Lower-cost, long-tenure debt होने के कारण investing के साथ balance संभव है। |
| Low-cost education loan | Case-by-case | Interest cost, tax treatment और career benefit को साथ देखें। |
यह table कोई fixed rule नहीं है। अपने actual borrowing cost, fees, tax impact और remaining tenure को देखकर निर्णय लें।
Loan Interest को Return की तरह क्यों देखें?
जब आप loan principal prepay करते हैं, तो future interest का एक हिस्सा बच सकता है। यही prepayment का economic benefit है। इसे investment return के साथ compare करते समय certainty सबसे महत्वपूर्ण है। Equity market का return positive भी हो सकता है और negative भी, लेकिन loan prepayment से मिलने वाली interest saving lender के amortisation schedule के अनुसार comparatively predictable होती है।
इसी वजह से high-interest debt के मामले में prepayment को केवल खर्च घटाने के रूप में नहीं, बल्कि risk-adjusted financial benefit के रूप में देखना उपयोगी है।
Expected Return और Guaranteed Saving में फर्क
मान लीजिए किसी investment का long-term expected return 12% है और loan rate 10% है। कागज पर 2 percentage points का gap दिखता है, लेकिन यह guaranteed profit नहीं है। Investment में volatility, taxes, charges और timing risk हो सकते हैं।
अगर return gap छोटा है, तो liquidity और risk tolerance का weight बढ़ जाता है। Historical return को future certainty की तरह इस्तेमाल न करें।
After-Tax Comparison कैसे करें?
Practical calculation के लिए तीन numbers लिखें:
- Loan की effective annual cost, जिसमें actual interest और applicable charges शामिल हों।
- Investment का realistic after-tax expected return, न कि केवल headline return assumption।
- Risk adjustment, यानी market गिरने पर क्या आप investment को बेचने के लिए मजबूर हो सकते हैं?
उदाहरण के लिए, अगर loan की effective cost 11% है और investment का realistic expected return 11% से 12% के बीच है, तो केवल छोटा return gap देखकर debt बनाए रखना जरूरी नहीं। Practical outcome liquidity और market conditions से बदल सकता है।
Prepayment के बाद EMI घटाएं या Tenure?
Partial prepayment के बाद lender की terms के अनुसार EMI कम करने या tenure घटाने जैसे विकल्प हो सकते हैं। अगर आपका लक्ष्य कुल interest saving है और monthly cash-flow manageable है, तो tenure reduction कई मामलों में ज्यादा interest बचा सकता है। EMI reduction immediate cash-flow relief देता है, लेकिन loan लंबे समय तक चल सकता है। इसलिए prepayment के बाद total remaining interest को भी देखें।
छोटा Loan पहले खत्म करें या High-Interest Loan?
दो popular approaches हैं। Highest-interest-first method में सबसे महंगे debt को पहले खत्म किया जाता है। Smallest-balance-first method में छोटा debt पहले खत्म करके motivation और monthly cash-flow बढ़ाने की कोशिश की जाती है।
Pure mathematics में highest-interest-first मजबूत रहता है, लेकिन behaviour भी matter करता है। वह system चुनें जिसे आप लंबे समय तक बिना टूटे follow कर सकें।
Investment पूरी तरह बंद करने की जगह Step-Up Strategy
अगर आपका home loan comparatively low-cost है, तो investing को zero करने के बजाय base SIP चालू रखी जा सकती है। Salary increment या annual bonus का कुछ हिस्सा prepayment में और कुछ हिस्सा investment में भेजें। इससे debt reduction और compounding दोनों चलते रहते हैं।
तीन Real-World Case Studies
Case 1: Credit Card Debt + SIP
मान लीजिए आपके पास revolving credit-card balance है और साथ में equity SIP चल रही है। यहाँ high-cost debt को control करना अधिक urgent हो सकता है। Emergency fund की स्थिति देखकर SIP को maintain, reduce या temporarily pause करने का फैसला करें, लेकिन महंगे revolving debt को केवल market return की उम्मीद में ignore न करें।
Case 2: Home Loan + Long-Term SIP
आपके पास 8.5% home loan है, emergency fund मौजूद है और retirement के लिए 15 साल का horizon है। यहाँ 100% prepayment जरूरी नहीं। Regular SIP और partial prepayment दोनों को साथ चलाना reasonable हो सकता है, खासकर जब EMI comfortable हो और आप market volatility सह सकते हों।
Case 3: Unstable Income + EMI Pressure
अगर income variable है, emergency fund छोटा है और EMI fixed है, तो liquidity का value बढ़ जाता है। पूरे surplus को loan में डालने की बजाय पहले cash buffer मजबूत करें। उसके बाद high-cost debt को reduce करें और investment contribution को धीरे-धीरे बढ़ाएं।
Bonus, Increment या Windfall का पैसा कहाँ लगाएं?
एक बड़ी रकम मिलने पर पूरी राशि investment या पूरी राशि prepayment में लगाना जरूरी नहीं। पहले emergency fund top-up, फिर high-interest debt, फिर long-term goal investment और उसके बाद low-cost loan prepayment जैसे buckets बना सकते हैं।
एक useful test है: क्या इस रकम से future mandatory interest घट रहा है, या decision mostly expected market gain पर निर्भर है?
Loan खत्म होने के बाद EMI को Invest करें
Loan पूरी तरह खत्म होने के बाद free cash-flow को lifestyle inflation में जाने देना common mistake है। अगर ₹30,000 की EMI free हुई है तो उसके बड़े हिस्से का automated SIP या goal-based investment शुरू करना debt-free होने के financial benefit को wealth creation में बदल सकता है।
Decision लेने से पहले यह 10-Point Checklist
Mathematics को थोड़ा और आसान बनाएं
अगर आप numbers के आधार पर फैसला लेना चाहते हैं, तो एक simple principle याद रखें: prepayment का return आपकी loan cost के आसपास होता है, जबकि investment return probability और risk के साथ आता है। इसलिए investment का expected return जितना uncertain होगा, उतना ही बड़ा return premium चाहिए ताकि अतिरिक्त risk justify हो सके।
मान लीजिए loan की effective cost 12% है और आप किसी market-linked asset से 13% return की उम्मीद कर रहे हैं। केवल 1 percentage point के expected gap के लिए पूरा surplus investment में डालना जरूरी नहीं। इसके विपरीत, अगर loan 7% का है, horizon 15 साल का है, emergency fund मजबूत है और आपकी asset allocation risk-appropriate है, तो investing को पूरी तरह बंद करना भी जरूरी नहीं।
Prepayment बनाम Investment: सबसे जरूरी 7 सवाल
- क्या loan की cost fixed है या floating? Floating rate बदलने पर future EMI या tenure बदल सकता है।
- क्या investment guaranteed है? अगर नहीं, तो risk premium जोड़कर सोचें।
- क्या आपका goal long-term है? Short-term requirement हो तो liquidity और capital protection ज्यादा महत्वपूर्ण हो सकती है।
- क्या emergency fund अलग रखा है? अगर नहीं, तो पहले cash buffer बनाएं।
- क्या high-interest debt बाकी है? अगर हाँ, तो उसे low-cost home loan के साथ confuse न करें।
- क्या tax benefit वास्तव में मिल रहा है? Eligibility और tax regime verify करें।
- क्या prepayment के बाद monthly surplus invest करने की discipline है? अगर नहीं, तो केवल debt-free होने की खुशी में future wealth creation कमजोर पड़ सकती है।
Debt और Investment का Balance आपकी Personality पर भी निर्भर करता है
दो लोग एक ही interest rate पर अलग decision ले सकते हैं और दोनों के लिए फैसला सही हो सकता है। एक investor market volatility आसानी से सह सकता है और 15 साल का horizon रखता है। दूसरा व्यक्ति debt-free होने को बहुत अधिक महत्व देता है और lower volatility चाहता है।
इसलिए personal finance में optimal answer हमेशा mathematically maximum wealth नहीं होता। ऐसा plan अधिक उपयोगी है जिसे आप लगातार follow कर सकें, emergency में टूटे नहीं और आपको हर महीने financial stress में न रखे।
कब 100% Loan Repayment की ओर जाएं?
100% prepayment की तरफ जाना तब अधिक logical हो सकता है जब loan cost बहुत high हो, income stable हो, emergency fund पर्याप्त हो, future goals के लिए अलग investment व्यवस्था हो और prepayment से meaningful interest saving हो।
कब 100% Investment पर जाना सही नहीं है?
जब loan महंगा है, income uncertain है, emergency fund नहीं है या investment goal short-term है, तब पूरा surplus market-linked assets में डालना aggressive decision हो सकता है। केवल historical returns देखकर ऐसा फैसला न लें।
सबसे Practical Answer: Core + Accelerator
कई households के लिए एक useful system है Core + Accelerator। Core हिस्सा आपकी mandatory financial safety और minimum long-term investing को बनाए रखता है। Accelerator हिस्सा high-interest debt या partial home-loan prepayment जैसी priority को target करता है।
उदाहरण के लिए, पहले एक fixed SIP और emergency-fund contribution तय करें। इसके बाद monthly surplus को loan prepayment और additional investment के बीच split करें। Salary increase, bonus या tax refund जैसी irregular income को accelerator bucket में डालना आसान होता है।
अपने Decision को हर साल Recalculate क्यों करें?
आज का फैसला हमेशा पांच साल बाद भी सही हो, यह जरूरी नहीं। आपकी salary बढ़ सकती है, loan rate बदल सकती है, tax rules बदल सकते हैं, family responsibilities बढ़ सकती हैं और investment horizon छोटा हो सकता है। इसलिए एक annual review रखें।
Review के समय केवल portfolio return न देखें। Debt outstanding, total interest remaining, emergency reserve, goal progress और monthly free cash-flow पांचों को साथ देखें। यही holistic view आपको over-investing या unnecessary prepayment दोनों से बचा सकता है।
अब फिर से अपना फैसला इन 10 सवालों से check करें:
- Loan का exact interest rate लिखें।
- Remaining principal और tenure देखें।
- Prepayment से future interest saving estimate करें।
- Emergency fund का current amount जाँचें।
- Tax regime और applicable deductions verify करें।
- Investment का time horizon तय करें।
- Investment return को guaranteed न मानें।
- Prepayment charges और lender terms पढ़ें।
- Income stability और future large expenses देखें।
- हर 6 से 12 महीने review करें।
। Loan interest saving comparatively predictable है, जबकि market-linked investment return नहीं।
कब पहले Loan चुकाना चाहिए?
High-interest debt होने पर
Credit card rollover या महंगे personal debt के साथ equity SIP बढ़ाते रहना अक्सर गलत priority हो सकती है। महंगे debt को aggressive तरीके से कम करना financial risk घटाता है।
Debt आपकी cash-flow capacity दबा रहा हो
अगर EMI आपकी monthly income का बड़ा हिस्सा खा रही है और हर महीने financial pressure बना रहता है, तो debt reduction future flexibility बढ़ा सकता है।
Emergency fund पहले से बना हो
जब liquid cash buffer सुरक्षित है और उसके बाद surplus बचता है, तब prepayment ज्यादा comfortable हो जाता है।
Prepayment से meaningful interest saving हो
अपना amortization schedule देखें। खासकर long-tenure loan में principal जल्दी कम करने से future interest outgo घट सकता है।
कब Investment जारी रखना बेहतर हो सकता है?
Low-cost loan और long-term horizon
Reasonable-cost home loan के साथ 10 से 20 साल का investment horizon अलग decision बना सकता है। Long-term equity investment में volatility रहती है, लेकिन लंबा horizon उसे manage करने का समय देता है।
Emergency fund और protection तैयार हो
Financial safety net के बाद investment strategy ज्यादा टिकाऊ होती है क्योंकि आपको market गिरने पर forced selling की जरूरत कम पड़ती है।
Tax benefits लागू हों
Home loan का tax treatment आपकी effective cost बदल सकता है। Income Tax Department की AY 2026-27 guidance के अनुसार Section 24(b) में old tax regime के तहत self-occupied house property के interest पर सामान्यतः ₹2 लाख तक deduction उपलब्ध हो सकती है, subject to applicable conditions. Income Tax Department: AY 2026-27 guidance देखें। Sections 80EE और 80EEA specific loan-sanction periods और conditions से जुड़े हैं, इसलिए इन्हें automatic benefit न मानें।
Investing habit को बचाए रखना हो
Loan खत्म करने के लिए investing पूरी तरह बंद कर देने से compounding की continuity टूट सकती है। Low-cost debt होने पर छोटी SIP जारी रखकर partial prepayment करना कई लोगों के लिए balanced solution हो सकता है।
₹20,000 Extra का Practical Example
मान लीजिए आपके पास हर महीने ₹20,000 extra हैं। Home loan 8.5% का है और आप long-term equity investment से 12% expected return मानते हैं। केवल 8.5% बनाम 12% देखकर investment चुनना अधूरा analysis होगा, क्योंकि 12% guaranteed नहीं है।
ऐसी स्थिति में एक possible balanced approach ₹10,000 prepayment + ₹10,000 long-term SIP हो सकती है। यह कोई universal formula नहीं है। Exact split आपकी liquidity, tax position, goals और risk capacity पर निर्भर करेगा।
High-Interest Loan के साथ क्या करें?
मान लीजिए unsecured loan की effective cost 17% है। तब 10% या 12% expected-return market investment को priority देना मजबूत decision नहीं माना जाएगा, खासकर जब return uncertain हो।
- पहले emergency fund तैयार करें।
- जरूरी insurance और financial protection देखें।
- High-interest debt aggressively reduce करें।
- Debt कम होने के बाद investment contribution बढ़ाएं।
Home Loan के मामले में अलग सोच क्यों जरूरी है?
Home loan long-tenure और comparatively lower-cost debt हो सकता है, इसलिए हर extra rupee को prepayment में डालना जरूरी नहीं। दूसरी तरफ इसे बिना analysis के पूरी tenure तक चलाना भी optimal नहीं हो सकता।
- Effective interest rate
- Remaining tenure और outstanding principal
- Prepayment से होने वाली interest saving
- Applicable tax benefits
- Investment horizon और risk capacity
- Income stability और future goals
Floating-rate loans में rate reset आपकी EMI या tenure को प्रभावित कर सकता है। RBI की guidance के अनुसार applicable floating-rate EMI based personal loans में borrowers को reset के समय कुछ options, including prepayment, दिए जाने चाहिए, subject to applicable instructions and lender terms. RBI guidance देखें।
4-Level Priority Framework
Level 1: Financial Safety
Cash-flow stability, emergency fund और जरूरी insurance को पहले रखें। बिना safety net के aggressive prepayment या aggressive investing दोनों risky हो सकते हैं।
Level 2: Toxic Debt
High-interest credit card balances और महंगे unsecured loans को priority दें।
Level 3: Goal-Based Investing
Retirement, children education या दूसरे long-term goals के लिए disciplined investing की continuity बनाए रखें, जहाँ आपकी financial capacity अनुमति देती हो।
Level 4: Low-Cost Debt vs Wealth Creation
अब home loan जैसे relatively lower-cost debt और long-term investment के बीच balance तय करें। यहीं partial prepayment plus investing strategy सबसे उपयोगी हो सकती है।
Simple Scoring Method
| Factor | क्या देखें? |
|---|---|
| Loan interest | जितना ज्यादा, उतनी prepayment priority |
| Investment horizon | जितना लंबा, उतना long-term investing के पक्ष में |
| Emergency fund | कम है तो पहले liquidity |
| Income stability | कम stability में debt reduction और cash buffer का weight बढ़ाएं |
| Risk tolerance | कम risk capacity में predictable debt saving को अधिक महत्व दें |
| Tax benefit | Valid tax benefit loan की effective cost बदल सकता है |
यह scoring tool exact financial formula नहीं है। इसका उद्देश्य blind decision से बचना है।
Loan Prepayment की 6 Common Mistakes
- Emergency fund खाली करना: पूरा cash loan में डालकर liquidity खत्म न करें।
- महंगे debt को ignore करना: low-cost home loan पर focus करते हुए credit card debt को पीछे न छोड़ें।
- Tax benefit को overestimate करना: deduction eligibility और tax regime verify करें।
- Investment return को guaranteed मानना: market-linked returns uncertain होते हैं।
- Prepayment terms न देखना: lender की current charges और conditions पढ़ें।
- Goal investing पूरी तरह बंद करना: long-term compounding की continuity पर भी विचार करें।
Balanced Strategy कैसे बनाएं?
- Emergency fund बनाएं और उसे liquid रखें।
- High-interest debt कम करें या खत्म करें।
- Eligible tax benefits और applicable rules समझें।
- Long-term SIP जारी रखें जहाँ cash-flow अनुमति देता हो।
- Low-cost loan पर partial prepayment करें जब interest saving meaningful हो।
- हर 6 से 12 महीने review करें, क्योंकि income, interest rates, goals और risk capacity बदल सकती है।
Debt-Free होना भी एक Financial Return है
Personal finance में return सिर्फ portfolio value नहीं है। अगर loan कम होने से आपकी EMI घटती है, financial stress कम होता है और future cash-flow बेहतर होता है, तो उसका real-life value है। उसी तरह long-term investing future goals के लिए capital बनाती है। सही strategy वह है जो financial resilience और wealth creation दोनों को साथ लेकर चले।
तो आखिर पहले Loan चुकाएं या Investment करें?
High-interest loan है? पहले loan repayment की ओर झुकें।
Emergency fund नहीं है? पहले liquidity और financial safety बनाएं।
Low-cost home loan है और long-term investment horizon है? दोनों को balance करना अक्सर ज्यादा sensible हो सकता है।
Loan rate और realistic after-tax investment return करीब हैं? Split strategy पर विचार करें और risk capacity को weight दें।
सबसे जरूरी बात: loan interest को guaranteed saving और investment return को uncertain return की तरह देखें। यही फर्क आपको बेहतर financial decision लेने में मदद करता है।
Bottom Line
Loan पहले चुकाएं या Investment करें, इसका सही जवाब आपकी पूरी financial situation देखकर ही मिलता है। High-cost debt को तेजी से कम करना सामान्यतः मजबूत शुरुआत है, जबकि low-cost long-term debt के साथ disciplined investing जारी रखना कई मामलों में balanced approach हो सकती है।
अपना फैसला financial safety, debt की वास्तविक cost और long-term wealth creation के बीच balance करके लें। यही approach आपको सिर्फ EMI कम करने या investment बढ़ाने के बजाय एक मजबूत financial plan बनाने में मदद करेगी।
महत्वपूर्ण Disclaimer
यह article केवल educational और general informational purpose के लिए है। Loan prepayment, tax treatment और investment decisions आपकी income, loan agreement, tax regime, risk profile और individual goals पर निर्भर करते हैं। Specific financial decision से पहले अपने lender की current terms और लागू tax rules की जाँच करें तथा जरूरत होने पर qualified financial or tax professional से सलाह लें।