FD अब CAS में दिखेगा: RBI के नए Rule से 5 बड़े बदलाव
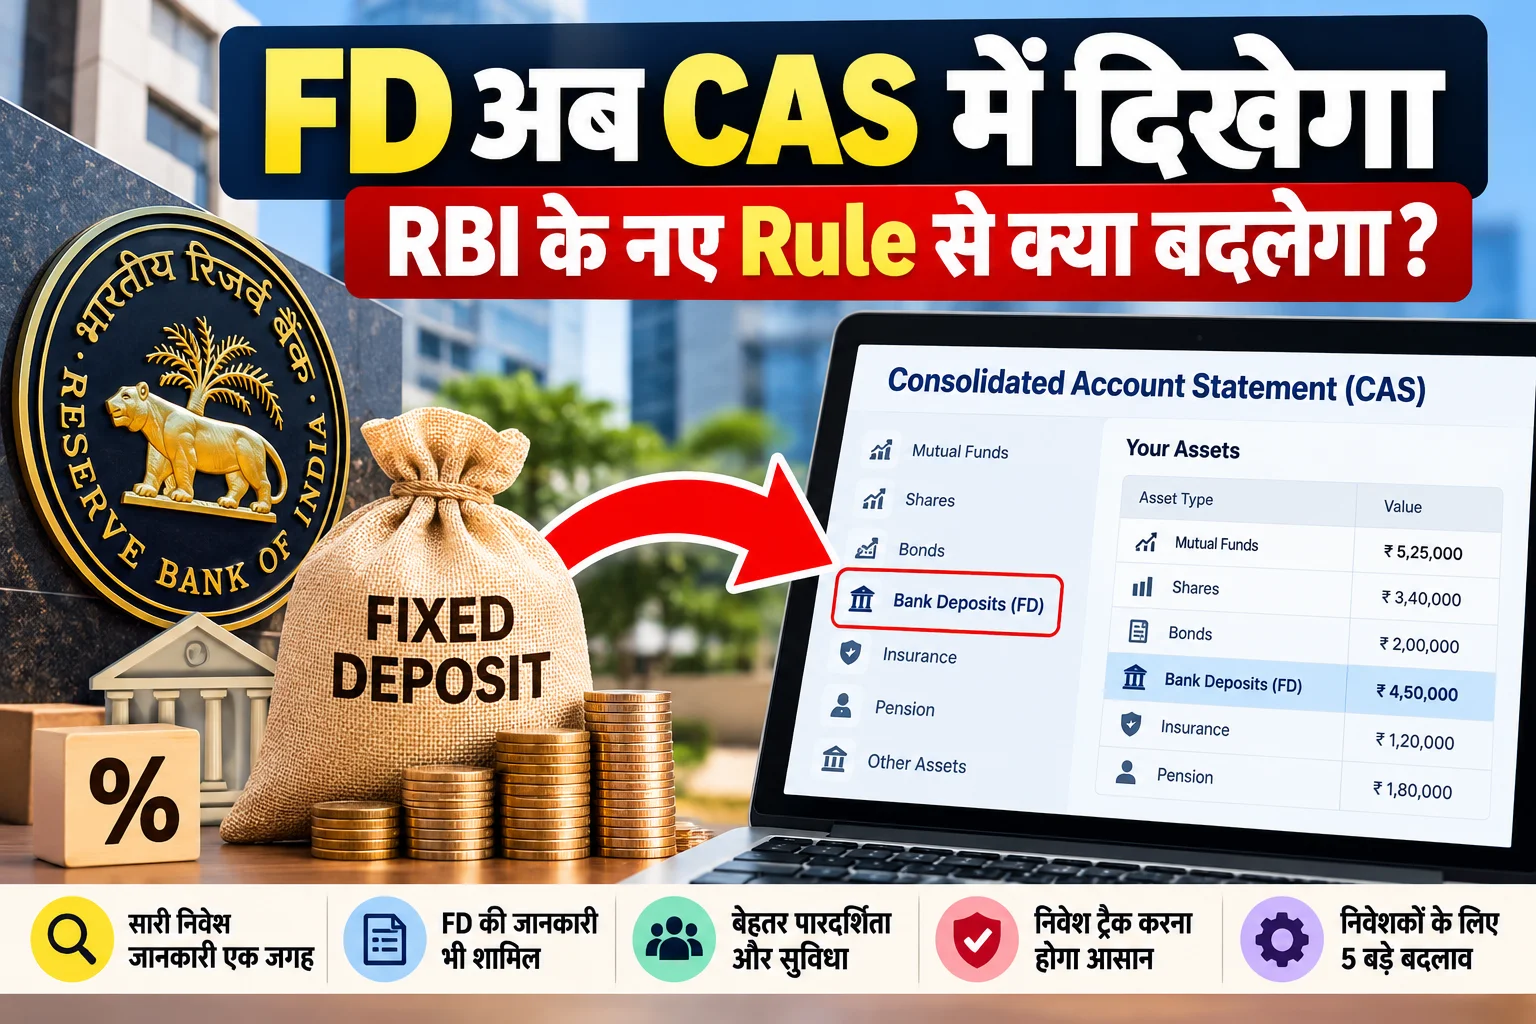
RBI ने 7 अक्टूबर 2026 को financial information को एक जगह देखना आसान बनाने के लिए एक अहम कदम की घोषणा की है। इसके तहत SEBI-regulated depositories को NBFC-Account Aggregators (NBFC-AAs) के जरिए bank deposit accounts की information को Consolidated Account Statement (CAS) में शामिल करने की सुविधा दी जाएगी। RBI के अनुसार यह व्यवस्था 31 दिसंबर 2026 तक लागू किए जाने की उम्मीद है। इसका मतलब यह है कि आने वाले समय में demat account holder को अपने securities holdings के साथ bank deposits की जानकारी भी एक consolidated statement में दिखाई दे सकती है।
सबसे जरूरी बात यह है कि इसे “FD पर नया ब्याज नियम” या “FD का नया tax rule” समझना सही नहीं होगा। RBI का focus यहां financial visibility, data sharing और customer convenience पर है।
एक नजर में:
- RBI ने 7 अक्टूबर 2026 को CAS में bank-deposit information शामिल करने की सुविधा की घोषणा की।
- यह काम SEBI-regulated depositories और NBFC-Account Aggregators के माध्यम से होगा।
- Expected implementation date: 31 दिसंबर 2026।
- Demat account holders को securities और bank deposits की जानकारी एक जगह देखने में मदद मिलेगी।
- यह announcement अपने आप FD interest rate, maturity, premature withdrawal या tax treatment नहीं बदलता।
Short Forms और Hard Words का आसान मतलब
इस article में इस्तेमाल हुए कुछ banking और investment terms पहली बार पढ़ने पर मुश्किल लग सकते हैं। यहां उनका आसान मतलब समझिए:
| Short Form / Term | पूरा नाम | आसान मतलब |
|---|---|---|
| FD | Fixed Deposit | Bank में तय अवधि के लिए जमा किया गया पैसा, जिस पर बैंक interest देता है। |
| CAS | Consolidated Account Statement | ऐसा consolidated statement जिसमें eligible investments और account-related information एक जगह दिखाई जा सकती है। |
| RBI | Reserve Bank of India | भारत का central bank, जो banking और monetary system को regulate करता है। |
| SEBI | Securities and Exchange Board of India | भारत के securities और capital market का प्रमुख regulator। |
| NBFC | Non-Banking Financial Company | ऐसी financial company जो banking जैसी कुछ financial services देती है, लेकिन commercial bank नहीं होती। |
| AA | Account Aggregator | एक regulated framework/entity जो customer की consent के आधार पर financial data को securely share करने में मदद करती है। |
| KYC | Know Your Customer | Customer की पहचान और जरूरी details verify करने की प्रक्रिया। |
| FIP | Financial Information Provider | वह regulated financial institution जो customer का financial data रखता है और applicable consent process के तहत data उपलब्ध कराता है। |
| FIU | Financial Information User | वह financial entity जो customer की consent के आधार पर financial information को किसी permitted service के लिए इस्तेमाल करती है। |
कुछ जरूरी Finance Words के आसान अर्थ
- Interoperability: अलग-अलग Account Aggregators या systems का आपस में compatible होकर information exchange कर पाना।
- Consolidated: अलग-अलग जगह की जानकारी को एक combined view में दिखाना।
- Asset Allocation: आपके पैसे को equity, debt, FD, cash जैसी अलग-अलग asset classes में किस proportion में रखा गया है।
- Liquidity: जरूरत पड़ने पर किसी investment को cash में जल्दी और आसानी से इस्तेमाल कर पाने की क्षमता।
- Consent: customer की स्पष्ट अनुमति, जिसके आधार पर financial information share की जाती है।
- Financial Information: bank deposit, investment या अन्य regulated financial account से जुड़ी relevant information।
- Implementation: किसी announced framework को practical तौर पर लागू करने की प्रक्रिया।
- Data Field: किसी record में मौजूद specific information, जैसे deposit amount, account type या date।
FD अब CAS में दिखेगा, इसका असली मतलब क्या है?
CAS यानी Consolidated Account Statement ऐसा consolidated statement है जिसमें investor के mutual fund transactions और demat account में रखी securities जैसी जानकारी एक जगह दिखाई जाती है। SEBI Investor के अनुसार CAS investor के अलग-अलग investments को consolidate करने के लिए इस्तेमाल किया जाता है।
RBI के 7 अक्टूबर 2026 के कदम के बाद bank deposit accounts की information को भी CAS framework में शामिल करने की दिशा खुली है। यानी जिस व्यक्ति के पास demat account है, वह भविष्य में एक ही consolidated statement में अपने securities holdings के साथ bank deposits की information देख सकता है, subject to the final implementation framework and data availability.
यह बदलाव खास तौर पर उन लोगों के लिए उपयोगी हो सकता है जिनके पास कई banks में savings accounts, term deposits या FDs हैं और साथ में mutual funds तथा shares भी हैं। अभी अक्सर आपको अलग-अलग bank statements, deposit receipts और investment statements को मिलाकर अपनी total financial position समझनी पड़ती है।
RBI ने 7 अक्टूबर 2026 को क्या बदला?
RBI ने “Measures to Enhance the Customer Convenience through the Account Aggregator Framework” के तहत दो connected measures की घोषणा की। पहला, NBFC-Account Aggregators के बीच interoperability लाना है। दूसरा, SEBI-regulated depositories को NBFC-AAs के जरिए bank deposit account information को CAS में शामिल करने की सुविधा देना है। RBI के अनुसार दोनों measures को 31 दिसंबर 2026 तक implement किए जाने की उम्मीद है.
इसका practical effect यह हो सकता है कि financial information अलग-अलग systems में बंद रहने के बजाय, customer consent के आधार पर ज्यादा आसानी से consolidate हो सके। Account Aggregator framework का मूल उद्देश्य ही customer की consent के साथ financial information को secure तरीके से share करना है।
CAS में FD दिखने से क्या-क्या बदलेगा?
1. Investments की पूरी तस्वीर समझना आसान होगा
मान लीजिए आपके पास एक bank में ₹5 लाख की FD है, दूसरे bank में ₹3 लाख की FD है, savings account में ₹1.5 लाख हैं और demat account में ₹6 लाख के shares तथा mutual funds हैं। अलग-अलग statements में यह जानकारी देखना संभव है, लेकिन overall picture बनाने में समय लगता है।
CAS में bank deposit information जुड़ने के बाद आपका financial snapshot ज्यादा consolidated हो सकता है। इससे asset allocation, liquidity planning और overall net-worth tracking ज्यादा आसान हो सकती है।
2. Multiple bank FDs को track करना आसान हो सकता है
कई लोग बेहतर interest rate या अलग-अलग maturity dates के कारण अलग-अलग banks में FDs रखते हैं। ऐसे में maturity date, deposit amount और bank-wise allocation को याद रखना आसान नहीं होता। Consolidated view से यह information एक जगह दिखाई देने पर portfolio monitoring आसान हो सकती है।
हालांकि implementation के final technical details यह तय करेंगे कि CAS में deposit information का exact format क्या होगा और कौन-कौन से fields दिखाए जाएंगे। इसलिए अभी यह दावा करना सही नहीं होगा कि हर FD की हर detail एक ही format में निश्चित रूप से दिखाई देगी।
3. Financial planning में clarity बढ़ सकती है
आप investment करते समय सिर्फ return नहीं देखते। आपको यह भी पता होना चाहिए कि पैसा कहां रखा है, कितना liquid है और कब mature होगा। जब bank deposits और market investments एक consolidated view में दिखाई देंगे, तब risk और liquidity balance को समझना आसान हो सकता है।
उदाहरण के लिए, अगर आपके portfolio का बहुत बड़ा हिस्सा FDs में है और equity exposure कम है, तो आपको यह नजर आ सकता है कि आपकी asset allocation कितनी conservative है। दूसरी तरफ अगर emergency जरूरत के लिए पर्याप्त liquid money नहीं है, तो वह gap भी आसानी से दिखाई दे सकता है।
4. Unclaimed deposits की पहचान में मदद मिल सकती है
इस बदलाव का एक बड़ा practical benefit family और heirs से जुड़ा हो सकता है। कभी-कभी परिवार को यह पूरी जानकारी नहीं होती कि किसी व्यक्ति ने किन banks में deposits रखे थे। अलग-अलग accounts और FDs का consolidated visibility mechanism होने से forgotten या unclaimed deposits की पहचान आसान हो सकती है।
फिर भी यह समझना जरूरी है कि CAS खुद किसी deposit को claim या transfer नहीं करता। Maturity, nominee, succession, KYC और claim settlement के लिए संबंधित bank की प्रक्रिया ही लागू होगी।
5. Financial service providers के लिए information sharing आसान हो सकती है
Account Aggregator ecosystem customer consent के आधार पर financial information को Financial Information Providers से Financial Information Users तक पहुंचाने के लिए बनाया गया है। RBI के framework के अनुसार Account Aggregator customer की financial information का मालिक नहीं बनता और information sharing consent architecture के तहत होती है।
इससे future में loan, insurance, wealth management और other financial services के लिए verified financial information share करने की प्रक्रिया बेहतर हो सकती है, जहां customer स्वयं consent देता है।
क्या इसका मतलब हर FD अपने-आप CAS में दिखेगी?
ऐसा अभी सीधे-सीधे नहीं कहा जा सकता। RBI ने bank deposit account information को CAS में शामिल करने की सुविधा देने की घोषणा की है और expected implementation date 31 दिसंबर 2026 बताई है। Final operational process, participating entities, data fields, consent flow और reporting mechanics के बारे में detailed implementation instructions की जरूरत होगी।
इसलिए अभी “1 जनवरी 2027 से हर व्यक्ति की हर FD automatically CAS में दिखेगी” जैसा absolute statement करना जल्दबाजी होगा। बेहतर और fact-checked wording यह है कि 31 दिसंबर 2026 तक framework implement किए जाने की उम्मीद है, जिसके बाद eligible and available bank-deposit information को CAS में शामिल किया जा सकेगा।
क्या FD का interest rate बदल जाएगा?
नहीं। यह RBI measure अपने आप किसी bank की FD interest rate को बढ़ाता या घटाता नहीं है। FD interest rate bank की deposit policy, tenure, customer category और prevailing market conditions के अनुसार तय होती है।
इसी तरह यह announcement FD की maturity period, premature withdrawal charges या renewal instructions को सीधे नहीं बदलता। इसलिए सिर्फ इस खबर की वजह से अपनी existing FD तोड़ने या नई FD खोलने का फैसला नहीं करना चाहिए।
क्या FD पर tax भी बदल जाएगा?
इस announcement का उद्देश्य tax rules बदलना नहीं है। FD interest पर tax treatment applicable income-tax rules के अनुसार ही रहेगा, जब तक tax authorities अलग से कोई बदलाव घोषित न करें।
इसलिए CAS में FD information दिखने का मतलब यह नहीं है कि FD पर नया tax लग गया या tax rate बदल गया। यहां मुख्य बदलाव visibility और financial data consolidation का है।
CAS और Account Aggregator में क्या अंतर है?
| Point | CAS | Account Aggregator |
|---|---|---|
| मुख्य उद्देश्य | Consolidated investment/account statement | Consent-based financial data sharing |
| मुख्य ecosystem | Depositories, mutual funds और securities ecosystem | Financial Information Providers और Financial Information Users |
| नई RBI सुविधा | Bank deposit information को include करने की दिशा | Different AAs के बीच interoperability |
| Customer consent | Implementation framework पर निर्भर | Explicit consent framework का core हिस्सा |
क्या इससे आपके सारे bank accounts एक साथ दिखाई देंगे?
यहां भी थोड़ी सावधानी जरूरी है। RBI की घोषणा bank deposit accounts की information को CAS में लाने की दिशा बताती है, लेकिन final rollout में कौन-सी information, किस bank से, किन technical standards के जरिए और किस consent mechanism के तहत उपलब्ध होगी, यह implementation rules से स्पष्ट होगा।
इसलिए इसे अभी “हर bank account का complete live dashboard” कहना सही नहीं होगा। CAS को एक consolidated statement के रूप में समझें, न कि instant banking app replacement के रूप में। आपका normal bank app, net banking और account statement अपनी जगह बने रहेंगे।
आपके लिए practical फायदे क्या हैं?
- Net worth tracking: bank deposits और investments का combined picture ज्यादा आसानी से समझ सकते हैं।
- FD maturity planning: अलग-अलग deposits को track करना आसान हो सकता है।
- Asset allocation: savings, deposits, debt और market investments का balance review करना आसान होगा।
- Family financial planning: financial holdings की visibility बढ़ने से documentation और estate planning में मदद मिल सकती है।
- Data sharing: consent-based financial services में relevant information share करना आसान हो सकता है।
लेकिन कुछ limitations भी रहेंगी
Consolidated view useful है, लेकिन यह financial planning का replacement नहीं है। CAS में information दिखने का मतलब यह नहीं कि कोई investment automatically suitable है। आपको risk, liquidity, tax, tenure और goals अलग-अलग evaluate करने होंगे।
दूसरी बात, consolidated data की accuracy source institution पर depend करेगी। RBI के Account Aggregator framework में source records की importance बनी रहती है। इसलिए अगर किसी deposit में mismatch दिखे, तो संबंधित bank के records को verify करना चाहिए।
तीसरी बात, privacy और consent का role महत्वपूर्ण रहेगा। Financial information sensitive होती है। इसलिए कोई भी request approve करने से पहले यह देखें कि कौन-सी information share की जा रही है, किस purpose के लिए और किस entity को access मिलेगा।
आपको अभी क्या करना चाहिए?
इस announcement के बाद तुरंत अपनी FD बदलने की जरूरत नहीं है। इसके बजाय अपनी current financial records को organized रखना बेहतर है। अपने bank-wise deposits, maturity dates, nominees, linked mobile/email और KYC details review करें।
अगर आपके पास multiple FDs हैं, तो एक simple personal tracker बनाना अभी भी useful है। उसमें bank name, principal amount, interest rate, tenure, maturity date और nominee status जैसी basic details रखें। CAS integration शुरू होने के बाद consolidated statement एक extra verification layer की तरह काम कर सकता है।
आप FD portfolio को समझने के लिए हमारी guide FD New Rules 2026 भी देख सकते हैं। इसी तरह bank FD risk को समझने के लिए Small Finance Bank FD vs Government Bank FD पढ़ना उपयोगी रहेगा।
FD और emergency fund के बीच सही balance क्यों जरूरी है?
अगर आपकी सारी savings long-term FDs में locked हैं, तो unexpected expense के समय liquidity problem हो सकती है। इसलिए सिर्फ consolidated visibility पर focus करने के बजाय यह देखना जरूरी है कि emergency money का एक हिस्सा आसानी से accessible रहे।
इस संदर्भ में Emergency Fund कहाँ रखें? और Emergency Fund vs FD जैसे guides आपके decision को बेहतर तरीके से structure करने में मदद कर सकते हैं।
RBI के नए CAS बदलाव का सबसे बड़ा असर क्या है?
इस पूरे announcement को एक line में समझें तो RBI financial information को ज्यादा connected बनाने की दिशा में कदम उठा रहा है। आज आपके shares, mutual funds और bank deposits अलग-अलग platforms पर दिखते हैं। नए framework के बाद इन pieces को एक अधिक consolidated view में देखने की सुविधा मिल सकती है।
सबसे महत्वपूर्ण बदलाव convenience और visibility का है, न कि FD product के core terms का। यानी आपकी FD वही FD रहेगी, लेकिन उसे आपके broader financial picture में देखना ज्यादा आसान हो सकता है।
Bottom Line
RBI का 7 अक्टूबर 2026 का फैसला FD interest rate या FD tax rule बदलने वाला आदेश नहीं है। यह bank deposit information को SEBI-regulated depositories द्वारा CAS में शामिल करने की दिशा में एक बड़ा customer-convenience measure है। RBI ने दोनों related measures, यानी NBFC-Account Aggregator interoperability और CAS में bank-deposit information inclusion, को 31 दिसंबर 2026 तक implement किए जाने की उम्मीद बताई है।
Demat investors के लिए इसका सबसे बड़ा फायदा यह होगा कि securities और bank deposits को एक consolidated financial view में देखना आसान हो सकता है। लेकिन final rollout details आने तक “हर FD automatically एक ही CAS में दिखेगी” जैसा दावा नहीं करना चाहिए।
अपने personal finance decisions में सिर्फ किसी नए rule की headline देखकर action लेने के बजाय, liquidity, risk, tax, maturity और financial goals को साथ में देखें। यही approach किसी भी FD या investment decision को ज्यादा practical बनाती है।
और पढ़ें
- RBI Repo Rate 5.50%: Loan EMI, FD और Personal Loan पर असर
- FD New Rules 2026: 1 October से 7 बड़े बदलाव
- Small Finance Bank FD vs Government Bank FD
- Emergency Fund कहाँ रखें?
- Emergency Fund vs FD
आधिकारिक जानकारी के लिए
- Reserve Bank of India (RBI)
- SEBI Investor: Consolidated Account Statement (CAS)
- RBI: Master Direction on NBFC-Account Aggregator
लेखक: Dinesh Rewale
Dinesh Rewale personal finance, banking, investment और financial awareness topics पर reader-friendly Hindi content लिखते हैं। उनका focus practical explanations, fact-checking और everyday money decisions को आसान भाषा में समझाने पर है।
Dinesh Rewale on Facebook
Financial Disclaimer: यह लेख सामान्य financial awareness और educational purpose के लिए है। इसमें दी गई जानकारी को व्यक्तिगत investment, tax या financial advice न समझें। किसी FD, investment या financial product का निर्णय लेने से पहले संबंधित bank, regulator की latest information और जरूरत पड़ने पर SEBI-registered या अन्य योग्य professional से सलाह लें। RBI/SEBI framework में future updates होने पर implementation details बदल सकती हैं।