Section 54F Exemption: Capital Gain Tax कैसे बचाएं? (2026)
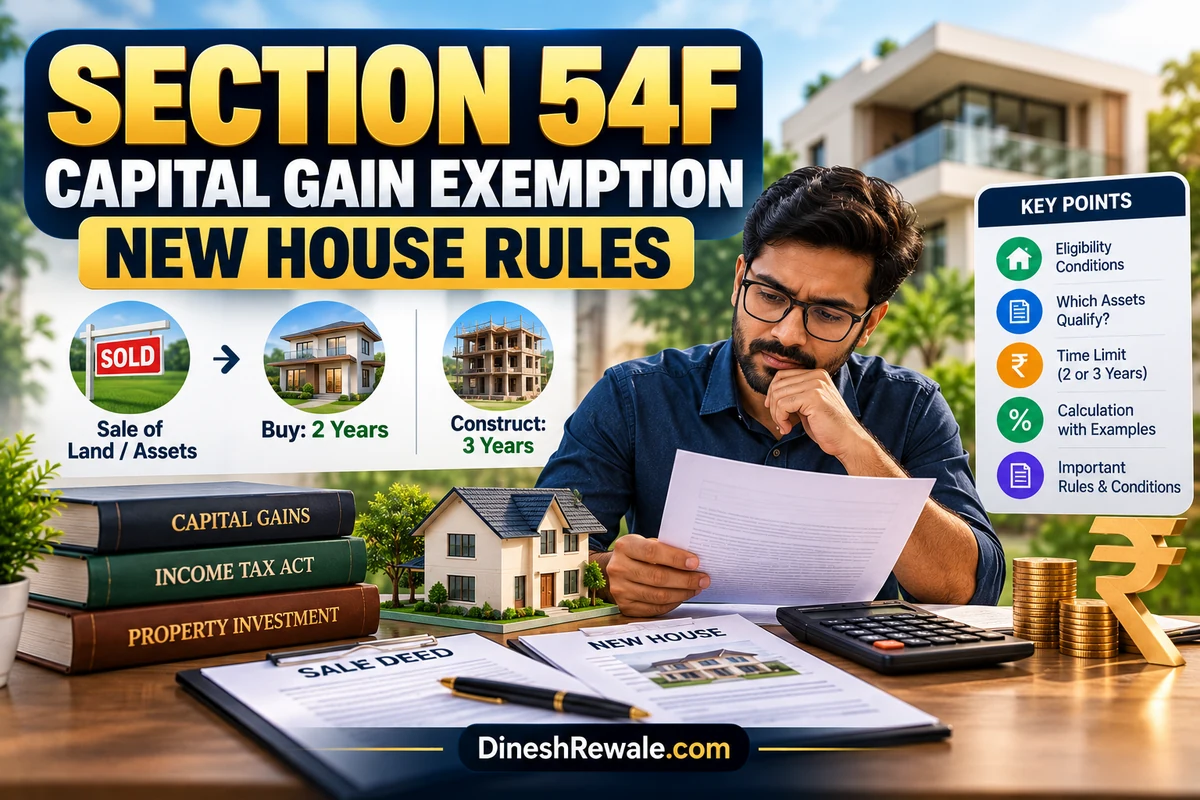
सीधा जवाब: Section 54F के तहत किसी eligible long-term capital asset (residential house को छोड़कर) को बेचने पर हुआ capital gain, भारत में एक residential house खरीदने या बनाने में net sale consideration reinvest करने पर पूरी तरह या proportionately exempt हो सकता है। सामान्य timeline है—घर खरीदने के लिए sale से 1 साल पहले या sale के 2 साल के भीतर, और निर्माण के लिए sale के 3 साल के भीतर। लेकिन exemption तभी मिलेगी जब ownership, investment, Capital Gains Account Scheme और बाकी शर्तें पूरी हों।
2026 का जरूरी legal update: Income-tax Act, 2025, 1 अप्रैल 2026 से लागू है। Tax Year 2026-27 में पुराने Section 54F का corresponding provision Section 86 है। इसलिए 31 मार्च 2026 तक हुए transfers के लिए सामान्यतः Income-tax Act, 1961 का Section 54F और 1 अप्रैल 2026 से हुए transfers के लिए Income-tax Act, 2025 का Section 86 देखें। Specific case में applicable savings और transitional provisions भी verify करें। Official text: Income-tax Act, 2025 — Section 86.
Section 54F Capital Gain Exemption क्या है?
Section 54F, Income-tax Act, 1961 का वह provision है जिसके तहत Individual या Hindu Undivided Family (HUF) को residential house के अलावा किसी अन्य long-term capital asset की sale पर होने वाले capital gain पर residential house में investment करने से exemption मिल सकती है। नए कानून के Section 86 में यही core principle जारी है। यह tax planning provision है—automatic tax waiver नहीं।
उदाहरण के तौर पर long-term land/plot, gold या किसी दूसरी eligible long-term asset को बेचकर residential house में पैसा लगाना इस section के दायरे में आ सकता है। Original asset खुद residential house है, तो आम तौर पर Section 54/नए Act का corresponding residential-house provision देखना होगा, न कि 54F को सीधे लागू मान लेना चाहिए। Asset का holding period और capital-gain classification current law के अनुसार verify करें।
Section 54F की eligibility: कौन claim कर सकता है?
- Eligible taxpayer: Individual या HUF. Company, firm या हर प्रकार की entity इस exemption को स्वतः claim नहीं कर सकती।
- Original asset: बेची गई asset long-term capital asset होनी चाहिए और वह residential house नहीं होनी चाहिए।
- New asset: भारत में एक residential house purchase या construct करना जरूरी है।
- Investment amount: Full exemption के लिए सामान्यतः original asset की पूरी net consideration new house में लगानी होती है। अगर केवल कुछ राशि invest की है, exemption proportionate हो सकती है।
- House ownership restriction: Sale के समय पहले से कितने residential houses हैं, और exemption window में कोई अतिरिक्त house खरीदा/बनाया जाता है या नहीं, यह eligibility पर असर डाल सकता है।
- ₹10 करोड़ की cap: Current provision में qualifying new-house cost की गणना के लिए ₹10 करोड़ से अधिक रकम को exemption calculation में नहीं गिना जाता। Section 86 में CGAS से जुड़े net consideration पर भी cap का provision है।
Eligibility और restriction की full statutory language के लिए Income Tax Department की Section 54F text और current Section 86 दोनों देखें। Sale/transfer की तारीख तय करती है कि किस Act और किस transitional rule को लागू करना है।
House खरीदने या बनाने की time limit क्या है?
| Investment option | Timeline | ध्यान रखने वाली बात |
|---|---|---|
| पहले से घर खरीदना | Asset transfer से 1 साल पहले तक | Purchase date और ownership documents check करें। |
| Sale के बाद घर खरीदना | Transfer date के 2 साल के भीतर | Agreement, payment proof और registration record रखें। |
| नया घर construct करना | Transfer date के 3 साल के भीतर | Construction का वास्तविक progress और bills document करें। |
| Capital Gains Account Scheme | Return filing की applicable due date तक | Unutilised eligible amount prescribed CGAS में deposit करके proof attach करें। |
अगर due date तक purchase/construction में पैसा इस्तेमाल नहीं हुआ है, तो केवल savings account में रकम रख लेना काफी नहीं है। Prescribed Capital Gains Account Scheme (CGAS) में applicable deadline तक deposit करना पड़ सकता है। बाद में निर्धारित 2 या 3 साल की अवधि में यह पैसा eligible residential house खरीदने/बनाने के लिए इस्तेमाल करना होगा। Official guidance: Income Tax Department — investment time limit.
Section 54F exemption की calculation कैसे होती है?
जब new house में investment, net consideration से कम हो, तो सामान्य formula यह है:
Exemption = Long-term Capital Gain × (Eligible investment in new house / Net consideration)
Eligible investment में नियमों के अनुसार new house की qualifying cost और prescribed CGAS में जमा रकम शामिल हो सकती है, ₹10 करोड़ की applicable cap के अधीन। Net consideration का मतलब sale consideration में से asset transfer के संबंध में पूरी तरह और exclusively incurred eligible expenses घटाने के बाद बची रकम है। यदि net consideration पूरी तरह eligible house में invest कर दी जाए, तो अन्य conditions और statutory caps के अधीन पूरा capital gain exempt हो सकता है।
Example: ₹1.18 करोड़ में से ₹70 लाख घर पर invest किए
मान लेते हैं कि एक taxpayer ने eligible long-term plot/land बेचा और figures इस तरह हैं:
| Calculation detail | Amount |
|---|---|
| Sale consideration | ₹1,20,00,000 |
| Eligible transfer expenses | ₹2,00,000 |
| Net consideration | ₹1,18,00,000 |
| Long-term capital gain (assumed, after eligible cost calculation) | ₹50,00,000 |
| Qualifying new-house investment | ₹70,00,000 |
| Approximate exemption | ₹29,66,102 |
| Capital gain remaining taxable before other adjustments | ₹20,33,898 |
Calculation: ₹50,00,000 × ₹70,00,000 ÷ ₹1,18,00,000 ≈ ₹29,66,102. यह illustrative calculation है। Actual capital gain, asset type, acquisition cost, improvements, transfer expenses, tax rate और transitional law के आधार पर amount अलग होगा। इसे personal tax computation नहीं समझें।
अगर घर खरीदने तक पूरा पैसा इस्तेमाल नहीं हुआ तो क्या करें?
यदि return filing की applicable due date तक net consideration का पूरा required amount purchase/construction में इस्तेमाल नहीं हो सका, तो Section 54F/Section 86 के लागू नियमों के अनुसार बची रकम prescribed Capital Gains Account Scheme में जमा की जा सकती है। इस deposit का proof return के साथ रखना जरूरी है।
- पहले applicable tax return की due date और transfer date तय करें।
- CGAS deposit bank और account type की official instructions follow करें; ordinary FD/savings account को CGAS का substitute न मानें।
- CGAS में जमा पैसा निर्धारित समय के भीतर eligible house purchase/construction पर उपयोग करें।
- अगर 2/3 साल के prescribed period में पैसा पूरी तरह इस्तेमाल नहीं होता, तो unutilised amount पर capital-gains tax लग सकता है।
2026-27 tax year के transaction पर current Act के तहत return-filing section और applicable forms check करना जरूरी है; पुराने Assessment Year के form या due date को automatically लागू न मानें।
Section 54F में house ownership की कौन-सी restrictions हैं?
यह exemption सिर्फ sale proceeds को घर में लगाने भर से तय नहीं होती। Existing house ownership और बाद में acquired house भी मायने रखता है:
- Original asset transfer की तारीख पर नए house के अलावा एक से अधिक residential house own होने पर exemption disqualify हो सकती है।
- Transfer के बाद statutory window में दूसरा residential house purchase या construct करने से exemption denied या पहले granted exemption वापस taxable होने का जोखिम पैदा हो सकता है। नियमों में specific conditions हैं—सिर्फ headline देखकर निष्कर्ष न निकालें।
- Qualifying new house को purchase/construction date से 3 साल के भीतर transfer करना exemption clawback/tax consequences trigger कर सकता है।
- Ownership co-owners में हो तो investment, sale proceeds और title ownership की legal documentation तथा taxpayer की actual contribution खास तौर पर review करें।
इन restrictions का असर high-value property और multiple-house cases में बड़ा हो सकता है। किसी house की ownership, inherited share या joint ownership को लेकर ambiguity हो तो return file करने से पहले tax professional से लिखित opinion लें।
Section 54F claim करते समय ये गलतियाँ न करें
- Residential house बेचने पर 54F claim करना: Section 54F का original asset residential house नहीं होना चाहिए। Residential house sale पर Section 54/नए कानून का corresponding provision evaluate करें।
- Purchase/construction deadline चूकना: 1 साल पहले/2 साल बाद purchase और 3 साल में construction की statutory timelines calendar करें।
- पूरा consideration invest किए बिना full exemption मान लेना: Partial investment में exemption proportionate होती है, subject to rules and limits।
- CGAS deadline भूल जाना: Return की applicable due date तक unutilised amount prescribed CGAS में deposit करने की जरूरत पड़ सकती है।
- ₹10 करोड़ cap ignore करना: बड़ी transactions में excess investment को exemption calculation में नहीं गिना जा सकता।
- नया house जल्दी बेच देना: 3 साल की holding restriction और tax consequences समझे बिना sale न करें।
- पुराना section number ही लागू मानना: 1 April 2026 से नए Act का Section 86 relevant है; transaction date के हिसाब से सही law apply करें।
Section 54 और Section 54F में क्या अंतर है?
| Comparison | Section 54 / corresponding provision | Section 54F / new Section 86 |
|---|---|---|
| Original asset sold | Long-term residential house | Other eligible long-term asset, not a residential house |
| New investment | Residential house | Residential house in India |
| Full exemption condition | Exemption generally measured against eligible capital gain reinvestment | Full net consideration reinvestment generally needed for full capital-gain exemption |
| New-law reference from 2026-27 | Check Income-tax Act, 2025 equivalent section | Section 86 |
Property transaction की प्रकृति समझने के लिए DineshRewale.com के Gift Deed vs Will, Property खरीदते समय price negotiation, Circle Rate vs Market Value, Home Loan Balance Transfer और HUF Account और tax planning की guides भी पढ़ें।
FAQs: Section 54F Capital Gain Exemption
क्या Section 54F में पूरा capital gain tax-free हो सकता है?
हाँ, eligible conditions पूरी होने पर और net consideration की required amount qualifying residential house में invest होने पर पूरा capital gain exempt हो सकता है। ₹10 करोड़ की applicable cap और other restrictions लागू रहती हैं।
क्या Section 54F का लाभ shares या gold बेचने पर मिल सकता है?
Potentially, अगर बेची गई asset qualifying long-term capital asset है और residential house नहीं है। लेकिन asset-specific holding period, tax classification और transaction facts verify करना जरूरी है।
क्या Section 54F में सिर्फ capital gain की राशि invest करनी होती है?
Full exemption के लिए generally net consideration—sale value minus eligible transfer expenses—पूरी तरह invest करनी होती है। Net consideration से कम investment होने पर formula के अनुसार proportionate exemption मिल सकती है।
क्या CGAS में पैसा जमा करना जरूरी है?
यदि applicable return-filing due date तक eligible amount खरीद या construction में इस्तेमाल नहीं हुआ है, तो exemption claim preserve करने के लिए prescribed Capital Gains Account Scheme में deposit जरूरी हो सकता है। Ordinary savings account को CGAS न समझें।
2026 में Section 54F लागू है या नया Section 86?
Income-tax Act, 2025, 1 अप्रैल 2026 से लागू है। Tax Year 2026-27 के transfers के लिए corresponding provision Section 86 है। इससे पहले के transfer के लिए उस transaction पर लागू law और transitional rules check करें।
निष्कर्ष
Section 54F/वर्तमान law का Section 86 capital gain पर tax घटाने का उपयोगी विकल्प हो सकता है, लेकिन यह तभी काम करता है जब taxpayer eligible हो, original asset सही category का हो, residential house में investment सही समय पर हो और ownership restrictions का पालन किया जाए। सबसे पहले sale consideration, transfer expenses और actual long-term capital gain calculate करें; फिर purchase/construction timeline और CGAS की due date plan करें। High-value transaction में return file करने से पहले qualified Chartered Accountant से calculation और applicable law verify कराएँ।
संबंधित गाइड: Ancestral Property Transfer Process · Circle Rate और Market Value का अंतर · Gift Deed vs Will · Home Loan Prepayment Calculation · Home Inspection Checklist
2026 tax-year update: Income-tax Act, 2025, 1 April 2026 से लागू है. Tax Year 2026-27 में old Section 54F के corresponding residential-reinvestment rule को नए Act की Section 86 में देखें. Inherited property sale, cost basis और holding-period calculation के लिए Inherited Property Sale Capital Gains Tax Calculator 2026 भी पढ़ें.
लेखक: Dinesh Rewale
Dinesh Rewale personal finance, tax planning, property transactions और money management पर reader-focused guides लिखते हैं। नए updates के लिए Facebook पर जुड़ें।
Disclaimer: यह लेख सामान्य जानकारी और educational purpose के लिए है, व्यक्तिगत tax या legal advice नहीं। Income-tax Act, 2025 और transitional provisions, asset classification, investment dates और taxpayer के facts के अनुसार exemption बदल सकती है। कोई transaction या return filing करने से पहले official statute देखें और जरूरत पर qualified Chartered Accountant से सलाह लें।