Second Home Loan Tax Benefits: 7 जरूरी बातें
अगर आपके पास पहले से एक घर है और आप दूसरा घर Home Loan लेकर खरीदने की planning कर रहे हैं, तो सिर्फ EMI और property price देखना काफी नहीं है। Second Home Loan Tax Benefits का actual फायदा इस बात पर निर्भर करता है कि दूसरा घर self-occupied है या let-out, आपने old tax regime चुना है या new tax regime, और loan का interest तथा principal कितना है।
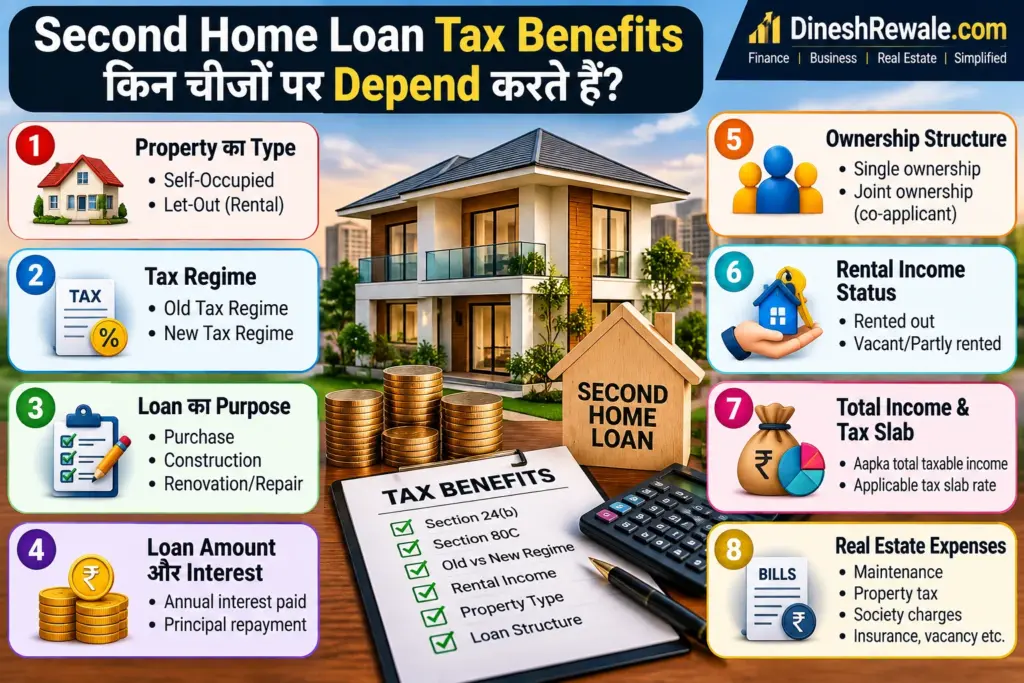
Second Home Loan Tax Benefits किन चीजों पर depend करते हैं?
सबसे पहले यह समझना जरूरी है कि Income Tax में “second home” नाम से कोई अलग fixed deduction नहीं है। Property की tax classification और आपका tax regime मिलकर benefit तय करते हैं।
1. Second home self-occupied है तो क्या tax benefit मिलेगा?
AY 2026-27 से Income Tax Department ने दो houses को self-occupied मानने के लिए पहले लागू specified conditions को हटा दिया है। इसलिए पुराने नियम के आधार पर दूसरे घर को automatically deemed let-out मानना सही नहीं है।
अगर दोनों properties self-occupied हैं और आप old tax regime में हैं, तो Section 24(b) के तहत eligible housing-loan interest का aggregate deduction सामान्यतः ₹2 लाख तक हो सकता है। यह दोनों properties पर अलग-अलग ₹2 लाख नहीं है।
इसलिए अगर पहले घर पर eligible interest ₹1.40 लाख और दूसरे घर पर ₹1.10 लाख है, तो केवल ₹2 लाख की aggregate limit तक deduction उपलब्ध हो सकता है, subject to applicable conditions.
2. New Tax Regime में second home का क्या होगा?
यह सबसे important distinction है। Income Tax Department के current FAQ के अनुसार new tax regime में self-occupied house property के borrowed-capital interest की Section 24(b) deduction नहीं मिलती। अगर आप self-occupied second home पर interest deduction चाहते हैं, तो applicable conditions के अनुसार old regime का option देखना पड़ सकता है।
लेकिन let-out property का treatment अलग है। New regime में eligible let-out property के लिए Section 24(b) के तहत actual interest deduction उपलब्ध हो सकता है। हालांकि house-property loss को दूसरे heads of income के against set-off नहीं किया जा सकता और उसे आगे carry forward भी नहीं किया जा सकता।
3. Second home rent पर दिया है तो tax benefit कैसे काम करता है?
अगर दूसरा घर किराए पर दिया गया है, तो property से rental income taxable computation में आती है। सामान्य house-property computation में municipal taxes, applicable standard deduction और eligible home-loan interest जैसे components देखे जाते हैं। Let-out property के लिए standard deduction सामान्यतः Net Annual Value का 30% होती है।
Income from House Property = Net Annual Value − 30% Standard Deduction − Eligible Interest on Borrowed Capital
Example: मान लीजिए दूसरे घर से सालाना rent ₹3,60,000 मिलता है। अगर eligible deductions और interest को illustration के लिए ₹1,08,000 standard deduction तथा ₹4,20,000 interest माना जाए, तो house-property result लगभग ₹1,68,000 loss हो सकता है। Actual tax calculation में municipal taxes, vacancy, ownership share और अन्य applicable details भी देखनी होंगी।
4. Old Regime में ₹2 लाख वाला rule कैसे समझें?
Old tax regime में let-out house property के लिए eligible home-loan interest की deduction पर कोई ₹2 लाख की property-level cap नहीं है। लेकिन अगर house-property computation से loss बनता है, तो उसे salary या अन्य heads के against set-off करने की सीमा सामान्यतः ₹2 लाख प्रति assessment year है। Unabsorbed loss applicable rules के अनुसार आगे carry forward किया जा सकता है।
इसका मतलब यह नहीं है कि ₹5 लाख interest होने पर ₹5 लाख सीधे आपकी salary income से घट जाएगा। पहले house-property computation होगा, फिर set-off rules लागू होंगे।
5. Section 80C में second home loan का principal मिलेगा?
Eligible housing-loan principal repayment Section 80C में शामिल हो सकता है, लेकिन यह benefit old tax regime में Chapter VI-A deductions के framework के तहत आता है। Section 80C की combined limit ₹1.50 लाख है और इसमें कई दूसरे eligible investments/payments भी शामिल होते हैं।
इसलिए अगर आपके EPF, insurance, tuition fee या दूसरे eligible 80C items से ₹1.50 लाख की limit पहले ही भर जाती है, तो second home loan principal के लिए अलग से अतिरिक्त ₹1.50 लाख deduction नहीं मिलेगा।
Property transfer और eligibility conditions को भी ध्यान में रखें। सिर्फ EMI में principal component होने से बिना conditions check किए 80C claim करना सही approach नहीं है।
6. Second home को investment property बनाने से पहले यह calculation करें
Tax saving को investment return समझना एक common mistake है। Second home की economics में rent, vacancy, maintenance, property tax, society charges, insurance, loan interest, stamp duty और resale prospects सभी को साथ देखना चाहिए।
7. Joint Home Loan में tax benefit कैसे देखें?
अगर second property joint ownership और joint loan में है, तो tax benefit ownership share, actual repayment contribution और applicable tax rules से जुड़ सकता है। केवल loan में co-applicant होना पर्याप्त आधार मानकर deduction claim करना उचित नहीं है।
इसलिए agreement, ownership percentage, loan account details और दोनों borrowers के repayment records सुरक्षित रखें। Tax return file करते समय अपने share और actual eligibility को verify करना जरूरी है।
Second Home Loan लेने से पहले 8-point checklist
- Property use तय करें: Self-occupied, family use या rental?
- Tax regime compare करें: Old और new regime दोनों में total tax देखें।
- Interest certificate रखें: Bank से annual interest statement लें।
- Principal repayment अलग track करें: 80C eligibility और ₹1.50 लाख combined limit check करें।
- Rent realistic रखें: Gross rent को investment return न मानें।
- Vacancy buffer रखें: हर महीने rent आएगा, यह assumption न बनाएं।
- Property documents verify करें: RERA, title, approvals और agreement independently check करें।
- Cash-flow stress test करें: Interest rate बढ़ने या rent कम होने पर EMI comfortably संभलेगी या नहीं देखें।
Second Home और First Home के tax benefits में क्या फर्क है?
Tax rules property की “first” या “second” label से ज्यादा उसके treatment पर depend करते हैं। दो self-occupied houses के लिए old regime में Section 24(b) interest deduction का aggregate ₹2 लाख तक का framework लागू हो सकता है। वहीं rental property में actual interest और house-property income/loss computation का अलग treatment है।
इसलिए “मेरे पास पहले से एक घर है, इसलिए दूसरे घर का tax benefit नहीं मिलेगा” और “दूसरे घर का पूरा interest salary से घट जाएगा” दोनों statements oversimplified हैं।
Second Home Loan Tax Benefits का practical example
मान लीजिए आपने ₹60 लाख का second home loan लिया। पहले साल का eligible interest ₹5 लाख है और property ₹25,000 monthly rent पर दी गई है, यानी annual rent ₹3 लाख। Illustration के लिए 30% standard deduction ₹90,000 मानें। House-property computation में ₹3 लाख − ₹90,000 − ₹5 लाख = ₹2.90 लाख loss बनता है, अन्य applicable adjustments से पहले।
Old regime में applicable rules के अनुसार इस loss में से ₹2 लाख तक अन्य heads के against set-off हो सकता है और balance eligible loss आगे carry forward हो सकता है। New regime में ऐसे house-property loss को दूसरे heads से set-off या carry forward नहीं किया जा सकता। इसलिए सिर्फ “interest deduction unlimited है” सुनकर tax saving calculate करना अधूरा है।
किन गलतियों से बचें?
- Tax benefit को property investment का main reason बनाना।
- Old regime और new regime का total tax compare किए बिना decision लेना।
- Self-occupied और let-out treatment को एक जैसा मानना।
- ₹2 लाख loss set-off limit को ₹2 लाख interest deduction limit समझ लेना।
- Section 80C की ₹1.50 लाख combined limit को second home के लिए अलग limit समझना।
- Joint ownership में पूरे interest/principal पर अपना 100% deduction मान लेना।
- Bank statement और interest certificate के बिना अनुमान से claim करना।
Related Guides
- Home Loan लेने से पहले 15 जरूरी बातें
- Home Loan जल्दी खत्म करने के 7 Smart तरीके
- Home Loan EMI Salary का कितना % होना चाहिए?
- Flat की सही Price कैसे Calculate करें?
- RERA Registered Project कैसे Check करें?
FAQs: Second Home Loan Tax Benefits
क्या second home loan पर ₹2 लाख का interest deduction मिलेगा?
Self-occupied properties के लिए old tax regime में eligible interest का aggregate deduction सामान्यतः ₹2 लाख तक हो सकता है। Let-out property के लिए Section 24(b) का treatment अलग है।
क्या new tax regime में second home loan का interest claim कर सकते हैं?
Self-occupied house property के interest पर Section 24(b) deduction नहीं मिलता। Eligible let-out property के interest का treatment अलग है, लेकिन house-property loss को दूसरे heads से set-off या carry forward नहीं किया जा सकता।
क्या second home loan का principal 80C में claim कर सकते हैं?
Eligible principal repayment Section 80C के framework में आ सकता है, लेकिन old regime में Chapter VI-A की combined ₹1.50 लाख limit और अन्य conditions लागू होती हैं।
क्या दो houses को self-occupied माना जा सकता है?
AY 2026-27 से दो houses को self-occupied मानने के लिए पहले लागू specified conditions हटा दी गई हैं। अपने facts और current ITR rules के अनुसार tax treatment verify करें।
क्या second home खरीदने से tax saving guaranteed है?
नहीं। Tax saving property usage, loan interest, ownership, tax regime और house-property computation पर निर्भर करती है। Investment decision केवल tax benefit देखकर नहीं लेना चाहिए।
आपके लिए क्या मायने रखता है?
Second home loan का tax benefit समझने का सही तरीका है कि पहले property का use तय करें, फिर old और new tax regime में अलग-अलग house-property calculation बनाएं। Self-occupied property में old regime का Section 24(b) framework और let-out property में rent, 30% standard deduction तथा eligible interest को साथ रखकर calculation करें।
सबसे जरूरी बात यह है कि tax saving को return का substitute न मानें। Second property तभी practical हो सकती है जब EMI, rental income, vacancy risk, maintenance और long-term property goal आपके overall cash flow के साथ comfortably fit हों।
और पढ़ें
लेखक: Dinesh RewaleDinesh Rewale DineshRewale.com के संस्थापक और content creator हैं। वे personal finance, business और real estate से जुड़े practical topics को आसान हिंदी और useful examples के साथ समझाने पर ध्यान देते हैं।
Disclaimer: यह लेख सामान्य educational और financial-information purpose के लिए है। Tax laws, rules, limits और tax-regime provisions समय-समय पर बदल सकते हैं। किसी specific property purchase, loan structure या income-tax return से पहले current Income Tax Department provisions और अपने CA/tax professional से independent verification जरूर करें।