PRIM vs PMS vs Mutual Fund: 10 बड़े Differences
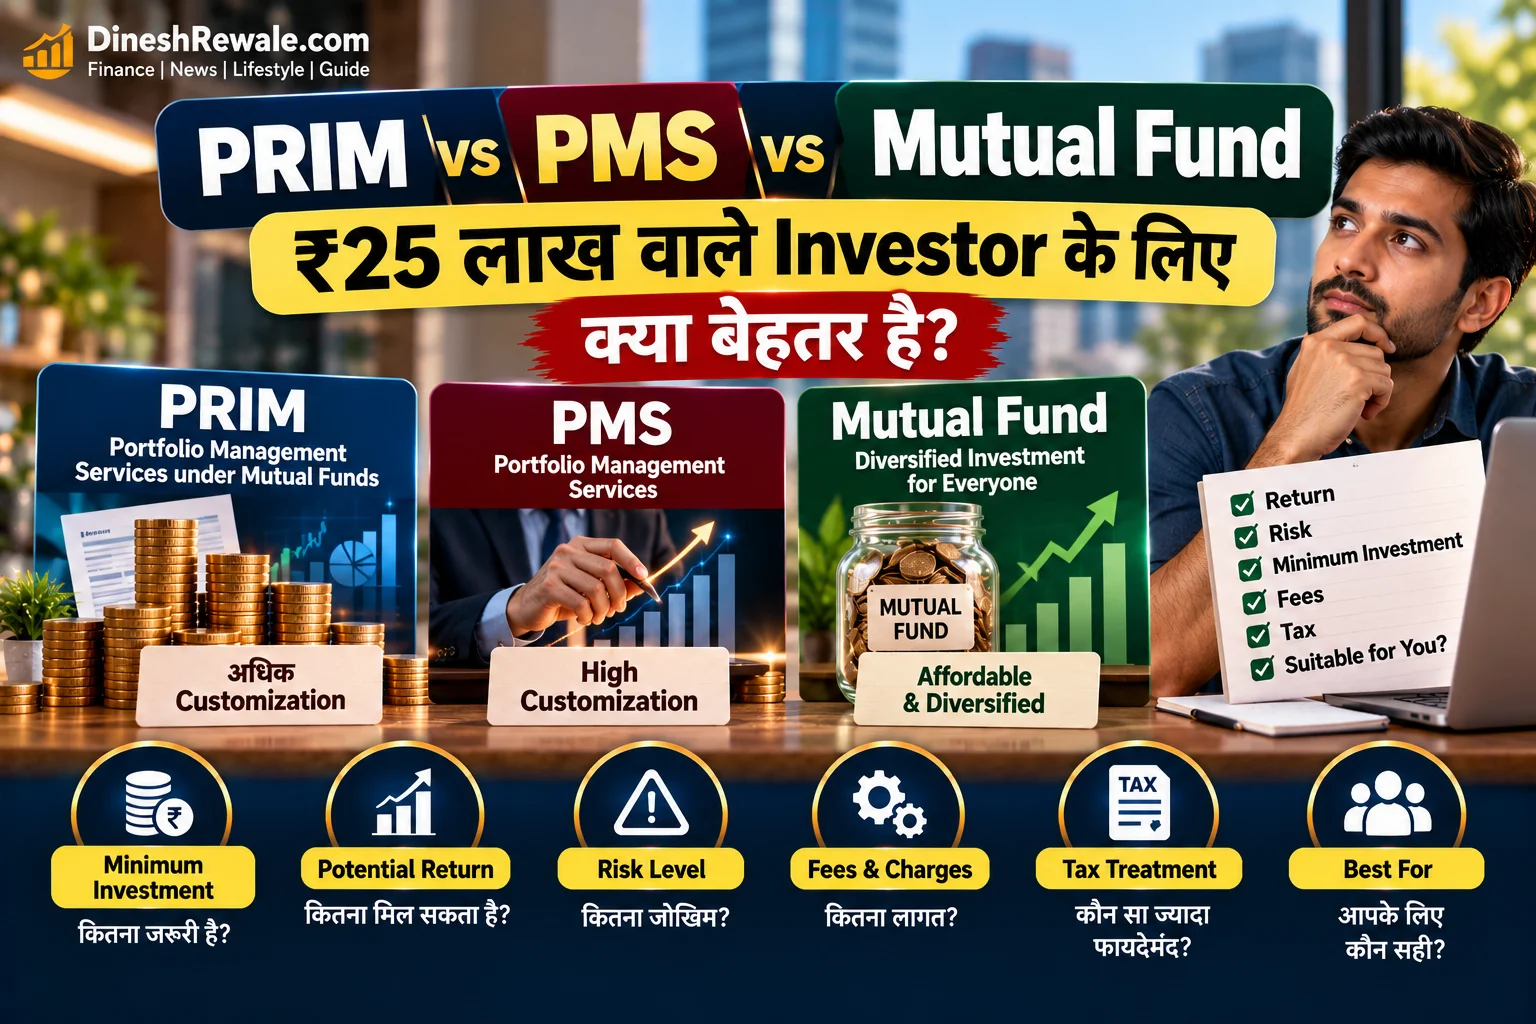
PRIM vs PMS vs Mutual Fund में कौन सा option बेहतर है, इसका जवाब आपके investment amount से ज्यादा आपकी जरूरत पर depend करता है। सितंबर 2026 में SEBI ने PRIM यानी Portfolio Managers Route for Investing in Mutual Fund Units को approve किया है। PRIM में portfolio manager eligible direct mutual fund products के जरिए portfolio manage कर सकता है और minimum investment ₹25 लाख है, जबकि conventional PMS का minimum investment ₹50 लाख है।
इसलिए ₹25 लाख वाले investor के लिए PRIM एक नया middle-ground option बनता है। लेकिन PRIM को “better Mutual Fund” या “cheaper PMS” समझना सही नहीं है। इसमें professional portfolio management मिलता है, लेकिन fee, taxation, risk और underlying fund costs को समझना उतना ही जरूरी है।
In Short
- Mutual Fund: pooled investment vehicle, जिसमें investor scheme units खरीदता है।
- PRIM: portfolio manager eligible direct mutual funds, ETFs, index funds और SIFs के जरिए customised portfolio manage करता है।
- PMS: portfolio manager client-specific portfolio manage करता है और eligible securities में direct portfolio construction की अधिक flexibility हो सकती है।
- Minimum investment: Mutual Fund में scheme-wise amount बहुत कम हो सकता है, PRIM में ₹25 लाख और conventional PMS में ₹50 लाख minimum है।
- PRIM में professional allocation और rebalancing मिलता है, लेकिन underlying mutual fund costs के अलावा management fee भी हो सकती है।
- PRIM, PMS और Mutual Fund तीनों में market risk रहता है। कोई भी route guaranteed return नहीं देता।
PRIM क्या है?
PRIM का पूरा नाम Portfolio Managers Route for Investing in Mutual Fund Units है। यह 2026 में SEBI के नए portfolio-management framework के तहत आया route है। इसका उद्देश्य उन investors को professional portfolio construction की सुविधा देना है जो mutual funds में खुद investment कर सकते हैं, लेकिन fund selection, asset allocation और rebalancing किसी professional manager से करवाना चाहते हैं।
PRIM portfolio manager को eligible direct mutual fund plans, ETFs, index funds और Specialised Investment Funds (SIFs) के माध्यम से client portfolio बनाने की अनुमति देता है। इसका minimum investment ₹25 लाख है।
Simple language में समझें तो PRIM में आपको individual stocks चुनने वाला traditional PMS जरूरी नहीं मिलता। यहां manager अलग-अलग fund products को चुनकर overall portfolio बनाता और manage करता है।
PMS क्या है?
Portfolio Management Services (PMS) में portfolio manager client की जरूरत और agreed mandate के अनुसार securities manage करता है। Conventional PMS का minimum investment ₹50 लाख है।
PMS का बड़ा difference यह है कि portfolio relatively more personalised हो सकता है और manager permitted securities की broader range में direct portfolio construction कर सकता है। 2026 framework में PMS universe को पहले की तुलना में broader बनाया गया है, जिसमें specified listed securities, debt, IPOs और certain foreign exposure जैसी possibilities applicable rules के अधीन शामिल हैं।
PMS में investor को यह समझना चाहिए कि higher customisation के साथ concentration risk, portfolio turnover और cost complexity भी बढ़ सकती है। SEBI framework के तहत portfolio manager return guarantee नहीं कर सकता और fees agreement के अनुसार disclosed होती हैं।
Mutual Fund क्या है?
Mutual Fund एक pooled investment vehicle है। कई investors का पैसा एक scheme में जमा होता है और fund manager उस scheme के stated mandate के अनुसार securities में investment करता है।
Investor scheme चुनता है, amount तय करता है और SIP या lump sum के जरिए invest कर सकता है। इसलिए decision-making की जिम्मेदारी investor के पास अधिक रहती है, जबकि individual securities का selection fund manager करता है।
Mutual Funds की सबसे बड़ी practical strengths में comparatively low entry amount, diversification और simple account-based access शामिल हैं। हर investor को portfolio manager की separate fee देकर managed structure लेने की जरूरत नहीं होती।
PRIM vs PMS vs Mutual Fund: Full Comparison
| Feature | Mutual Fund | PRIM | PMS |
|---|---|---|---|
| Minimum investment | Scheme-specific; often low | ₹25 लाख | ₹50 लाख |
| What manager manages | Securities inside the scheme | Portfolio of eligible MF products | Client-specific securities portfolio |
| Customisation | Low to moderate at investor level | Higher at portfolio level | High, subject to mandate |
| Underlying products | Scheme portfolio | Direct MF plans, ETFs, index funds, SIFs | Broader permitted securities |
| Who decides allocation? | Investor selects schemes | Portfolio manager | Portfolio manager |
| Ownership structure | Units in pooled scheme | Eligible fund units in managed portfolio | Client-specific portfolio/holdings as applicable |
| Complexity | Lower | Medium | Higher |
PRIM और Mutual Fund में सबसे बड़ा फर्क क्या है?
Mutual Fund में आप scheme चुनते हैं। अगर आपके पास 25 लाख हैं, तो आप अलग-अलग mutual fund categories में खुद allocation कर सकते हैं। लेकिन कौन सा fund कितना रखना है, कब rebalance करना है और overlapping exposure कैसे reduce करना है, इसका फैसला आपको खुद करना पड़ता है।
PRIM में यही portfolio-level decision professional manager ले सकता है। Manager multiple eligible mutual fund products के बीच allocation कर सकता है और agreed strategy के अनुसार rebalancing कर सकता है।
इसलिए PRIM का core value “mutual fund access” नहीं है। Mutual Fund access पहले से available है। PRIM की value portfolio construction और professional management में है।
PRIM और PMS में क्या बड़ा फर्क है?
PMS में portfolio manager individual securities को directly manage कर सकता है, subject to permitted investment universe and mandate. PRIM का universe mutual fund-based है, जिसमें eligible direct mutual fund plans, ETFs, index funds और SIFs शामिल हैं।
इस वजह से PRIM diversification-friendly structure हो सकता है, जबकि PMS अधिक direct security selection और customisation के लिए useful हो सकता है। दोनों को “higher return product” मानना गलत है। Actual performance manager, market conditions, portfolio design और costs पर depend करेगी।
₹25 लाख वाले Investor के लिए कौन सा option?
₹25 लाख invest करने की capacity होने का मतलब यह नहीं कि आपको PRIM ही लेना चाहिए। पहले तीन सवाल पूछें:
- क्या आप खुद fund selection और rebalancing कर सकते हैं?
- क्या professional portfolio management के लिए separate fee देना आपके लिए worthwhile है?
- क्या आपका investment horizon इतना लंबा है कि market volatility tolerate कर सकें?
अगर आप simple investing चाहते हैं और खुद allocation manage कर सकते हैं, तो Mutual Fund route काफी हो सकता है। अगर capital ₹25 लाख से ऊपर है लेकिन आपको fund-level नहीं, portfolio-level professional management चाहिए, तो PRIM explore किया जा सकता है।
अगर capital ₹50 लाख या उससे ज्यादा है और आप direct securities तथा higher customisation चाहते हैं, तो PMS भी comparison में आ सकता है।
PRIM में Fees कितनी हो सकती है?
SEBI-approved PRIM framework में fixed management fee पर 1% of client AUM तक cap का provision बताया गया है, और performance-linked fee की भी अनुमति है, subject to the applicable framework and client agreement।
लेकिन सिर्फ 1% देखकर cost को ignore नहीं करना चाहिए। Underlying mutual fund products की expense ratio और applicable transaction/tax costs भी overall portfolio economics को प्रभावित कर सकती हैं। इसलिए all-in cost पूछना ज्यादा important है।
PMS की Fees और Costs कैसे अलग हो सकती हैं?
PMS में fee structure provider और mandate के अनुसार fixed fee, performance-linked fee या combination हो सकती है। इसके अलावा brokerage, taxes, operating expenses और transaction-related charges भी हो सकते हैं।
इसलिए PMS provider से सिर्फ “annual fee कितनी है?” मत पूछिए। पूरा fee schedule, performance-fee mechanism और all applicable costs लिखित में समझना बेहतर है।
Taxation में सबसे जरूरी फर्क
PRIM, PMS और Mutual Fund तीनों में taxation को portfolio structure के हिसाब से समझना जरूरी है। खास तौर पर PRIM में portfolio manager fund-level switches या rebalancing decisions करता है, तो applicable redemption/switch transaction capital-gains implications पैदा कर सकता है।
Mutual Fund investor में capital gain सामान्यतः units redeem या switch करने पर arise होता है। PMS में manager के द्वारा portfolio securities की खरीद-बिक्री investor के taxable records को प्रभावित करती है। इसलिए investment decision लेते समय after-tax return देखना important है, सिर्फ headline return नहीं।
Tax rates और holding-period rules asset type तथा applicable law पर depend करते हैं। ITR filing से पहले current Income Tax Department provisions verify करें।
PRIM किस Investor के लिए useful हो सकता है?
- जिसके पास ₹25 लाख या अधिक investible corpus है।
- जो multiple mutual fund products के बीच portfolio allocation खुद नहीं करना चाहता।
- जो professional monitoring और periodic rebalancing चाहता है।
- जो direct mutual fund route के साथ portfolio-level customisation चाहता है।
PRIM कब जरूरी नहीं है?
अगर आप basic asset allocation समझते हैं, low-cost index funds या diversified mutual funds चुन सकते हैं और साल में एक-दो बार portfolio rebalance खुद कर सकते हैं, तो PRIM की separate management fee जरूरी नहीं भी हो सकती।
₹25 लाख होना सिर्फ eligibility का सवाल है, suitability का नहीं। A managed product तभी meaningful है जब वह आपके लिए enough value add करता हो।
PMS किस Investor के लिए useful हो सकता है?
PMS उन investors के लिए relevant हो सकता है जो portfolio को अधिक customised तरीके से manage करवाना चाहते हैं और ₹50 लाख minimum investment threshold को meet करते हैं। Direct securities exposure और mandate-specific customisation इसकी important features हैं।
लेकिन higher customisation का मतलब guaranteed outperformance नहीं है। PMS चुनने से पहले concentration, drawdown, turnover, fees और manager track record को carefully review करें।
Mutual Fund किसके लिए सबसे practical है?
Mutual Fund route उन investors के लिए practical रहता है जो low entry barrier, diversification और simple investing process चाहते हैं। SIP, lump sum और multiple fund categories के जरिए investor अपना portfolio खुद build कर सकता है।
इसके लिए fund selection discipline जरूरी है। सिर्फ पिछला return देखकर schemes चुनना या एक ही category के कई similar funds रखना portfolio quality को improve नहीं करता।
₹25 लाख Portfolio का तीन तरीके से Example
| Route | ₹25 लाख में क्या होगा? | Decision-making |
|---|---|---|
| Mutual Fund | आप selected schemes में invest करेंगे | Fund selection + allocation आप करेंगे |
| PRIM | Eligible MF/ETF/index/SIF portfolio | Portfolio manager allocation/rebalance करेगा |
| PMS | ₹25 लाख minimum से below, so conventional PMS generally eligible नहीं | ₹50 लाख threshold पूरा करना होगा |
PRIM चुनने से पहले 10 Checks
- SEBI registration और exact PRIM offering verify करें।
- Minimum ₹25 लाख requirement और provider eligibility check करें।
- Portfolio किन direct mutual funds, ETFs, index funds या SIFs में invest करेगा, पूछें।
- Management fee और performance fee दोनों लिखित में समझें।
- Underlying fund expense ratio भी calculate करें।
- Rebalancing की frequency और approach समझें।
- Expected portfolio turnover और taxation impact पूछें।
- Benchmark और post-fee performance reporting समझें।
- Exit/termination process और applicable charges देखें।
- Investment को goal, risk tolerance और time horizon से match करें।
PMS चुनने से पहले 10 Checks
- SEBI-registered portfolio manager verify करें।
- Minimum ₹50 लाख investment requirement check करें।
- Discretionary या non-discretionary model समझें।
- Permitted securities और portfolio concentration limits जानें।
- Fixed fee और performance fee का पूरा structure पढ़ें।
- Brokerage, operating expenses और taxes जोड़कर all-in cost निकालें।
- Maximum drawdown और historical risk समझें।
- Manager का audited performance disclosure पढ़ें।
- Exit terms और portfolio transfer process देखें।
- Past return के साथ strategy consistency भी compare करें।
Related Investing Guides
₹25 लाख के investment options की broader planning के लिए ₹25 लाख Investment Options पढ़ें। Mutual Funds के core concepts के लिए Index Fund vs Mutual Fund और Direct vs Regular Mutual Fund guides useful हैं। Mutual Fund costs समझने के लिए Expense Ratio का असर देखें।
Long-term portfolio allocation के लिए Asset Allocation by Age & Salary और emergency liquidity के लिए Emergency Fund guide भी पढ़ें।
FAQs
1. PRIM का पूरा नाम क्या है?
PRIM का मतलब Portfolio Managers Route for Investing in Mutual Fund Units है।
2. PRIM में minimum investment कितना है?
2026 SEBI framework के अनुसार PRIM का minimum investment ₹25 लाख है।
3. PMS में minimum investment कितना है?
Conventional PMS के लिए minimum investment ₹50 लाख है।
4. क्या PRIM एक नया Mutual Fund है?
नहीं। PRIM एक portfolio-management route है जिसमें portfolio manager eligible mutual fund products के जरिए client portfolio manage करता है।
5. क्या ₹25 लाख होने पर PRIM लेना जरूरी है?
नहीं। ₹25 लाख सिर्फ PRIM की minimum-entry eligibility से जुड़ा है। Product suitability आपके goals, risk और management needs पर depend करती है।
6. PRIM में कौन से products use हो सकते हैं?
Framework के अनुसार eligible direct mutual fund plans, ETFs, index funds और SIFs का उपयोग किया जा सकता है, subject to the applicable framework and provider mandate.
7. क्या PRIM में guaranteed return मिलता है?
नहीं। PRIM market-linked portfolio-management route है और return guarantee नहीं होती।
8. Mutual Fund और PRIM में tax कौन सा बेहतर है?
कोई universal answer नहीं है। PRIM में portfolio-level switching/rebalancing से taxable transactions हो सकते हैं, जबकि self-managed Mutual Fund में redemption/switch investor control करता है। Actual tax effect portfolio और applicable law पर depend करेगा।
9. क्या PRIM PMS से cheaper है?
Minimum investment कम है, लेकिन “cheaper” कहना सिर्फ entry amount देखकर सही नहीं है। Management fee, performance fee, underlying fund costs और taxes मिलाकर total cost compare करें।
10. ₹25 लाख वाले investor के लिए सबसे simple option क्या है?
अगर investor खुद fund selection और asset allocation manage कर सकता है, तो diversified Mutual Fund portfolio सबसे simple route हो सकता है। Professional management की जरूरत होने पर PRIM compare किया जा सकता है।
निष्कर्ष
PRIM vs PMS vs Mutual Fund में सही option investor की जरूरत पर depend करता है। Mutual Fund सबसे accessible और simple route है। PRIM ₹25 लाख minimum entry के साथ professional portfolio management को mutual fund-based structure के जरिए उपलब्ध कराता है। PMS ₹50 लाख minimum के साथ ज्यादा direct और customised portfolio management दे सकता है।
₹25 लाख वाले investor के लिए PRIM एक interesting new option है, लेकिन इसे सिर्फ “premium mutual fund” समझकर select नहीं करना चाहिए। Fee + portfolio design + taxation + risk + manager quality + your own involvement को एक साथ compare करें। यही comparison long-term outcome को ज्यादा meaningful तरीके से प्रभावित करेगा।
उपयोगी संदर्भ
PRIM और PMS framework की latest regulatory information के लिए SEBI की official website देखें। Mutual Fund regulation के लिए SEBI Regulations और tax rules के लिए Income Tax Department की current guidance देखें।
लेखक के बारे में
Dinesh Rewale personal finance, mutual funds और investment topics पर practical, reader-focused content लिखते हैं। उनका उद्देश्य complex investment concepts को आसान भाषा में समझाना है ताकि readers risk, cost और suitability को समझकर बेहतर decisions ले सकें।
Disclaimer
PRIM, PMS, Mutual Fund products, fees, eligibility, taxation और SEBI rules समय-समय पर बदल सकते हैं। यह article general educational information है, personalised investment advice नहीं। Investment करने से पहले SEBI-registered provider की latest disclosure documents, applicable costs, tax implications और अपनी risk profile verify करें।