ELSS vs PPF vs Tax Saving FD: 2026 में किसमें Tax बचत बेहतर?
ELSS, PPF और Tax Saving FD तीनों popular tax-saving options हैं, लेकिन 2026 में “किसमें Tax बचत बेहतर है?” का जवाब सिर्फ return देखकर नहीं दिया जा सकता। सबसे पहले यह देखना जरूरी है कि आप Old Tax Regime में हैं या New Tax Regime में। Old Regime में eligible 80C investments पर combined ₹1.50 लाख तक deduction मिल सकता है, जबकि New Tax Regime में सामान्य 80C deduction उपलब्ध नहीं है।
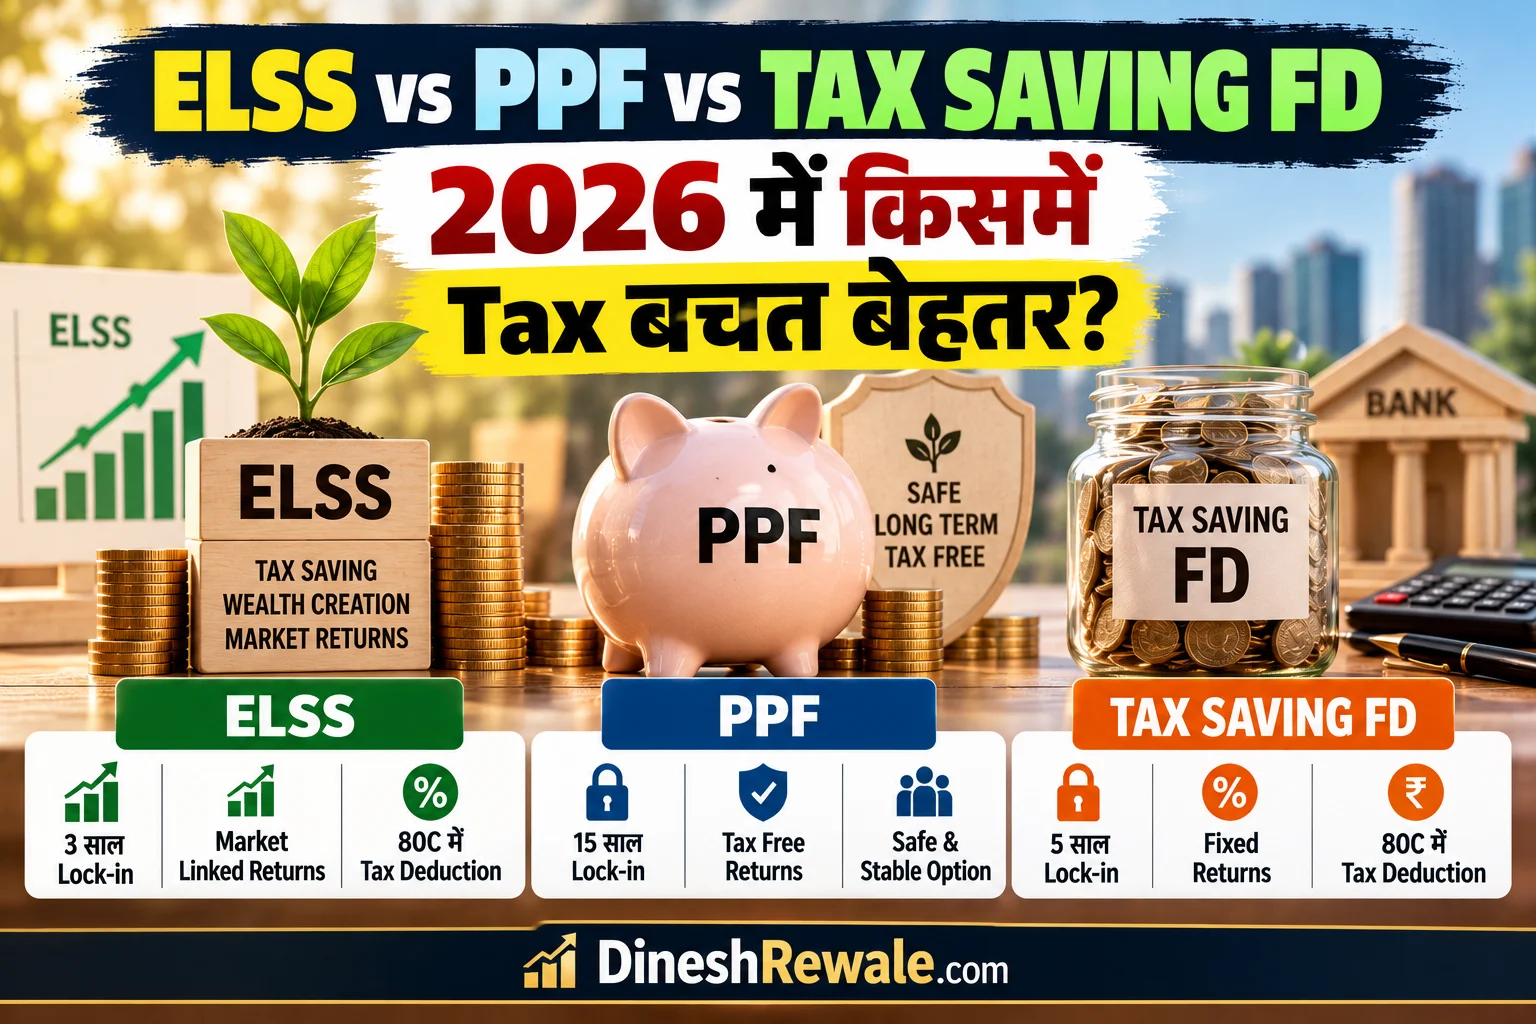
Quick Takeaway: Market-linked growth और 3-year lock-in पसंद है तो ELSS देख सकते हैं। Long-term conservative और tax-efficient saving चाहिए तो PPF useful हो सकता है। Fixed-return style और 5-year lock-in acceptable है तो Tax Saving FD एक option है। तीनों में से कोई भी हर investor के लिए automatically “best” नहीं है।
ELSS vs PPF vs Tax Saving FD: एक नजर में
| Feature | ELSS | PPF | Tax Saving FD |
|---|---|---|---|
| 80C benefit | Old Regime में eligible | Old Regime में eligible | Eligible 5-year bank term deposit |
| Lock-in | 3 साल | 15 साल की मूल maturity | 5 साल |
| Return | Market-linked | Government-notified interest rate | Bank-declared interest rate |
| Risk profile | Equity-market linked | Low market risk | Market-linked volatility नहीं |
| Earnings tax | Capital gains rules | Interest tax-exempt treatment | Interest taxable |
SEBI Investor के अनुसार ELSS equity-oriented mutual fund scheme है, जिसमें कम से कम 80% corpus equity और equity-related instruments में invest किया जाता है और इसका lock-in 3 साल है। India Post के recent material के अनुसार PPF में annual maximum deposit ₹1.50 लाख और मूल maturity period 15 साल है। Section 80C में कम से कम 5 साल की eligible bank term deposit भी शामिल है।
2026 में Tax Regime सबसे पहले क्यों देखें?
Income Tax Department के AY 2026-27 guidance में New Tax Regime को default regime बताया गया है, जबकि eligible taxpayers Old Tax Regime चुन सकते हैं। Old Regime में Section 80C की combined deduction limit ₹1.50 लाख है। New Regime में सामान्य Chapter VI-A deductions, जिसमें 80C भी शामिल है, उपलब्ध नहीं हैं, कुछ specified exceptions को छोड़कर।
इसलिए Old Regime में tax-saving investment चुनते समय 80C का फायदा महत्वपूर्ण हो सकता है। New Regime में product को केवल tax deduction के लिए चुनने के बजाय उसके return, risk, liquidity और goal fit को देखना चाहिए।
ELSS क्या है?
ELSS यानी Equity Linked Savings Scheme एक equity-oriented mutual fund category है। इसका 3-year lock-in Section 80C tax-saving options में सबसे कम lock-ins में से एक है। Equity exposure के कारण long-term wealth creation का potential हो सकता है, लेकिन returns market-linked हैं और guarantee नहीं होती।
ELSS के फायदे
- Old Regime में eligible investment के रूप में 80C deduction के लिए इस्तेमाल किया जा सकता है।
- 3 साल का lock-in PPF और 5-year Tax Saving FD से छोटा है।
- Long-term equity exposure से growth potential मिल सकता है।
ELSS की limitations
ELSS market risk वाला product है। Lock-in पूरा होने पर भी market conditions weak होने पर value आपके original expectation से कम हो सकती है। इसलिए ELSS को FD जैसा guaranteed-return product समझना गलत होगा।
एक और important point: ELSS में SIP करने पर हर installment की lock-in period अलग होती है। इसीलिए “SIP शुरू की और तीन साल बाद पूरी रकम unlock हो जाएगी” हमेशा सही नहीं है।
PPF क्या है?
PPF यानी Public Provident Fund long-term savings scheme है। India Post के अनुसार इसमें ₹500 minimum और ₹1.50 लाख तक annual deposit किया जा सकता है। मूल maturity period 15 साल है और account को applicable rules के अनुसार आगे extend किया जा सकता है। Interest rate सरकार समय-समय पर तय करती है। India Post के recent material में PPF interest को income tax से exempt बताया गया है।
PPF के फायदे
- Old Regime में eligible contribution पर 80C deduction मिल सकता है।
- Interest पर tax-exempt treatment इसकी बड़ी खासियत है।
- Long-term conservative savings के लिए useful structure है।
PPF की limitations
PPF short-term parking product नहीं है। इसकी मूल अवधि 15 साल है और premature closure तथा partial withdrawal पर specific rules लागू होते हैं। इसलिए आने वाले 1-3 साल में चाहिए पैसे को सिर्फ tax saving के कारण PPF में lock करना practical नहीं हो सकता।
PPF की पूरी जानकारी के लिए PPF क्या है? Interest, Tax और Maturity पढ़ सकते हैं।
Tax Saving FD क्या है?
Tax Saving FD एक eligible 5-year bank term deposit है। Section 80C में qualifying bank term deposit के लिए कम से कम पांच साल की fixed period का provision है। इसका return equity market की तरह fluctuate नहीं करता, लेकिन interest taxable होता है।
Tax Saving FD में principal qualifying 80C investment हो सकता है, लेकिन earned interest tax-free नहीं होता। इसलिए FD का post-tax return आपके tax slab और अन्य income के context में देखना चाहिए।
Tax Saving FD के फायदे
- Old Regime में eligible 80C investment हो सकता है।
- Interest rate investment के समय सामान्यतः fixed structure देता है।
- Equity-market volatility नहीं होती।
Tax Saving FD की limitations
- 5-year lock-in रहता है।
- Interest taxable होने के कारण post-tax return headline rate से कम हो सकता है।
- Long-term wealth creation potential ELSS जैसी equity investment से अलग है।
FD rules और practical checks के लिए FD New Rules 2026 और 8.5% FD Interest: पैसा लगाने से पहले 7 जरूरी बातें देखें।
Tax Saving के मामले में कौन आगे?
अगर सिर्फ tax treatment compare करें, तो PPF का structure मजबूत दिखता है क्योंकि Old Regime में qualifying contribution पर 80C deduction के साथ interest का tax-exempt treatment भी मिलता है। ELSS में 80C deduction के बाद redemption पर applicable capital gains tax rules लागू होते हैं। Tax Saving FD में initial 80C benefit हो सकता है, लेकिन interest taxable रहता है।
| Tax Point | ELSS | PPF | Tax Saving FD |
|---|---|---|---|
| Old Regime 80C | Eligible subject to rules | Eligible | Eligible 5-year deposit subject to rules |
| Earnings during investment | Market-linked | Tax-exempt interest treatment | Taxable interest |
| Exit | Capital gains tax may apply | Tax-exempt maturity treatment under PPF rules | Interest remains taxable |
| New Regime 80C | No normal 80C deduction | No normal 80C deduction | No normal 80C deduction |
ELSS पर 2026 में Tax कैसे लग सकता है?
Eligible equity-oriented mutual fund units पर current capital gains rules लागू होते हैं। Income Tax Department के guidance के अनुसार Section 112A में specified equity shares, equity-oriented mutual fund units और business trust units पर ₹1.25 लाख से ऊपर के eligible long-term capital gains पर 12.5% tax लागू हो सकता है, subject to applicable conditions। ELSS का lock-in 3 साल होने के कारण redemption generally long-term holding से आगे होता है, लेकिन actual tax calculation investment dates और applicable rules पर depend करेगी।
इसलिए “ELSS का पूरा profit tax-free है” कहना सही नहीं होगा।
₹1.50 लाख निवेश करने पर Tax Saving कितनी हो सकती है?
Section 80C की combined deduction limit ₹1.50 लाख है। इसका मतलब यह नहीं कि ELSS में ₹1.50 लाख, PPF में ₹1.50 लाख और Tax Saving FD में ₹1.50 लाख अलग-अलग deduction मिल सकती है। आपके सभी eligible 80C payments और investments मिलाकर qualifying deduction अधिकतम ₹1.50 लाख तक हो सकती है।
उदाहरण के लिए, अगर EPF, life insurance premium या home-loan principal से आपकी 80C limit पहले ही काफी हद तक इस्तेमाल हो चुकी है, तो नया tax-saving investment additional deduction उतनी ही मात्रा में नहीं देगा।
| Marginal tax rate | ₹1.50 लाख deduction पर basic tax impact* | 4% cess सहित illustrative impact* |
|---|---|---|
| 5% | ₹7,500 | ₹7,800 |
| 20% | ₹30,000 | ₹31,200 |
| 30% | ₹45,000 | ₹46,800 |
*यह केवल illustration है। Actual benefit taxable income, tax slab, rebate, surcharge, cess, existing 80C usage और अन्य applicable rules पर depend करता है।
Return के हिसाब से कौन बेहतर?
ELSS: Market-linked होने के कारण growth potential ज्यादा हो सकता है, लेकिन return fixed नहीं है और downside risk भी है।
PPF: Government-notified rate पर interest मिलता है। यह equity की तरह daily market volatility का product नहीं है और इसका interest tax-exempt treatment इसे tax-efficient बनाता है।
Tax Saving FD: Predictable fixed-interest structure देता है, लेकिन taxable interest के कारण post-tax return समझना जरूरी है।
इसलिए “highest return” और “best post-tax outcome” अलग concepts हो सकते हैं।
किस Investor के लिए कौन-सा Option?
| Need | Potential Fit | Why |
|---|---|---|
| Long-term growth + market risk acceptable | ELSS | Equity exposure और 3-year lock-in |
| Long-term conservative saving | PPF | Long tenure और tax-efficient interest treatment |
| Fixed-return style + 5-year lock-in | Tax Saving FD | Predictable interest profile |
यह suitability framework है, personal recommendation नहीं।
क्या तीनों में पैसा बांटना जरूरी है?
नहीं। Tax saving के नाम पर तीनों products में पैसा डालना जरूरी नहीं है। पहले अपनी existing 80C commitments देखें। उसके बाद यह तय करें कि आपके portfolio में growth, stability और liquidity का balance कैसा है।
अगर आपका equity exposure पहले ही बहुत ज्यादा है, तो सिर्फ 80C deduction के लिए ELSS जोड़ने से concentration और volatility बढ़ सकती है। दूसरी तरफ अगर आपका portfolio बहुत conservative है और long-term growth goal है, तो ELSS जैसी equity category का अलग role हो सकता है।
Broader portfolio planning के लिए उम्र और Salary के हिसाब से Asset Allocation guide देखें।
2026 में Tax Saving चुनने का 7-Step Formula
- Tax regime check करें: Old या New?
- 80C usage calculate करें: EPF, insurance premium, home-loan principal और दूसरे eligible items जोड़ें।
- Goal देखें: पैसा कब चाहिए?
- Risk तय करें: market volatility कितनी comfortable है?
- Post-tax return सोचें: headline return पर नहीं रुकें।
- Lock-in compare करें: 3, 5 या 15 साल की commitment practical है?
- Portfolio role तय करें: नया product existing investments में क्या value add करेगा?
इन 6 गलतियों से बचें
1. New Regime में सिर्फ 80C के लिए investment करना
अगर सामान्य 80C deduction available नहीं है, तो सिर्फ tax-saving label देखकर product चुनना सही logic नहीं है।
2. ₹1.50 लाख limit को हर product के लिए अलग समझना
Section 80C की limit aggregate है। तीनों products के लिए अलग-अलग ₹1.50 लाख deduction नहीं मिलता।
3. ELSS को guaranteed-return product समझना
ELSS equity-market linked है। Return fixed नहीं है।
4. Tax Saving FD interest को tax-free मानना
FD interest taxable होता है। इसलिए post-tax return देखें।
5. PPF को short-term fund की तरह use करना
PPF long-term product है। Near-term expenses और emergency needs के लिए अलग liquid money रखें।
6. Tax saving को investment का अकेला reason बनाना
एक अच्छा tax benefit भी खराब investment fit को अच्छा नहीं बना देता। Goal, risk, liquidity और time horizon साथ देखें।
ELSS vs PPF vs Tax Saving FD: Final Verdict
Tax saving में universal winner नहीं है। Old Regime में 80C deduction की जरूरत है तो तीनों useful हो सकते हैं, लेकिन उनका role अलग है।
ELSS market risk स्वीकार करने वाले long-term investor के लिए growth-oriented option हो सकता है। PPF long-term conservative और tax-efficient savings के लिए strong fit हो सकता है। Tax Saving FD fixed-interest style चाहने वाले investor के लिए practical choice हो सकता है, लेकिन taxable interest के कारण post-tax outcome देखना जरूरी है।
सबसे पहले tax regime और existing 80C usage check करें। उसके बाद goal, risk, lock-in और post-tax return की तुलना करें। यही 2026 में tax-saving investment चुनने का practical तरीका है।
और पढ़ें
- PPF vs FD vs SIP: 2026 में ₹5 लाख कहाँ लगाएं?
- PPF, NSC और SCSS Interest Rates Oct-Dec 2026
- PPF में ₹5,000 हर महीने जमा करें: 15 साल में कितना बनेगा?
- Mutual Fund SIP, Switch, STP और Redemption पर Tax
- Direct vs Regular Mutual Fund
FAQs
2026 में ELSS, PPF और Tax Saving FD में सबसे अच्छा कौन है?
यह आपके tax regime, goal, risk और time horizon पर depend करता है। Tax deduction के लिए Old Regime और existing 80C usage पहले check करें।
क्या New Tax Regime में ELSS, PPF या Tax Saving FD पर 80C deduction मिलता है?
सामान्य 80C deduction New Tax Regime में available नहीं है। इसलिए इन products को सिर्फ 80C tax saving के लिए चुनना सही reason नहीं है।
क्या PPF का interest tax-free है?
PPF का interest tax-exempt treatment इसकी प्रमुख विशेषताओं में है। PPF withdrawals और maturity पर applicable scheme rules भी ध्यान में रखें।
क्या Tax Saving FD का interest tax-free है?
नहीं। Tax Saving FD का qualifying principal 80C benefit दे सकता है, लेकिन interest taxable रहता है।
क्या ₹1.5 लाख ELSS और ₹1.5 लाख PPF दोनों पर 80C deduction मिलेगा?
नहीं। Section 80C की combined limit ₹1.50 लाख है। Existing eligible payments भी इसी limit में count हो सकते हैं।
ELSS में 3 साल बाद tax लगता है?
ELSS redemption पर applicable capital gains rules लागू होते हैं। Eligible equity-oriented mutual fund LTCG पर current law के अनुसार ₹1.25 लाख से ऊपर 12.5% tax लागू हो सकता है, subject to conditions.
क्या ELSS में SIP किया जा सकता है?
हाँ। लेकिन हर SIP installment की lock-in period अलग होती है।
Useful Official Resources
- Income Tax Department: AY 2026-27 Tax Regime और Deductions
- Income Tax Department: Section 80C
- SEBI Investor: ELSS Guide
- India Post: PPF and Small Savings Information
लेखक
Dinesh Rewale
वित्त, Business और Real Estate जैसे विषयों पर reader-first और practical content लिखते हैं, ताकि complex financial topics को आसान भाषा में समझा जा सके।
Facebook पर Dinesh Rewale से जुड़ें
Disclaimer
यह लेख केवल educational और informational purpose के लिए है। Tax rules, rates, deductions और product conditions समय के साथ बदल सकते हैं। इसमें दी गई information personalized financial advice नहीं है। किसी भी tax या investment decision से पहले अपनी income, tax regime, existing deductions, goals, risk profile और applicable rules की जांच करें। जरूरत होने पर CA, tax professional या SEBI-registered investment adviser से सलाह लें।