Loan Against Property: 7 फायदे और 7 बड़े Risks
Loan Against Property (LAP) एक secured loan है जिसमें आपकी residential या commercial property lender के पास security के तौर पर mortgage रहती है। इसके बदले आपको relatively बड़ा loan amount मिल सकता है और repayment tenure भी लंबा हो सकता है। लेकिन इसका सबसे बड़ा risk भी यही है: loan repay नहीं करने की…
Loan Against Property (LAP) एक secured loan है जिसमें आपकी residential या commercial property lender के पास security के तौर पर mortgage रहती है। इसके बदले आपको relatively बड़ा loan amount मिल सकता है और repayment tenure भी लंबा हो सकता है। लेकिन इसका सबसे बड़ा risk भी यही है: loan repay नहीं करने की स्थिति में pledged property पर lender का legal claim बन सकता है।
सीधी बात: LAP तब useful हो सकता है जब आपको बड़ा fund चाहिए और आपके पास clear-title property है, लेकिन इसे सिर्फ इसलिए लेना सही नहीं है क्योंकि property की value ज्यादा है। Loan amount, EMI, interest, processing/mortgage charges, end-use और property risk को साथ में देखना जरूरी है। कई lenders residential और commercial property के against financing देते हैं, लेकिन actual LTV, rate, tenure और eligibility lender के rules पर depend करते हैं। उदाहरण के लिए HDFC Bank की current LAP information में property value के एक हिस्से तक funding और up to 15 years tenure बताया गया है।
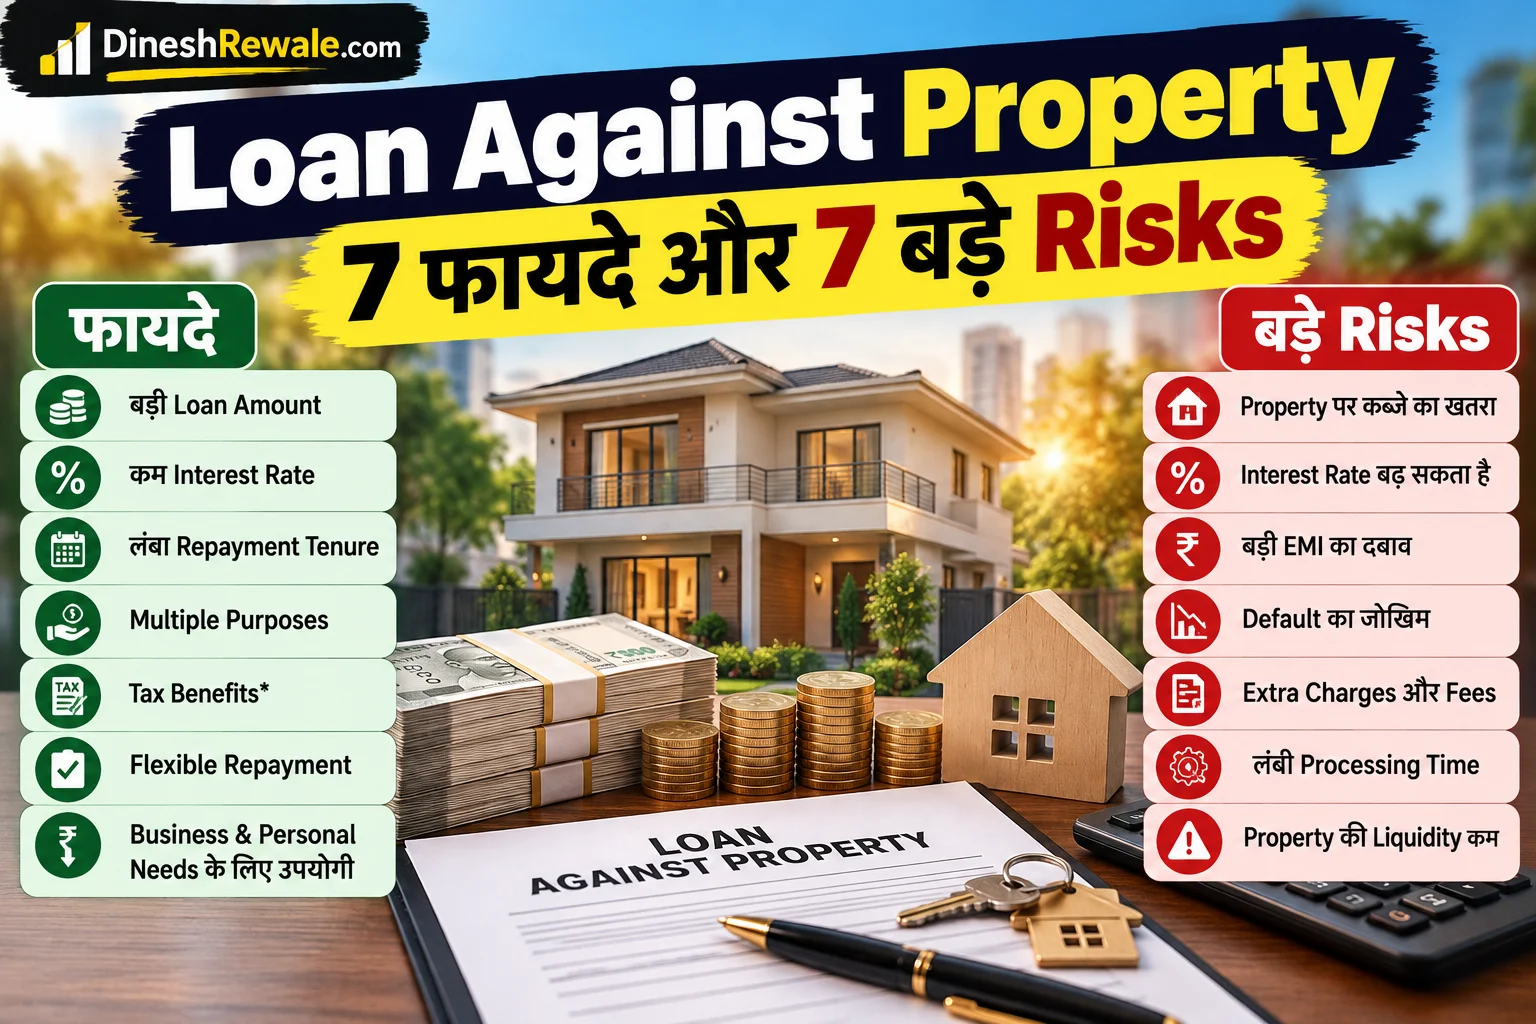
In Short: LAP के बड़े फायदे हैं high loan amount, long tenure और multiple eligible uses। बड़े risks हैं property को collateral रखना, valuation-based lower-than-expected funding, interest cost, charges और repayment failure की स्थिति में property पर risk।
Loan Against Property क्या है?
Loan Against Property को सरल भाषा में समझें तो आप अपनी existing property को mortgage करके loan लेते हैं। यह property आपकी residential, commercial या कुछ मामलों में अन्य eligible property हो सकती है। Loan के दौरान property security के तौर पर lender के पास रहती है, जबकि ownership सामान्यतः borrower के पास बनी रहती है, subject to the mortgage terms.
LAP को home loan से अलग समझना जरूरी है। Home loan आम तौर पर property खरीदने, निर्माण या eligible housing purpose के लिए structured होता है, जबकि LAP में existing property को collateral बनाकर funds जुटाए जाते हैं। Lender के product rules के अनुसार personal या business needs के लिए loan use किया जा सकता है। HDFC Bank अपनी LAP information में business needs, education, medical expenses, marriage और debt consolidation जैसे examples देता है।
LAP काम कैसे करता है?
- Property assessment: lender property की legal और technical verification करता है.
- Income और credit assessment: आपकी repayment capacity, income, existing liabilities और credit profile check होती है.
- LTV तय होता है: property value का पूरा पैसा loan के रूप में नहीं मिलता; lender अपनी policy के अनुसार funding percentage तय करता है.
- Mortgage creation: loan sanction होने पर property lender के favour में security के तौर पर mortgage होती है.
- Disbursement: documentation complete होने के बाद sanctioned amount disburse किया जाता है.
- EMI repayment: borrower agreed tenure के दौरान principal और interest repay करता है.
Loan Against Property के 7 बड़े फायदे
1. Personal Loan से ज्यादा बड़ा loan amount मिल सकता है
क्योंकि LAP secured loan है, lender के पास collateral रहता है। इसलिए eligible borrower को unsecured personal loan की तुलना में बड़ा amount मिल सकता है। Actual amount property valuation, income, credit profile और lender policy पर depend करेगा। HDFC Bank की current product information में property market value के up to 65% तक funding का example दिया गया है।
2. Repayment tenure लंबा हो सकता है
Long tenure का मतलब monthly EMI को relatively manageable रखा जा सकता है। कई lenders LAP में 15 साल तक tenure offer करते हैं। SBI और HDFC Bank दोनों की published LAP information में maximum tenure up to 15 years का reference मिलता है। SBI की LAP details और HDFC Bank की LAP details देखें।
3. Funds का use कई जरूरतों में किया जा सकता है
Product terms के हिसाब से LAP का इस्तेमाल business expansion, education, medical expenses, marriage या debt consolidation जैसी जरूरतों के लिए किया जा सकता है। Exact permitted end-use lender से confirm करना जरूरी है।
4. Existing property से liquidity मिलती है
अगर आपकी property valuable है लेकिन immediate cash available नहीं है, तो उसे बेचने के बजाय mortgage करके funds जुटाने का option मिल सकता है। इससे ownership transfer किए बिना capital access करने की सुविधा मिलती है, subject to loan approval.
5. Secured structure के कारण pricing competitive हो सकती है
Collateral होने के कारण LAP की interest rate अक्सर unsecured loans से lower हो सकती है, लेकिन यह universal rule नहीं है। Borrower profile, property, lender, loan amount और rate type के अनुसार pricing काफी बदल सकती है। इसलिए “LAP हमेशा सस्ता होता है” मानना सही नहीं है.
6. Business के लिए large-ticket funding में मदद
Business owner के लिए working capital, expansion, equipment या other business needs में LAP useful funding source हो सकता है, खासकर जब property collateral available हो। लेकिन business purpose के loan में cash flow और repayment visibility पहले calculate करना जरूरी है.
7. Long-term repayment planning की flexibility
कुछ lenders term loan के अलावा overdraft-type structures भी offer करते हैं। Product-specific features अलग हो सकते हैं, इसलिए sanction letter में repayment structure, interest calculation और charges ध्यान से पढ़ें।
Loan Against Property के 7 बड़े Risks
1. Property पर सबसे बड़ा risk
LAP का सबसे महत्वपूर्ण risk यह है कि property collateral होती है। अगर borrower लगातार repayment नहीं करता और loan default की स्थिति में जाता है, तो lender agreement और applicable law के अनुसार secured asset पर recovery action ले सकता है। इसलिए LAP को “property की value के against free cash” समझना खतरनाक हो सकता है.
2. Property की पूरी market value के बराबर loan नहीं मिलता
मान लीजिए आपकी property ₹1 करोड़ की है। इसका मतलब यह नहीं कि ₹1 करोड़ का LAP मिल जाएगा। LTV limit और lender की valuation के कारण sanctioned amount काफी कम हो सकता है। कुछ lenders 50% से 65% तक के indicative limits publish करते हैं, लेकिन final amount borrower और property assessment पर depend करता है।
3. Interest का total cost बड़ा हो सकता है
Long tenure EMI को कम कर सकता है, लेकिन tenure बढ़ने पर total interest outgo बढ़ सकता है। इसलिए सिर्फ “EMI कम है” देखकर loan select न करें। Principal, interest rate, tenure और total payable amount एक साथ compare करें.
4. Property valuation कम आई तो expected funding नहीं मिलेगी
Lender अपनी valuation कर सकता है। Market में owner को जो value लगती है, वह lender की assessed value से अलग हो सकती है। Lower valuation होने पर loan amount भी अपेक्षा से कम हो सकता है.
5. Processing और mortgage-related charges होते हैं
Interest के अलावा processing fee, legal/technical charges, stamp duty, mortgage charges, documentation या other applicable fees हो सकते हैं। RBI की consumer guidance भी borrowers को loan के different fees और charges समझकर compare करने की सलाह देती है।
6. Floating rate होने पर EMI बदल सकती है
Floating-rate loan में benchmark या lender’s pricing changes के कारण interest rate बदल सकती है। इससे EMI बढ़ सकती है या tenure बढ़ सकता है। Loan sign करने से पहले rate reset mechanism और possible EMI/tenure impact समझना जरूरी है.
7. गलत purpose के लिए loan लेने से financial pressure बढ़ सकता है
अगर LAP से lifestyle spending, speculative investment या ऐसी liability finance की जाती है जिसके cash flows uncertain हैं, तो repayment risk बढ़ सकता है। Secured debt का उपयोग ideally a clearly defined need और predictable repayment plan के साथ होना चाहिए.
Benefits vs Risks: एक नजर में
₹1 करोड़ की Property पर LAP का Example
मान लीजिए lender की assessed property value ₹1 करोड़ है और उसकी applicable LTV policy 60% है। ऐसे case में theoretical maximum loan ₹60 लाख हो सकता है। लेकिन actual sanction income, credit score, existing EMIs, age, property type और lender assessment पर depend करेगा.
अगर ₹60 लाख का loan 10% annual interest पर 15 साल के लिए लिया जाए, तो illustrative EMI लगभग ₹64,507 प्रति माह आती है। यह सिर्फ mathematical example है, किसी lender का quoted rate नहीं। Interest rate या tenure बदलने पर EMI और total interest दोनों बदल जाएंगे.
Practical lesson: सिर्फ eligible loan amount देखकर खुश न हों। पहले यह देखें कि आपकी monthly cash flow इतनी EMI comfortably support करती है या नहीं.
LAP लेने से पहले कौन-कौन से Charges check करें?
- Processing fee
- Legal and technical valuation charges
- Mortgage / stamp duty related costs
- Documentation and CERSAI-related charges, where applicable
- Late payment / penal charges
- Prepayment / foreclosure terms
- Rate conversion or other service charges, if applicable
Charges lender और product के अनुसार काफी अलग हो सकते हैं। उदाहरण के लिए Bank of India की LAP page पर processing, mortgage और other actual-basis charges अलग से listed हैं।वहीं RBI की responsible lending directions के अनुसार applicable charges और prepayment terms borrower-facing documents में transparent होने चाहिए।
2026 में LAP Prepayment Charges पर क्या ध्यान दें?
1 जनवरी 2026 से RBI की नई pre-payment directions लागू हैं। कई categories में individual borrowers के floating-rate loans पर prepayment charges नहीं लगाए जा सकते, लेकिन applicability lender type, loan purpose और loan structure पर depend करती है। इसलिए “हर LAP पर prepayment charge zero है” ऐसा universal statement सही नहीं होगा। Sanction letter और Key Facts Statement में applicable terms जरूर देखें।
Loan Against Property के लिए Eligibility में क्या देखा जाता है?
Lender आम तौर पर age, income, employment/business profile, credit history, existing liabilities और property documents देखता है। Property की legal ownership, title clarity, construction status और valuation भी महत्वपूर्ण होते हैं। Salaried और self-employed applicants दोनों कई LAP products में eligible हो सकते हैं। HDFC Bank की current eligibility information भी salaried और self-employed applicants को cover करती है।
LAP के लिए कौन से Documents लग सकते हैं?
Commonly identity proof, address proof, income proof और property documents मांगे जाते हैं। Self-employed applicants से business या financial records भी मांगे जा सकते हैं। Exact checklist lender और applicant profile के अनुसार बदलती है।
Loan Against Property किन लोगों के लिए Useful हो सकता है?
- जिनके पास clear-title property है और उन्हें relatively बड़ा loan amount चाहिए.
- Business expansion के लिए documented और predictable cash flow वाले borrowers.
- ऐसे borrowers जिनके लिए unsecured loan amount पर्याप्त नहीं है.
- ऐसे cases जहां long repayment tenure cash-flow management में मदद करती है.
LAP कब Avoid करना बेहतर हो सकता है?
- जब EMI आपकी monthly cash flow को लगातार दबाव में डालती हो.
- जब loan सिर्फ lifestyle spending के लिए लेना हो.
- जब repayment future bonus या uncertain income पर पूरी तरह dependent हो.
- जब property family की primary residence हो और default risk manage करने की capacity कमजोर हो.
- जब loan की total cost, fees और end-use आपको clear नहीं है.
LAP लेने से पहले 10-Point Checklist
- Property का clear title और ownership verify करें.
- Lender की valuation को समझें.
- Actual LTV और sanctioned amount compare करें.
- Fixed vs floating rate समझें.
- EMI के साथ total interest payable देखें.
- Processing, legal और mortgage charges लिखित में लें.
- Prepayment rules पढ़ें.
- Loan का exact end-use तय करें.
- Existing EMIs के साथ combined debt burden calculate करें.
- Worst-case scenario में property risk समझे बिना sign न करें.
Useful Reading
Property की सही value समझने के लिए Flat की सही Price कैसे Calculate करें? पढ़ सकते हैं। Home loan और EMI planning समझने के लिए Home Loan EMI Salary का कितना % होना चाहिए? वाली guide भी useful है। अगर loan के कारण monthly cash flow दबाव में आने की आशंका है, तो Emergency Fund: 3, 6 या 9 महीने का कितना रखें? देखें.
Final Takeaway
Loan Against Property के benefits बड़े हैं, लेकिन risks भी equally important हैं. आपको property के against बड़ा loan और long repayment tenure मिल सकता है, लेकिन property collateral होने के कारण repayment failure की cost personal loan से कहीं ज्यादा गंभीर हो सकती है.
इसलिए LAP को “cheap money” की तरह नहीं बल्कि secured debt backed by your property की तरह देखें। Loan amount, EMI, interest, total payable amount, charges, prepayment rules और end-use को समझने के बाद ही decision लें.
Loan Against Property: FAQs
Loan Against Property क्या होता है?
यह secured loan है जिसमें borrower अपनी eligible residential या commercial property को collateral के तौर पर mortgage करता है और उसके against loan लेता है.
LAP का सबसे बड़ा फायदा क्या है?
मुख्य फायदे high funding potential, longer tenure और multiple eligible uses हैं। Actual benefits lender policy और borrower profile पर depend करते हैं.
LAP का सबसे बड़ा risk क्या है?
सबसे बड़ा risk pledged property है। लंबे समय तक repayment default होने पर lender applicable recovery process के तहत secured property पर action ले सकता है.
क्या LAP personal loan से सस्ता होता है?
कई cases में secured nature के कारण LAP pricing personal loan से competitive हो सकती है, लेकिन यह guaranteed नहीं है। Actual rate borrower profile, lender और product पर depend करती है.
क्या LAP से business के लिए पैसा ले सकते हैं?
कई lenders business needs के लिए LAP offer करते हैं। Actual permitted end-use और documentation lender-specific होते हैं.
Property की पूरी value का loan मिलता है?
नहीं। Loan amount lender की LTV policy और property valuation के साथ आपकी income और repayment capacity पर depend करता है.
LAP की maximum tenure कितनी हो सकती है?
कई lenders 15 साल तक tenure offer करते हैं, लेकिन actual tenure age, lender policy और applicant profile पर depend करता है।
क्या LAP में prepayment charge हमेशा लगता है?
नहीं, 2026 में RBI की नई directions के तहत कुछ floating-rate loans पर individual borrowers के लिए prepayment charges प्रतिबंधित हैं। इस rule की details RBI के latest applicable directions में check करें।लेकिन सभी LAP structures automatically exempt नहीं हैं, इसलिए अपने loan documents में exact applicability check करें.
LAP लेने से पहले सबसे जरूरी क्या check करें?
Property valuation, LTV, interest rate, EMI, total interest, charges, prepayment terms, legal title और repayment capacity सबसे पहले check करें.
लेखक
Dinesh Rewale
Dinesh Rewale एक independent content creator और personal finance writer हैं, जो banking, credit cards, saving, investing और everyday money decisions को आसान भाषा में समझाने पर लिखते हैं। उनका फोकस practical, reader-first और responsible financial information पर है.
Facebook पर Dinesh Rewale से जुड़ें
Disclaimer
यह लेख केवल सामान्य financial education के उद्देश्य से है। Loan Against Property की eligibility, interest rate, LTV, tenure, charges, permitted end-use और prepayment terms lender तथा borrower profile के अनुसार अलग हो सकते हैं। किसी loan को लेने से पहले lender के latest sanction letter, Key Facts Statement, loan agreement और applicable terms जरूर पढ़ें।