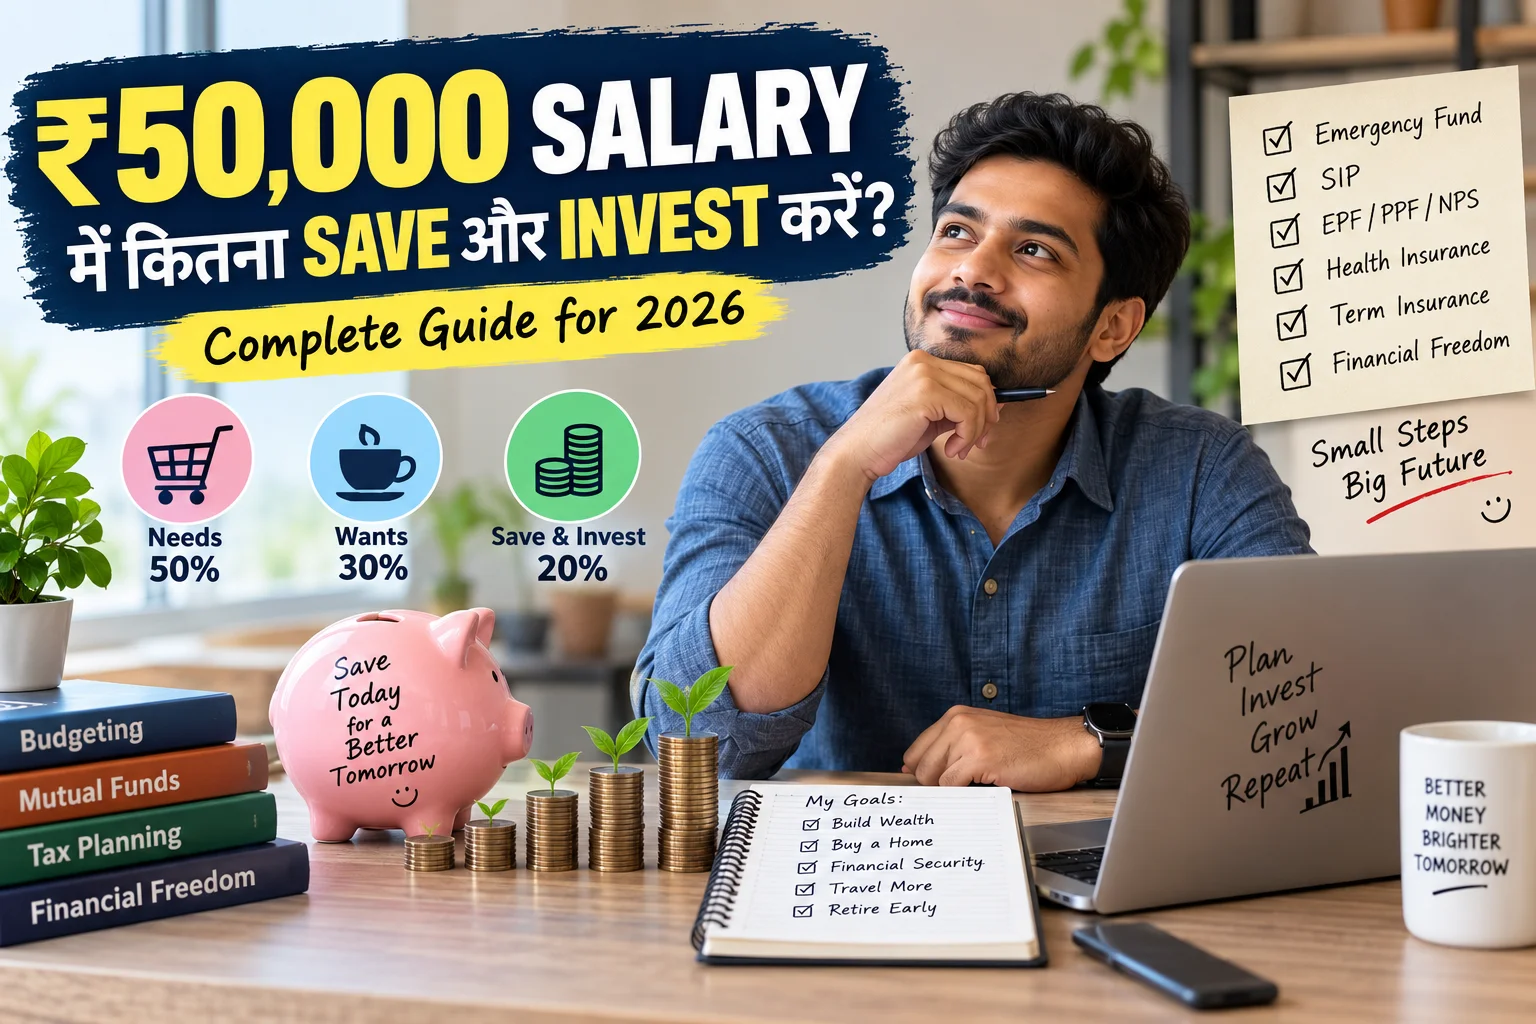
₹50,000 Salary में कितना Save और Invest करें? 2026 Guide
महीने की शुरुआत में ₹50,000 account में आते हैं, लेकिन महीने के आखिर तक यह समझ नहीं आता कि कितना पैसा वास्तव में बचा और कितना invest हुआ। Rent, groceries, travel, parents की मदद, EMI, insurance, subscriptions और अचानक आने वाले खर्च मिलकर salary को धीरे-धीरे खा लेते हैं। इसलिए सवाल सिर्फ यह नहीं है कि ₹50,000 Salary में कितना Save और Invest करें? असली सवाल है: ऐसा कौन-सा monthly system बनाया जाए जो आपकी current life को भी चलाए और future goals के लिए पैसा भी बनाए?
इस guide में ₹50,000 को किसी एक rigid rule में फिट करने की कोशिश नहीं की गई है। यहां तीन अलग situations के लिए practical allocation दिया गया है: high expenses वाला व्यक्ति, balanced setup वाला salaried employee और low expenses के कारण ज्यादा save करने वाला व्यक्ति। साथ ही emergency fund, debt, insurance, SIP, short-term goals और salary बढ़ने पर Step-Up SIP को एक ही framework में रखा गया है।
महत्वपूर्ण assumption: नीचे के मुख्य examples में ₹50,000 को monthly in-hand/take-home salary माना गया है। अगर ₹50,000 आपकी gross salary या CTC है, तो actual budget अलग होगा क्योंकि PF, tax और दूसरे payroll deductions पहले निकल सकते हैं।
Quick Answer: ₹50,000 Salary में कितना Save और Invest करें?
- Minimum practical target: ₹10,000–₹12,500 प्रति माह future के लिए अलग करना एक useful starting range हो सकती है।
- Balanced target: ₹15,000–₹17,500 प्रति माह, जिसमें emergency/short-term saving और long-term investing दोनों शामिल हों, कई low-to-moderate expense situations में संभव है।
- Aggressive saving: ₹20,000 या उससे ज्यादा तभी रखें जब rent, EMI और family responsibilities manageable हों और cash buffer बना हुआ हो।
- Emergency fund अधूरा है तो पूरे surplus को SIP में डालने के बजाय पहले safety bucket बनाएं।
- High-cost debt होने पर पहले interest burden देखें। Credit card rollover या महंगे debt के साथ aggressive investing कई बार गलत priority बन जाती है।
- Salary बढ़े तो investment amount भी बढ़ाएं। हर increment का एक हिस्सा Step-Up SIP में डालना lifestyle inflation को control करने में मदद कर सकता है।
₹50,000 Salary का सबसे Practical Budget क्या हो सकता है?
50/30/20 जैसी popular budgeting rules useful starting points हैं, लेकिन इन्हें कानून की तरह follow करना जरूरी नहीं है। SEBI की investor education material भी budgeting, regular saving, emergency fund और goal-based investing को financial planning का हिस्सा मानती है। इसलिए आपकी salary का सही allocation आपकी actual obligations पर निर्भर करेगा।
| Bucket | ₹50,000 का Practical Allocation | Amount | क्या शामिल करें |
|---|---|---|---|
| Essential Expenses | 45%–50% | ₹22,500–₹25,000 | Rent, food, utilities, commute, minimum EMI |
| Long-term Investment | 15%–20% | ₹7,500–₹10,000 | Goal-based SIP, retirement investing |
| Emergency / Short-term Saving | 10%–15% | ₹5,000–₹7,500 | Emergency fund, annual bills, near-term goals |
| Wants / Lifestyle | 10%–15% | ₹5,000–₹7,500 | Dining out, entertainment, shopping |
| Insurance / Irregular Costs | 5%–10% | ₹2,500–₹5,000 | Insurance premiums, gifts, medical or annual expenses |
इस model में long-term investment और savings को अलग रखा गया है। यही distinction महत्वपूर्ण है। Savings का बड़ा हिस्सा liquidity और near-term stability के लिए हो सकता है, जबकि investment का उद्देश्य आपके long-term goals के लिए capital growth हो सकता है।
Practical Tip: अगर आपकी financial foundation अभी बन रही है, तो “मैं SIP में कितना डाल सकता हूं?” से पहले “अगर अगले महीने income रुक जाए तो मैं कितने महीनों तक बिना नया debt लिए चल सकता हूं?” पूछिए।
₹50,000 Salary में Saving और Investment का फर्क समझिए
बहुत से salaried employees saving और investing को एक ही bucket समझते हैं। लेकिन दोनों की जरूरत अलग हो सकती है। Emergency fund, अगले साल की insurance premium, छह महीने बाद होने वाला relocation या दो साल बाद की शादी के लिए अलग liquidity चाहिए। वहीं retirement जैसे long-term goal को लंबे time horizon के हिसाब से invest किया जा सकता है।
| उद्देश्य | आम तौर पर Horizon | Focus | ₹50,000 Salary में Example |
|---|---|---|---|
| Emergency fund | अचानक जरूरत | Liquidity और capital access | ₹5,000–₹7,500 monthly build-up |
| Near-term goal | 0–3 साल | Capital protection और liquidity | अलग savings bucket |
| Medium-term goal | 3–5 साल | Goal के हिसाब से risk | Down payment corpus |
| Long-term goal | 5–10+ साल | Growth + diversification | ₹7,500–₹10,000 SIP starting point |
| Retirement | 10–20+ साल | Long-term compounding | Income बढ़ने के साथ Step-Up SIP |
पहला सवाल: आपकी वास्तविक Investment Capacity कितनी है?
Salary का 20% निकालना आसान है। लेकिन practical planning actual cash flow से शुरू होती है। एक simple formula इस्तेमाल करें:
Investment Capacity = In-hand Salary − Essential Expenses − Minimum Cash Buffer − Near-term Obligations
मान लीजिए salary ₹50,000 है, essential expenses ₹24,000 हैं, irregular/annual expenses के लिए ₹3,000 monthly provision रखते हैं और ₹6,000 flexible cash buffer चाहते हैं। तब:
₹50,000 − ₹24,000 − ₹3,000 − ₹6,000 = ₹17,000
₹17,000 आपकी theoretical investable capacity है। लेकिन इसका मतलब यह नहीं कि पूरे ₹17,000 को equity SIP में डालना चाहिए। अगर emergency fund अधूरा है, तो इसी surplus का हिस्सा safety bucket में जाना चाहिए। यही approach आपकी SIP को sustainable बनाती है।
तीन Ready-Made Plans: ₹50,000 Salary को कैसे बांटें?
Plan A: High Expenses वाला Employee
यह स्थिति तब हो सकती है जब rent ज्यादा हो, EMI चल रही हो, parents को support करना हो या शहर में living cost ऊंची हो। यहां लक्ष्य maximum investment नहीं, financial stability है।
| Bucket | Amount |
|---|---|
| Essentials + EMI | ₹28,000 |
| Emergency / Short-term Savings | ₹7,000 |
| Long-term Investment | ₹7,500 |
| Lifestyle | ₹5,000 |
| Insurance / Irregular | ₹2,500 |
कुल future allocation = ₹14,500, यानी salary का 29%। लेकिन इसमें पूरी राशि SIP नहीं है। ₹7,000 safety bucket में जा रहा है और ₹7,500 long-term investment में।
Plan B: Balanced Salaried Professional
| Bucket | Amount |
|---|---|
| Essential Expenses | ₹25,000 |
| Long-term Investment | ₹10,000 |
| Emergency / Short-term Savings | ₹7,500 |
| Lifestyle | ₹5,000 |
| Insurance / Irregular Costs | ₹2,500 |
यह model बहुत से beginners के लिए practical benchmark हो सकता है। यहां ₹10,000 monthly investment + ₹7,500 savings बनती है। Emergency fund target पूरा हो जाने के बाद ₹7,500 का पूरा हिस्सा SIP में डालना जरूरी नहीं है, लेकिन long-term goal मजबूत हो तो उसका एक हिस्सा investment में shift किया जा सकता है।
Plan C: Low Expenses और High Saving Capacity
| Bucket | Amount |
|---|---|
| Essentials | ₹20,000 |
| Long-term Investment | ₹15,000 |
| Emergency / Short-term Savings | ₹7,500 |
| Lifestyle | ₹5,000 |
| Insurance / Miscellaneous | ₹2,500 |
यह plan family के साथ रहने, low rent या strong cash flow जैसी situations में possible हो सकता है। लेकिन केवल इसलिए ₹15,000 SIP मत चुनिए क्योंकि यह salary का 30% है। अगर अगले छह महीनों में job change, relocation, marriage या बड़ा purchase expected है, तो liquidity की जरूरत पहले हो सकती है।
Emergency Fund पहले कितना बनाना चाहिए?
Emergency fund का purpose return कमाना नहीं, बल्कि unexpected expense या income disruption के समय आपको मजबूरी में investment बेचने या महंगा loan लेने से बचाना है। SEBI की financial education material भी emergency fund को personal financial planning का हिस्सा बताती है।
मान लीजिए आपके essential monthly expenses ₹25,000 हैं। 4 months reserve का simple target होगा:
₹25,000 × 4 = ₹1,00,000
अगर आप 6 months का reserve रखना चाहते हैं:
₹25,000 × 6 = ₹1,50,000
यह कोई universal legal rule नहीं है। सही emergency target आपकी job stability, dependents, insurance, debt और income visibility पर निर्भर करता है। Single-income household या irregular income में ज्यादा buffer useful हो सकता है।
Emergency fund की detailed planning के लिए Emergency Fund कितना होना चाहिए? guide देखें।
₹50,000 Salary पर कितना Invest करें: एक Practical Range
| Investment Rate | Monthly Investment | किस स्थिति में? |
|---|---|---|
| 10% | ₹5,000 | High expenses, debt या शुरुआती stage |
| 15% | ₹7,500 | Conservative start |
| 20% | ₹10,000 | Balanced benchmark |
| 25% | ₹12,500 | Healthy surplus और manageable expenses |
| 30% | ₹15,000 | Low expenses और stronger cash flow |
| 35%+ | ₹17,500+ | Only with strong savings capacity and clear goals |
इस table को “right answer” नहीं बल्कि decision range समझें। उदाहरण के लिए ₹12,500 invest करने के बाद अगर आपको month-end credit card balance carry करना पड़ रहा है, तो आपकी वास्तविक investment rate जरूरत से ज्यादा aggressive है। इसके उलट अगर ₹50,000 salary में आपकी essential cost ₹20,000 है और emergency fund पहले से मजबूत है, तो ₹10,000 पर रुकना भी unnecessarily conservative हो सकता है।
₹10,000 SIP से कितना Corpus बन सकता है?
अब एक mathematical illustration देखते हैं। मान लेते हैं कि आप ₹10,000 monthly SIP करते हैं। नीचे 8%, 10% और 12% annualized return scenarios दिए गए हैं। ये assumptions हैं, forecast या guarantee नहीं। Actual mutual fund returns अलग हो सकते हैं और बीच के वर्षों में negative भी हो सकते हैं।
| Monthly SIP | 10 साल @8% | 10 साल @10% | 10 साल @12% |
|---|---|---|---|
| ₹5,000 | ₹9.21 लाख | ₹10.33 लाख | ₹11.62 लाख |
| ₹7,500 | ₹13.81 लाख | ₹15.49 लाख | ₹17.43 लाख |
| ₹10,000 | ₹18.42 लाख | ₹20.66 लाख | ₹23.23 लाख |
| ₹12,500 | ₹23.02 लाख | ₹25.82 लाख | ₹29.04 लाख |
| ₹15,000 | ₹27.62 लाख | ₹30.98 लाख | ₹34.85 लाख |
Calculation method: monthly SIP future-value formula, monthly compounding approximation. Figures rounded. Returns are illustrative assumptions only and are not guaranteed.
15 और 20 साल में compounding का असर और स्पष्ट हो जाता है:
| Monthly SIP | 15 साल @10% | 15 साल @12% | 20 साल @10% | 20 साल @12% |
|---|---|---|---|---|
| ₹5,000 | ₹20.90 लाख | ₹25.23 लाख | ₹38.28 लाख | ₹49.96 लाख |
| ₹7,500 | ₹31.34 लाख | ₹37.84 लाख | ₹57.43 लाख | ₹74.94 लाख |
| ₹10,000 | ₹41.79 लाख | ₹50.46 लाख | ₹76.57 लाख | ₹99.91 लाख |
| ₹12,500 | ₹52.24 लाख | ₹63.07 लाख | ₹95.71 लाख | ₹1.25 करोड़ |
| ₹15,000 | ₹62.69 लाख | ₹75.69 लाख | ₹1.15 करोड़ | ₹1.50 करोड़ |
यहां सबसे महत्वपूर्ण lesson return percentage नहीं बल्कि time + consistency + contribution size है। सिर्फ 12% मान लेने से wealth नहीं बनती; actual outcome market performance, costs, taxes, asset allocation और investor behaviour पर निर्भर करेगा।
Step-Up SIP: ₹50,000 Salary वाले व्यक्ति के लिए सबसे Powerful Habit
मान लीजिए आप आज ₹10,000 SIP शुरू करते हैं और हर साल उसे 10% बढ़ाते हैं। तब monthly amount ऐसे बढ़ेगा: Year 1 ₹10,000, Year 2 ₹11,000, Year 3 ₹12,100, Year 4 ₹13,310 और इसी तरह आगे। इससे investment amount आपकी income growth के साथ बढ़ सकती है।
Illustration के तौर पर 15 साल तक ₹10,000 से शुरू करके हर साल 10% step-up करने पर total contribution लगभग ₹38.13 लाख होगा। 10% annualized return की mathematical assumption पर corpus लगभग ₹4.00 करोड़ और 12% assumption पर लगभग ₹4.51 करोड़ बनता है। ये केवल illustrations हैं, guaranteed outcomes नहीं।
Step-up का बड़ा फायदा यह है कि शुरुआत में आपको बहुत बड़ा sacrifice करने की जरूरत नहीं पड़ती। Salary बढ़ने के साथ investment burden धीरे-धीरे absorb होता है।
₹50,000 Salary पर पैसे कहां Invest करें?
एक ही investment हर व्यक्ति के लिए सही नहीं है। पहले goal और time horizon तय करें, फिर product चुनें। SEBI investor education material financial planning को goals, risk profile और periodic review से जोड़ता है। Mutual fund schemes पर SEBI Riskometer risk level समझने का एक जरूरी reference है।
| Goal | General approach | क्या ध्यान रखें |
|---|---|---|
| Emergency Fund | High-liquidity savings options | Access और stability priority |
| 0–3 साल का goal | Capital preservation oriented options | Short-term market risk से सावधान |
| 5+ साल wealth creation | Diversified equity-oriented investments may have a role | Market volatility सहने की capacity जरूरी |
| Retirement | Long-term diversified portfolio + retirement products as suitable | Inflation और time horizon देखें |
Mutual Fund SIP
Monthly salary से disciplined investing के लिए SIP practical method हो सकती है। AMFI के अनुसार SIP mutual fund scheme में fixed amount को periodic intervals पर invest करने की methodology है और इसे disciplined investing तथा rupee cost averaging के लिए इस्तेमाल किया जा सकता है। लेकिन SIP खुद कोई separate asset class नहीं है; risk underlying mutual fund पर निर्भर करता है।
Beginner-friendly route में broadly diversified schemes को समझना कई बार multiple overlapping funds लेने से बेहतर हो सकता है। Fund चुनने से पहले objective, benchmark, portfolio, expense ratio, riskometer और investment horizon देखें। आपके site पर Index Fund vs Mutual Fund की practical comparison इस topic को आगे समझने में मदद कर सकती है।
EPF, PPF और NPS की भूमिका
अगर आप salaried employee हैं तो EPF पहले से salary structure का हिस्सा हो सकता है। इसे ignore करके पूरा retirement plan केवल SIP पर बनाना जरूरी नहीं है। PPF और NPS जैसे long-term retirement-oriented instruments की suitability आपके goal, liquidity needs और applicable tax rules पर निर्भर करती है। NPS में subscribers asset classes और investment choices के अनुसार allocation चुन सकते हैं, लेकिन इसकी structure retirement-focused है और liquidity mutual fund SIP जैसी नहीं समझनी चाहिए।
यानी ₹10,000 “investment budget” का मतलब जरूरी नहीं कि पूरा ₹10,000 एक ही mutual fund में जाए। पहले देखें कि EPF/NPS जैसी existing retirement contributions कितनी हैं और आपका target corpus कितना है।
Insurance को Investment समझने की गलती मत करें
₹50,000 salary वाले household में insurance premium को investment return के हिसाब से judge करना सही framework नहीं है। Health insurance और जरूरत के अनुसार life insurance का काम financial protection है, wealth creation नहीं। Employer health cover है तो उसके limits, waiting periods, exclusions और job change के impact को समझना भी जरूरी है।
Investment के लिए बची हुई रकम को पूरी तरह insurance products में shift करने से पहले यह देखें कि आप protection खरीद रहे हैं या wealth-building asset। दोनों jobs अलग हैं।
High-Cost Debt है तो पहले क्या करें?
मान लीजिए आपके पास credit card का revolving balance है और हर महीने interest लग रहा है। दूसरी तरफ आप ₹15,000 SIP कर रहे हैं। ऐसे case में केवल SIP amount देखकर आप खुद को “high saver” समझ सकते हैं, जबकि expensive debt आपकी net wealth को खा रहा है।
इसलिए priority framework रखें: minimum debt obligations + basic emergency reserve + protection + high-cost debt review + goal-based investing। हर व्यक्ति के लिए order बिल्कुल identical नहीं होगा, लेकिन expensive unsecured debt को ignore करना उचित नहीं है।
₹50,000 Salary वालों की 7 Common Money Mistakes
- सिर्फ salary percentage देखकर SIP तय करना: cash flow ज्यादा महत्वपूर्ण है।
- Emergency fund को investment समझना: emergency money को अलग और accessible रखें।
- एक साथ बहुत सारे mutual funds लेना: छोटी SIP को 5–6 funds में बांटने से overlap बढ़ सकता है।
- Short-term goal का पैसा equity में डालना: goal के समय market correction आ सकता है।
- Salary hike के साथ पूरा lifestyle inflate कर देना: investment capacity वहीं की वहीं रह जाती है।
- Investment को tax saving के नाम पर blind तरीके से चुनना: पहले product का purpose और current tax treatment समझें।
- Market गिरते ही SIP बंद कर देना: long-term plan को short-term volatility के आधार पर बार-बार बदलना behaviour risk पैदा कर सकता है।
Real-World Scenario: 25 साल का Single Employee
मान लीजिए in-hand salary ₹50,000 है, rent ₹10,000 है, EMI नहीं है, family के साथ occasional support है और emergency fund सिर्फ ₹30,000 है। यहां ₹15,000 SIP तुरंत शुरू करने के बजाय ₹7,500 SIP + ₹7,500 emergency savings ज्यादा balanced हो सकती है। Emergency target बनने के बाद investment amount बढ़ाया जा सकता है।
Real-World Scenario: 32 साल का Married Employee
अब rent ₹15,000, groceries ₹8,000, travel ₹4,000, family support ₹5,000 और insurance/other costs ₹4,000 हैं। Essential + committed spending तेजी से बढ़ता है। यहां ₹20,000 SIP “best” नहीं है। ₹7,500–₹10,000 long-term investment और बाकी surplus को emergency, near-term goals और cash buffer में रखना अधिक practical हो सकता है।
Real-World Scenario: अगले 3 साल में घर की Down Payment
यहां सबसे बड़ी गलती retirement SIP और house down payment को एक ही basket में डालना होगी। अगर आपको 3 साल में निश्चित amount चाहिए, तो goal horizon के कारण capital volatility को ध्यान में रखना होगा। Market-linked investment में पैसा लगाने से पहले यह सोचें कि purchase date के समय market गिरा तो क्या होगा।
अगर आपका बड़ा लक्ष्य घर है, तो 50-30-20 budgeting guide से cash-flow structure देखें और घर खरीदना या किराये पर रहना जैसे decision को investment plan से अलग evaluate करें।
₹50,000 Salary पर Savings Rate कितना होना चाहिए?
एक useful starting target total future allocation का 20%–30% हो सकता है। यहां “future allocation” में emergency savings, short-term goals और long-term investments सभी शामिल हो सकते हैं। Emergency fund पूरा होने के बाद यह ratio बदल सकता है और long-term investment share बढ़ सकता है।
उदाहरण के लिए:
| Future Allocation | Amount | Interpretation |
|---|---|---|
| 20% | ₹10,000 | Minimum practical starting point for many situations |
| 25% | ₹12,500 | Healthy level when expenses are controlled |
| 30% | ₹15,000 | Strong savings/investing capacity |
| 35% | ₹17,500 | Possible with low expenses and strong discipline |
| 40% | ₹20,000 | Aggressive; needs clear priorities and cash buffer |
एक Simple Money System बनाइए
₹50,000 salary को manage करने का सबसे आसान तरीका हर खर्च को याद रखना नहीं, बल्कि salary आते ही money को अलग jobs देना है। उदाहरण:
- Salary credit होते ही long-term SIP auto-debit रखें।
- Emergency/short-term saving को अलग account या clearly defined bucket में भेजें।
- Essential खर्च के लिए fixed amount रखें।
- Lifestyle spending का monthly cap तय करें।
- Annual और irregular expenses के लिए monthly provision बनाएं।
- Salary increment पर SIP को automatic step-up करें।
- हर 6–12 महीने goals, expenses और risk tolerance review करें।
₹50,000 Salary पर 60-Second Decision Framework
- क्या emergency fund बना है? नहीं है तो पहले safety bucket बढ़ाएं।
- क्या high-cost debt है? है तो debt cost को plan में शामिल करें।
- क्या अगले 3 साल में बड़ा goal है? उसका पैसा long-term equity bucket से अलग रखें।
- क्या monthly surplus stable है? नहीं है तो lower SIP चुनें।
- क्या salary बढ़ने वाली है? Step-Up SIP plan पहले से तय करें।
- क्या आपके existing EPF/NPS investments हैं? उन्हें total retirement plan में count करें।
Frequently Asked Questions
1. ₹50,000 salary में हर महीने कितना save करना चाहिए?
एक practical starting point salary का 20%–30% total future allocation हो सकता है, यानी ₹10,000–₹15,000। लेकिन इसमें emergency savings और long-term investment दोनों शामिल हो सकते हैं। आपकी rent, EMI, dependents और goals के अनुसार amount बदल सकता है।
2. ₹50,000 salary पर ₹10,000 SIP पर्याप्त है?
कई beginners के लिए यह practical benchmark है। लेकिन पर्याप्त है या नहीं, यह आपके retirement target, existing EPF/NPS, age, goals और future contributions पर निर्भर करेगा।
3. ₹50,000 salary में ₹20,000 invest करना सही है?
तभी जब essentials, emergency fund, insurance और short-term goals संभले हुए हों और investment के बाद cash-flow stress न हो। सिर्फ percentage देखकर ₹20,000 तय करना सही तरीका नहीं है।
4. SIP और saving दोनों कैसे manage करें?
Salary आते ही दो buckets बनाएं: safety/short-term और long-term investment। उदाहरण के लिए ₹7,500 emergency savings + ₹10,000 SIP। Emergency target बनने के बाद saving amount का हिस्सा long-term investment में shift किया जा सकता है।
5. क्या पहले emergency fund बनाना चाहिए या SIP शुरू करनी चाहिए?
Basic emergency cushion बहुत जरूरी है। कई लोग पूरी SIP रोकने के बजाय छोटी SIP के साथ emergency fund build करते हैं। सही mix आपकी job stability और financial obligations पर निर्भर करता है।
6. ₹50,000 salary पर कितने mutual funds लेने चाहिए?
Salary के आधार पर कोई fixed number नहीं है। Goals, asset allocation और overlap ज्यादा महत्वपूर्ण हैं। छोटी SIP को कई overlapping schemes में बांटने की जरूरत नहीं है।
7. Salary बढ़ने पर investment कितना बढ़ाएं?
Annual increment का एक हिस्सा Step-Up SIP में जोड़ना practical तरीका है। 10% annual step-up एक example है, mandatory rule नहीं। आपकी नई responsibilities बढ़ी हों तो increase कम भी रखा जा सकता है।
8. क्या ₹50,000 salary पर घर भी खरीद सकते हैं और invest भी?
संभव है, लेकिन goals को अलग buckets में plan करना होगा। Down payment, transaction costs, EMI affordability और emergency reserve को retirement SIP के साथ एक ही calculation में mix नहीं करना चाहिए।
आज से क्या शुरू करें?
- अपनी exact in-hand salary लिखें।
- पिछले 3 महीनों का average essential खर्च निकालें।
- EMI और high-cost debt की पूरी list बनाएं।
- Emergency fund target तय करें।
- ₹7,500, ₹10,000 या ₹12,500 में से एक sustainable starting investment amount चुनें।
- Short-term goals की separate monthly saving तय करें।
- Insurance coverage और employer benefits review करें।
- SIP को salary cycle के साथ automate करें।
- हर increment पर Step-Up percentage तय करें।
- हर साल कम से कम एक बार complete financial review करें।
आखिरी बात: ₹50,000 Salary में Perfect Number नहीं, सही System चाहिए
₹50,000 Salary में कितना Save और Invest करें? इसका एक universal जवाब ₹10,000, ₹15,000 या ₹20,000 नहीं है। असली answer आपकी financial capacity है। अगर खर्च ज्यादा हैं तो ₹7,500 investment भी अच्छी शुरुआत हो सकती है। अगर expenses कम हैं और emergency fund मजबूत है तो ₹15,000 या उससे ज्यादा invest करना संभव हो सकता है।
सबसे मजबूत plan वह है जिसमें तीन चीजें साथ चलें: आज की financial stability, कल के goals और आपकी बदलती income। पहले cash flow को व्यवस्थित करें, फिर emergency reserve बनाएं, उसके बाद goal-based investing शुरू करें और salary बढ़ने पर SIP को step-up करते रहें।
आपका पहला लक्ष्य किसी दूसरे व्यक्ति की SIP को beat करना नहीं है। आपका लक्ष्य ऐसा money system बनाना है जिसे आप कई सालों तक निभा सकें। वही consistency समय के साथ बड़ी financial advantage बन सकती है।
Related reading: ₹50,000 Salary पर कितना SIP करें? | उम्र और Salary के हिसाब से Asset Allocation | ₹1 Lakh Salary Investment Plan
Financial Disclaimer
यह लेख केवल educational और informational उद्देश्य के लिए है और किसी व्यक्ति के लिए personalized financial, investment, tax या insurance advice नहीं है। Savings और investment amounts examples और assumptions पर आधारित हैं। Mutual fund investments market risk के अधीन हैं; किसी भी return की guarantee नहीं दी गई है। SIP corpus calculations केवल mathematical illustrations हैं और actual returns अलग हो सकते हैं। किसी investment product को चुनने से पहले उसके risk, costs, liquidity, taxation, applicable lock-in और official scheme documents को समझें। व्यक्तिगत सलाह की आवश्यकता हो तो SEBI-registered Investment Adviser और tax-related मामलों में qualified tax professional से परामर्श लें।