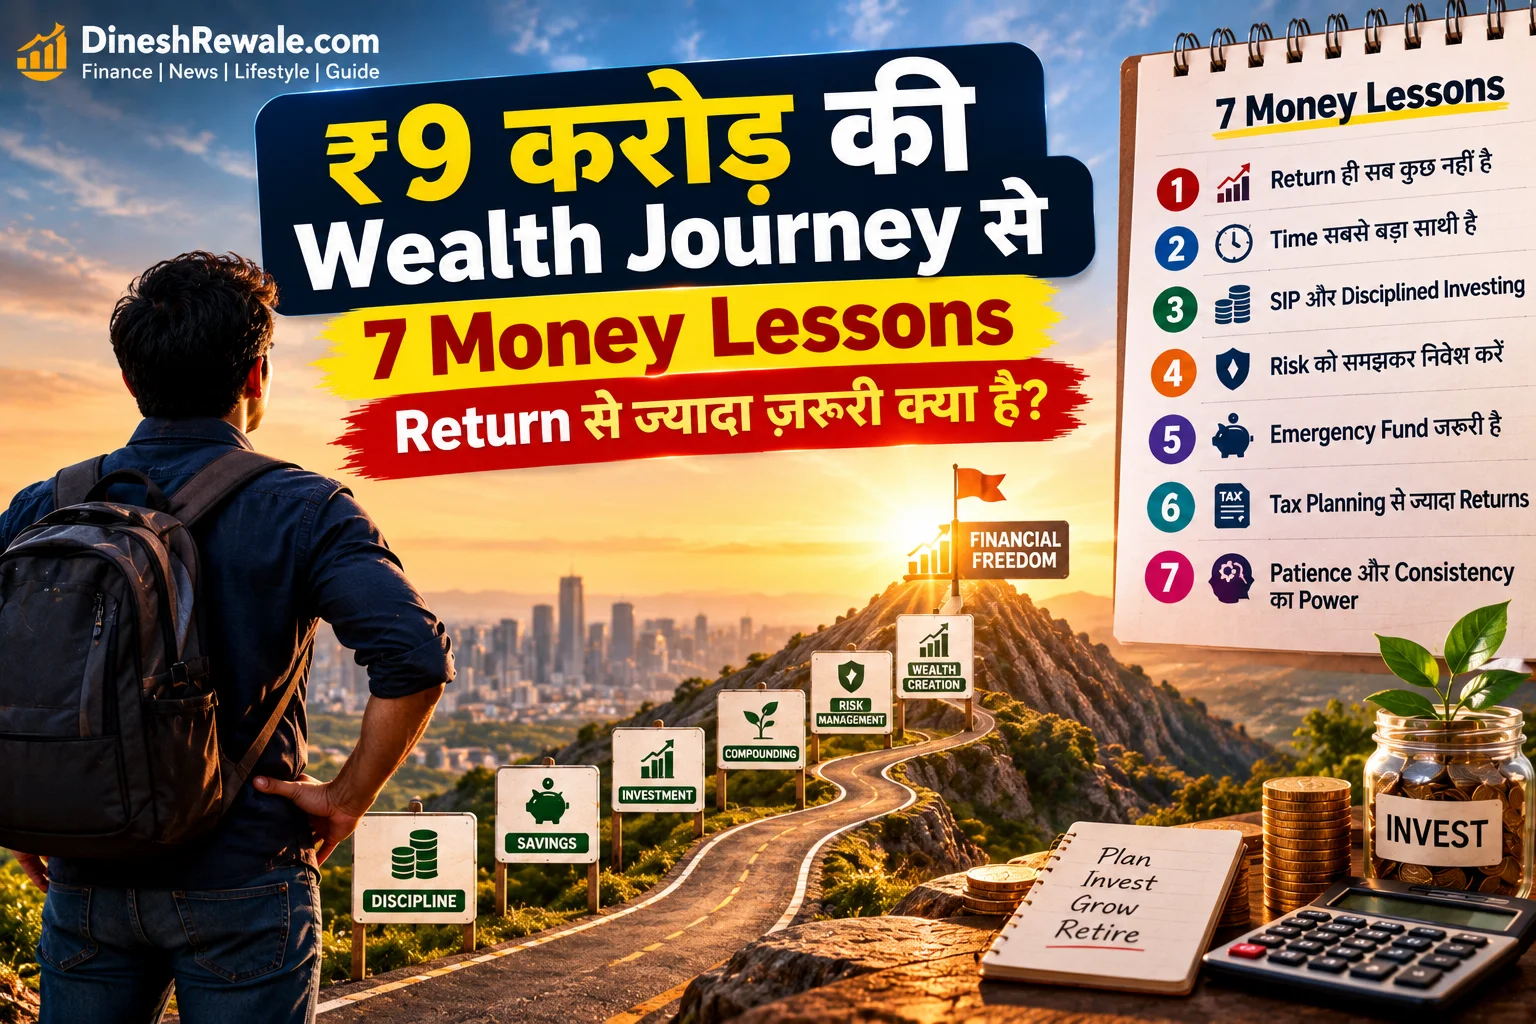
₹9 करोड़ Wealth Journey से 7 Money Lessons: असली सीख
₹9 करोड़ की wealth journey सुनकर सबसे पहले ध्यान return या किसी “best mutual fund” पर जाता है। लेकिन Pune के 32 वर्षीय IT professional Sudhir Dandotiya की reported journey की बड़ी सीख कुछ और है: income बढ़ाना, खर्च को control करना, नियमित investing और समय के साथ assets बनाना कई बार fund selection से…
₹9 करोड़ की wealth journey सुनकर सबसे पहले ध्यान return या किसी “best mutual fund” पर जाता है। लेकिन Pune के 32 वर्षीय IT professional Sudhir Dandotiya की reported journey की बड़ी सीख कुछ और है: income बढ़ाना, खर्च को control करना, नियमित investing और समय के साथ assets बनाना कई बार fund selection से ज्यादा महत्वपूर्ण हो सकता है।
Financial Express की October 2026 report के अनुसार Dandotiya ने लगभग ₹9 करोड़ का gross asset pool बनाया है। इसमें करीब ₹4.3 करोड़ financial assets और लगभग ₹4.5–4.7 करोड़ की Pune property शामिल है। Property पर home loan outstanding होने की वजह से ₹9 करोड़ को सीधे net worth नहीं मानना चाहिए। उनकी mutual-fund portfolio value लगभग ₹2.56 करोड़ बताई गई है और वे करीब ₹1.5 लाख monthly SIP करते हैं। ये सभी figures reported snapshot हैं, कोई guaranteed wealth formula नहीं।
In Short
- Wealth salary से नहीं, surplus को assets में बदलने से बनती है।
- Salary बढ़ने पर SIP या investment contribution बढ़ाना long-term corpus को तेजी से बदल सकता है।
- First-Deduct approach यानी पहले saving/investing और फिर spending, lifestyle inflation को control करने में मदद कर सकता है।
- Market गिरने पर panic करके long-term plan तोड़ना जरूरी नहीं है, लेकिन risk profile की review जरूरी है।
- Diversification का मतलब सिर्फ ज्यादा funds रखना नहीं, बल्कि overall portfolio risk को समझना है।
- ₹9 करोड़ किसी दूसरे व्यक्ति की journey है। अपना target income, expenses, goals और liabilities से तय करें।
₹9 करोड़ की इस Wealth Journey में असल में क्या हुआ?
Reported details के अनुसार Sudhir Dandotiya ने 2017 में लगभग ₹4.5 लाख annual package से career शुरू किया और 2026 तक उनकी annual income करीब ₹52 लाख तक पहुंची। Income growth के साथ उन्होंने investments को भी बढ़ाया। वे करीब ₹1.5 लाख monthly mutual-fund SIP करते हैं और home loan EMI लगभग ₹1.61 लाख बताई गई है।
उनकी wealth का बड़ा हिस्सा सिर्फ mutual funds से नहीं आया। Financial assets, mutual funds, property, FD, gold और दूसरे investments मिलाकर gross asset pool तैयार हुआ। यही distinction महत्वपूर्ण है: asset value और net worth एक ही चीज नहीं हैं। अगर किसी property या investment पर loan outstanding है, तो liability घटाने के बाद actual net worth कम हो सकती है।
| Reported figure | Approx amount | इसका मतलब |
|---|---|---|
| Gross assets | लगभग ₹9 करोड़ | कुल reported assets, liabilities घटाने से पहले |
| Financial assets | लगभग ₹4.3 करोड़ | Financial investments का reported value |
| Mutual funds | लगभग ₹2.56 करोड़ | Reported MF portfolio value |
| Pune property | ₹4.5–4.7 करोड़ | Property value, loan liability अलग से देखें |
| Monthly SIP | लगभग ₹1.5 लाख | Regular monthly investing discipline |
इन numbers को किसी individual investor के लिए target या benchmark न मानें। Wealth creation की speed salary growth, starting capital, property appreciation, liabilities, saving rate और market returns के combination से तय होती है।
Lesson 1: Income Growth को Investment Growth से जोड़ें
इस journey की सबसे practical सीख है कि salary बढ़ने पर investment भी बढ़ना चाहिए। अगर income ₹10 लाख से ₹15 लाख हो गई लेकिन पूरा extra cash lifestyle में चला गया, तो wealth-building की गति बहुत कम बदलती है।
इसके उलट, salary hike का एक fixed हिस्सा SIP, EPF, NPS या अन्य long-term assets में redirect किया जाए तो contribution तेजी से बढ़ सकता है। इसे annual step-up investing भी कह सकते हैं।
उदाहरण के लिए ₹20,000 monthly SIP से शुरुआत करने वाला investor हर साल 10% contribution बढ़ाता है तो कुछ वर्षों बाद उसका monthly investment शुरुआती amount से काफी ज्यादा हो जाता है। यहाँ return assumption से पहले contribution growth पर ध्यान देना जरूरी है।
Lesson 2: “Best Fund” से ज्यादा जरूरी Consistency है
किसी mutual fund का पिछले 3 या 5 साल में top performer होना भविष्य में भी वही return देगा, इसकी guarantee नहीं है। SEBI के standard risk disclosures भी बताते हैं कि mutual-fund investments market risk के अधीन हैं और past performance future performance का संकेत नहीं है।
इसका मतलब fund selection महत्वहीन नहीं है। सही category, reasonable cost, suitable risk level और portfolio quality देखनी चाहिए। लेकिन हर साल fund बदलना, returns के पीछे भागना या ranking देखकर portfolio churn करना consistency को नुकसान पहुंचा सकता है।
AMFI के अनुसार SIP fixed amount को नियमित intervals पर निवेश करने की method है और यह disciplined investing तथा rupee-cost averaging में मदद कर सकती है। लेकिन SIP profit की guarantee नहीं देता और गिरते market में loss से protect भी नहीं करता।
Direct vs Regular Mutual Fund और Expense Ratio क्यों महत्वपूर्ण है? जैसी guides से cost और plan selection को बेहतर समझा जा सकता है।
Lesson 3: Lifestyle Inflation को Control करें
Income बढ़ने के साथ खर्च बढ़ना सामान्य है, लेकिन हर salary hike को new EMI, expensive car, frequent upgrades और unnecessary subscriptions में बदल देना long-term wealth creation को slow कर सकता है।
एक practical rule है: हर income increase का पहले से तय हिस्सा wealth-building में जाए। बाकी रकम से lifestyle improve करें। इससे saving एक leftover activity नहीं रहती, बल्कि financial system का हिस्सा बन जाती है।
इस approach का फायदा यह है कि income बढ़ने के साथ investment amount भी बढ़ता है और lifestyle अचानक इतना expensive नहीं होता कि future saving मुश्किल हो जाए।
Lesson 4: Market गिरने पर Plan को तुरंत मत तोड़ें
Long-term equity investing में market corrections और bear phases आ सकते हैं। ऐसे समय SIP बंद करके या panic selling करके plan बदलना future compounding को नुकसान पहुंचा सकता है।
लेकिन इसका मतलब यह नहीं कि हर situation में investment continue करना चाहिए। अगर goal बदल गया है, emergency cash की जरूरत है या portfolio risk आपकी capacity से ज्यादा हो गया है, तो review जरूरी है। सही सवाल यह है: क्या market गिरा है, या मेरी financial plan की वजह बदल गई है?
AMFI भी SIP को disciplined investing method बताता है, लेकिन यह स्पष्ट करता है कि rupee-cost averaging profit की guarantee नहीं देता और declining market में losses से protect नहीं करता।
Long-term equity basics के लिए Index Fund vs Mutual Fund guide भी पढ़ें।
Lesson 5: Diversification रखें, लेकिन Over-Diversification नहीं
Reported portfolio में mutual funds के साथ property, FD, gold और दूसरे assets भी शामिल हैं। इसका useful lesson यह है कि wealth सिर्फ एक asset class पर depend नहीं करनी चाहिए।
लेकिन diversification का मतलब 15-20 mutual funds खरीद लेना नहीं है। अगर कई funds लगभग वही stocks या sectors hold करते हैं, तो fund count ज्यादा होते हुए भी actual diversification कम हो सकता है।
Portfolio को broadly growth assets, stable/defensive assets और liquidity bucket में सोचें। Equity long-term growth दे सकती है, debt/FD stability दे सकते हैं और emergency fund short-term needs के लिए अलग रखा जा सकता है। Exact allocation age, goals और risk capacity पर depend करेगा।
Gold allocation समझने के लिए Gold Investment: ETF vs SGB vs Physical Gold और emergency liquidity के लिए Emergency Fund guide देखें।
Lesson 6: Wealth और Income एक चीज नहीं हैं
High salary wealth की शुरुआत हो सकती है, लेकिन wealth खुद नहीं है। Salary बंद होने के बाद भी अगर assets income generate कर सकते हैं या value retain कर सकते हैं, तभी financial independence stronger होती है।
इसीलिए monthly income को तीन हिस्सों में सोच सकते हैं: living expenses, debt obligations और asset building। जब asset-building contribution समय के साथ बढ़ता है, तो earned income का एक हिस्सा future financial freedom के लिए काम करने लगता है।
इस framework को जल्दी शुरू करना ज्यादा आसान होता है। 30 साल की उम्र में Financial Planning और Asset Allocation by Age & Salary जैसी guides इस planning को structure करने में मदद करती हैं।
Lesson 7: Time सबसे powerful advantage है
Compounding को समय चाहिए। ₹1 लाख का investment और ₹1 लाख की monthly income एक जैसी चीज नहीं हैं, लेकिन long time horizon regular contributions को meaningful corpus में बदल सकता है।
यही कारण है कि wealth journey को “मैं अगले साल करोड़पति कैसे बनूं?” के बजाय “मैं अगले 10-20 साल तक assets कैसे build करता रहूं?” के सवाल से देखना ज्यादा practical है।
Early start का दूसरा फायदा यह है कि investor छोटे contribution से शुरुआत करके salary growth के साथ amount बढ़ा सकता है। समय के साथ contribution और compounding दोनों काम करते हैं।
First-Deduct Strategy क्या है?
इस wealth story की एक महत्वपूर्ण behavioral lesson first-deduct approach है। इसका simple meaning है: salary आने के बाद पहले investment/saving का पैसा अलग करें और उसके बाद बाकी रकम खर्च करें।
मान लीजिए monthly income ₹1 लाख है। अगर investor पहले ₹25,000 invest कर देता है और ₹75,000 को spending budget मानता है, तो investment automatic priority बन जाती है। लेकिन पहले ₹1 लाख spend करके महीने के अंत में बची रकम invest करने की कोशिश की जाए तो contribution inconsistent हो सकता है।
यह कोई investment product नहीं, बल्कि cash-flow habit है। इसे SIP, EPF, NPS या recurring transfer के साथ automate किया जा सकता है।
क्या ₹9 करोड़ का target हर Investor के लिए realistic है?
नहीं। किसी successful wealth journey को देखकर उसी number को अपना target बना लेना सही नहीं है। Dandotiya की journey में strong salary growth, property ownership, monthly SIP और disciplined spending जैसे कई factors साथ आए हैं। दूसरे investor की income, family responsibilities, loan burden और starting age अलग हो सकती है।
अपना target निकालने के लिए आज के monthly expenses, retirement age, desired lifestyle, inflation, existing assets, liabilities और expected investment horizon को साथ में रखें।
₹9 करोड़ Asset और ₹9 करोड़ Net Worth में फर्क
यह distinction बहुत जरूरी है। अगर किसी व्यक्ति के assets ₹9 करोड़ हैं लेकिन property या दूसरे assets पर ₹2 करोड़ की liabilities हैं, तो net worth ₹9 करोड़ नहीं होगी। Basic formula है:
Net Worth = Total Assets − Total Liabilities
Reported story में home loan outstanding होने के कारण gross asset figure को actual net worth समझना misleading हो सकता है। Personal finance articles पढ़ते समय यह distinction हमेशा check करें।
₹9 करोड़ जैसी wealth journey से क्या copy करें और क्या नहीं?
| Copy करें | Blindly copy न करें |
|---|---|
| Regular investing | किसी व्यक्ति का exact mutual-fund portfolio |
| Income growth का हिस्सा invest करना | किसी और का SIP amount |
| Lifestyle inflation control | अपनी capacity से ज्यादा home loan लेना |
| Long-term mindset | Past returns को future guarantee मानना |
| Diversification | सिर्फ fund count बढ़ाते रहना |
₹9 करोड़ Journey से अपने लिए 7-Point Money Checklist
- Income बढ़ाओ: Skills, career growth और additional income पर focus करें।
- Pay-yourself-first: Salary आते ही investment automate करें।
- Annual step-up करें: Income बढ़ने पर investment contribution भी बढ़ाएं।
- Emergency fund रखें: Long-term investments को short-term जरूरतों के लिए बार-बार न तोड़ें।
- Debt control करें: Home loan और अन्य EMIs को overall cash flow में fit करें।
- Portfolio review करें: Risk, asset allocation, costs और overlap check करें।
- Target revise करें: हर साल assets, expenses और retirement goal के हिसाब से target update करें।
एक Simple Wealth-Building Framework
| Stage | Primary focus | Practical action |
|---|---|---|
| 1. Foundation | Cash flow stability | Budget + emergency fund + insurance review |
| 2. Accumulation | Regular investing | SIP/EPF/NPS and suitable assets |
| 3. Acceleration | Income + step-up | Raise investment when income rises |
| 4. Protection | Risk management | Diversification + debt control + liquidity |
| 5. Review | Goal alignment | Annual rebalance and goal check |
FAQs: ₹9 करोड़ Wealth Journey
Sudhir Dandotiya ने ₹9 करोड़ कैसे बनाए?
Published reports के अनुसार उनकी wealth journey में salary growth, regular ₹1.5 लाख monthly SIP, property ownership, disciplined savings और lifestyle inflation control जैसे factors शामिल हैं। यह reported individual case है, investment guarantee नहीं।
क्या ₹9 करोड़ उनकी net worth है?
जरूरी नहीं। Reported ₹9 करोड़ gross assets का figure है और property पर home loan outstanding होने की वजह से actual net worth इससे कम हो सकती है।
क्या ₹1.5 लाख SIP करने से कोई भी ₹9 करोड़ बना सकता है?
नहीं। Final corpus investment duration, annual step-up, returns, starting corpus और market performance पर depend करता है। Fixed SIP amount से fixed future corpus की guarantee नहीं होती।
क्या सबसे अच्छा mutual fund चुनना wealth बनाने का सबसे जरूरी तरीका है?
नहीं। Fund selection important है, लेकिन consistency, savings rate, contribution growth, diversification और time horizon भी बहुत महत्वपूर्ण हैं। Past performance future return की guarantee नहीं है।
First-Deduct method क्या है?
इसका अर्थ है income मिलने के तुरंत बाद saving या investment का हिस्सा अलग करना और बाकी रकम को spending budget मानना। इससे investing को regular habit बनाना आसान हो सकता है।
क्या market crash में SIP बंद कर देनी चाहिए?
सिर्फ market गिरने के कारण SIP बंद करना जरूरी नहीं है। लेकिन goal, risk tolerance, emergency needs और asset allocation बदल गई हो तो portfolio review करना चाहिए।
क्या diversification के लिए कई mutual funds रखने चाहिए?
जरूरी नहीं। Funds की संख्या से ज्यादा महत्वपूर्ण underlying portfolio, category, overlap और overall asset allocation है।
क्या ₹9 करोड़ target को retirement target बनाया जा सकता है?
बिना personal calculations के नहीं। Retirement target future monthly expenses, inflation, retirement age, life expectancy, existing assets और liabilities के आधार पर निकालना चाहिए।
और पढ़ें
Mutual Fund Expense Ratio क्यों महत्वपूर्ण है?
30 साल की उम्र में Financial Planning
Asset Allocation by Age & Salary
Emergency Fund: Savings Account, FD या Liquid Fund?
उपयोगी संदर्भ
Financial Express: How a 32-year-old Pune man made Rs 9 Cr without “best” mutual funds में reported wealth journey और figures देखें।
AMFI पर SIP, mutual-fund investing और investor education material देखें।
SEBI पर mutual-fund risk disclosures और investor-protection information देखें।
लेखक के बारे में
Dinesh Rewale personal finance, wealth-building और investment planning पर practical, reader-focused guides लिखते हैं। उनका उद्देश्य complex financial topics को आसान language, examples और useful comparisons के साथ समझाना है, ताकि readers informed financial decisions ले सकें।
Disclaimer
यह लेख एक reported financial journey से मिलने वाली general money lessons को समझाने के लिए है। किसी व्यक्ति के assets, returns, SIP amount या investment choices को copy करना जरूरी नहीं है। Mutual funds और अन्य market-linked investments में risk होता है और past performance future returns की guarantee नहीं है। Investment decision अपनी income, goals, liabilities, time horizon और risk profile के अनुसार लें।