Net Worth क्या है? कैसे Calculate करें | Assets और Liabilities
बहुत से लोग अपनी financial health को salary, bank balance या investment portfolio देखकर समझने की कोशिश करते हैं। लेकिन इनमें से कोई एक संख्या पूरी तस्वीर नहीं बताती। आपकी salary अच्छी हो सकती है, फिर भी अगर आपके ऊपर बड़ा loan है तो आपकी वास्तविक financial position उतनी मजबूत नहीं हो सकती। दूसरी तरफ, कम salary वाला व्यक्ति लगातार saving और investing करके मजबूत net worth बना सकता है।
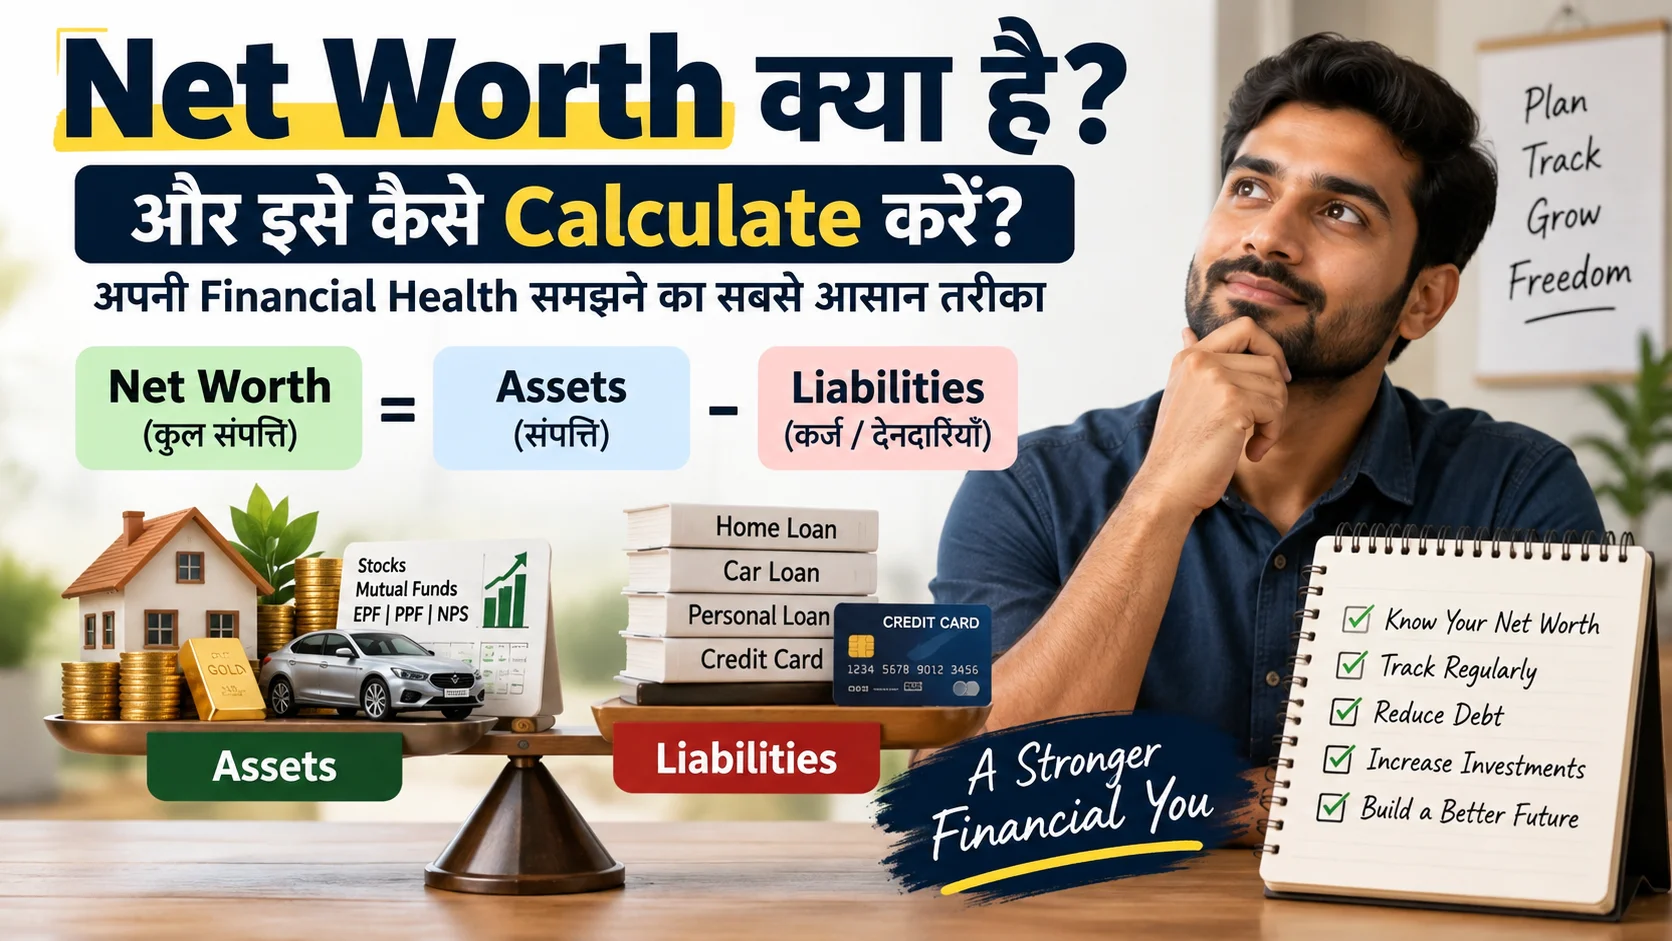
यहीं Net Worth काम आता है। आसान भाषा में, net worth बताता है कि आज की तारीख में आपने जो कुछ बनाया और जो कुछ आप पर बकाया है, दोनों को साथ देखने के बाद आपकी आर्थिक स्थिति कितनी मजबूत है। इसका basic formula बेहद सरल है:
Net Worth = Total Assets − Total Liabilities
लेकिन असली सवाल formula याद रखना नहीं है। असली काम यह तय करना है कि कौन-सी चीज asset है, उसका current value कितना माना जाए, कौन-सा debt liability है और self-use घर या car को किस तरह track किया जाए। यही वह जगह है जहां अक्सर गलतियां होती हैं।
इस guide में आप India-focused तरीके से net worth calculate करना सीखेंगे, realistic ₹ examples देखेंगे, liquid net worth और total net worth का फर्क समझेंगे, और एक simple annual tracking system भी बनाएंगे। SEBI Investor की official Net Worth Calculator भी assets और liabilities को इसी basic framework में जोड़कर net worth निकालती है।
Quick Answer: Net Worth क्या है?
- Net Worth = Total Assets − Total Liabilities.
- Assets में bank balance, FD, shares, mutual funds, EPF, PPF, NPS, gold, property और अन्य valuables शामिल हो सकते हैं।
- Liabilities में home loan, car loan, personal loan, credit-card dues, taxes due और अन्य outstanding obligations शामिल होते हैं।
- Assets को सामान्यतः आज की realistic value पर track करना बेहतर है, purchase price पर नहीं।
- Self-use घर total net worth का हिस्सा हो सकता है, लेकिन retirement या financial-independence planning में उसे अलग दिखाना ज्यादा useful हो सकता है क्योंकि वह तुरंत income पैदा नहीं करता।
- Positive net worth अच्छी शुरुआत है, लेकिन हर साल net worth का healthy trend देखना ज्यादा useful है।
- कोई universal “good net worth” number नहीं है। सही संख्या आपकी age, income, goals, liabilities और lifestyle पर depend करती है।
Net Worth का मतलब सरल भाषा में समझिए
मान लीजिए आपके पास ₹20 लाख के assets हैं और ₹8 लाख का outstanding debt है। यदि बाकी कोई liability नहीं है, तो आपकी net worth ₹12 लाख होगी।
यह आपकी monthly salary नहीं है। यह आपके पूरे financial balance sheet का एक snapshot है। आज assets की value बदल सकती है, market investments ऊपर-नीचे हो सकते हैं, property की value बदल सकती है और loan principal कम हो सकता है। इसलिए net worth एक time-specific financial measure है, कोई permanent number नहीं।
Moneycontrol की 2026 की explainer भी net worth को current values पर assets से liabilities घटाने के रूप में समझाती है और future income, expected inheritance या inflated asset values को शामिल करने से बचने की बात करती है।
Net Worth Calculate करने का Formula
सबसे basic formula है:
Net Worth = Total Assets − Total Liabilities
| Part | क्या शामिल करें | कैसे value करें |
|---|---|---|
| Assets | Cash, bank balance, FD, shares, Mutual Funds, EPF, PPF, NPS, gold, property, business interest आदि | जहां संभव हो current realistic value |
| Liabilities | Home loan, car loan, personal loan, education loan, credit-card outstanding, tax due, unpaid bills आदि | आज कितना outstanding है |
| Net Worth | Assets minus liabilities | उसी date का financial snapshot |
SEBI Investor के official calculator में savings/current accounts, deposits, EPF, PPF, NPS, shares, equity mutual funds, bonds, gold, business/partnership और real estate जैसे assets तथा home loan, car loan, personal loan, taxes due, credit-card dues और outstanding bills जैसी liabilities शामिल हैं।
Step-by-Step Net Worth Calculation कैसे करें?
Step 1: सभी Assets की list बनाइए
पहले यह मत सोचिए कि कौन-सी चीज “investment” है। सवाल सिर्फ इतना है: क्या आपके पास कोई monetary value वाली चीज है?
| Asset Category | Examples | Tracking Tip |
|---|---|---|
| Cash & Bank | Cash, Savings Account, Current Account | Statement balance या actual cash |
| Deposits | FD, RD | Current balance/value |
| Market Investments | Shares, Mutual Funds, Bonds | Current market value |
| Retirement Assets | EPF, PPF, NPS | Latest available balance/value |
| Precious Metals | Gold, Silver, eligible valuables | Conservative current resale estimate |
| Real Estate | House, Plot, Investment Property | Reasonable current market estimate |
| Business Interest | Partnership or privately held business interest | Documented and conservative value |
| Personal Assets | Car, Bike, valuable jewellery or collectibles | Current resale value, not original price |
Step 2: हर Asset की current value लिखिए
यहीं सबसे ज्यादा overvaluation होती है। आपने कोई asset ₹5 लाख में खरीदा था, इसका मतलब यह नहीं कि आज वह ₹5 लाख का ही है। Net worth tracking में purchase price से ज्यादा useful current realizable value होती है।
उदाहरण के लिए, कोई used car आज ₹3.5 लाख में बिक सकती है तो उसे ₹3.5 लाख के आसपास track करना ज्यादा realistic है, न कि purchase invoice की ₹6 लाख value पर।
Practical Tip: Market-linked investments के लिए latest market value लें। Property के लिए realistic current market estimate लें। Jewellery के लिए भाव देखकर सीधे retail bill value मत डालिए; resale value अलग हो सकती है। Personal-use assets को जरूरत से ज्यादा value देना आपकी net worth को artificially inflate कर सकता है।
Step 3: सभी Liabilities लिखिए
अब दूसरी तरफ लिखिए कि आप पर कितना बकाया है। “EMI ₹35,000 है” liability नहीं है। Liability वह outstanding amount है जिसे अभी चुकाना बाकी है।
- Home loan outstanding principal
- Car loan outstanding
- Personal loan outstanding
- Education loan outstanding
- Credit-card dues
- Tax dues, जहां applicable हों
- Family/friend से लिया हुआ documented debt
- अन्य unpaid financial obligations
Step 4: Assets में से Liabilities घटाइए
अब formula लगाइए:
Net Worth = Total Assets − Total Liabilities
Real Calculation Example 1: ₹12.20 लाख Net Worth
मान लीजिए एक 29-year-old salaried professional के पास यह financial position है। यह एक illustrative example है, किसी व्यक्ति की वास्तविक financial statement नहीं।
| Assets | Value |
|---|---|
| Savings + Cash | ₹1,20,000 |
| FD | ₹2,50,000 |
| Mutual Funds | ₹4,00,000 |
| EPF + PPF | ₹2,80,000 |
| Gold | ₹1,50,000 |
| Car current resale value | ₹3,40,000 |
| Total Assets | ₹15,40,000 |
| Liabilities | Outstanding |
|---|---|
| Car Loan | ₹2,20,000 |
| Credit Card Due | ₹35,000 |
| Personal Loan | ₹65,000 |
| Total Liabilities | ₹3,20,000 |
Calculation:
₹15,40,000 − ₹3,20,000 = ₹12,20,000
इस example में net worth ₹12.20 लाख है। ध्यान दीजिए कि salary, SIP contribution या monthly EMI amount सीधे net worth में नहीं जुड़ते। Net worth balance sheet का result है।
Real Calculation Example 2: Home Loan वाले परिवार की Net Worth
अब एक family case देखते हैं जहां self-use घर है। मान लीजिए:
- Self-use flat current estimated value: ₹80 लाख
- Mutual Funds: ₹6 लाख
- EPF/PPF/NPS: ₹4 लाख
- Bank + FD: ₹1.50 लाख
- Gold: ₹2.50 लाख
- Car current value: ₹5 लाख
Total assets = ₹99 लाख
अब outstanding liabilities:
- Home loan: ₹45 लाख
- Car loan: ₹2 लाख
- Credit-card due: ₹40,000
Total liabilities = ₹47.40 लाख
Net Worth = ₹99 लाख − ₹47.40 लाख = ₹51.60 लाख
इस family की total net worth ₹51.60 लाख है। लेकिन एक important point है: इसमें करीब ₹80 लाख का घर शामिल है। इसका मतलब यह नहीं कि family के पास ₹51.60 लाख cash या investable money भी उपलब्ध है। यही कारण है कि total net worth और liquid/financial net worth को अलग track करना practical planning में बहुत useful होता है।
Total Net Worth vs Liquid Net Worth: दोनों में फर्क क्या है?
यह article का सबसे useful practical distinction है। Basic net worth formula एक ही है, लेकिन financial planning में एक ही number पर depend करना misleading हो सकता है।
| Metric | क्या दिखाता है | Typical Components | कब useful है? |
|---|---|---|---|
| Total Net Worth | आपके पूरे balance sheet की net position | All assets minus all liabilities | Overall wealth tracking |
| Financial Net Worth | Financial assets की स्थिति | Cash, FD, MF, Shares, EPF, PPF, NPS आदि minus relevant liabilities | Investment planning और financial goals |
| Liquid Net Worth | Relatively quickly accessible wealth | Cash, bank, certain deposits and readily saleable investments, minus short-term liabilities | Emergency planning और short-term resilience |
यह categories कोई एक universal accounting standard नहीं हैं। अलग planners अलग definitions use कर सकते हैं। इसलिए सबसे महत्वपूर्ण बात यह है कि आप हर साल वही methodology consistently use करें, ताकि trend meaningful रहे।
SEBI का official calculator भी assets को liquid, partial-liquid और illiquid categories में अलग दिखाता है, जो यह समझने में मदद करता है कि ₹1 करोड़ net worth होने का मतलब ₹1 करोड़ immediately spendable cash नहीं है।
Self-Use घर को Net Worth में शामिल करें या नहीं?
इस सवाल पर काफी confusion मिलता है। Practical answer है: Total net worth में शामिल किया जा सकता है, क्योंकि घर आपकी आर्थिक संपत्ति है और उसके सामने home loan liability भी मौजूद हो सकती है।
लेकिन retirement planning में इसे अलग view से देखना चाहिए। आपका self-use house आपकी balance sheet मजबूत कर सकता है, पर वह तब तक नियमित cash flow नहीं देता जब तक आप उसे rent, sale, downsizing या किसी दूसरे तरीके से monetize न करें।
इसलिए दो numbers रखना useful हो सकता है:
- Total Net Worth: घर सहित.
- Investable/Financial Net Worth: financial assets पर focused view, जिसमें self-use house को अलग रखा जा सकता है.
इस approach से “मेरी net worth ₹1 crore है” और “मेरे पास retirement के लिए कितनी investable wealth है?” दोनों सवालों के अलग-अलग, ज्यादा honest जवाब मिलते हैं।
Car और Bike को Asset मानना चाहिए?
हाँ, personal net worth calculation में current resale value के आधार पर इन्हें asset के रूप में शामिल किया जा सकता है। लेकिन financial planning के लिए इन्हें investment समझना जरूरी नहीं है।
Car आम तौर पर depreciation झेलती है और उसे बेचने पर transaction, usage और practical replacement issues भी होते हैं। इसलिए एक sensible system यह है कि total net worth में car की conservative resale value शामिल करें, लेकिन wealth-building assets का analysis करते समय car को अलग रखें।
यही distinction आपको “मेरी net worth बढ़ रही है” और “मेरी investable wealth बढ़ रही है” के बीच फर्क समझने में मदद करता है।
Gold और Jewellery को कैसे Calculate करें?
Gold को purchase invoice पर track करना अक्सर गलत impression दे सकता है। Investment gold, coins, bars और jewellery की resale economics अलग हो सकती है। Jewellery में making charges जैसी चीजों के कारण purchase price और resale value में फर्क हो सकता है।
Net worth tracking में बेहतर approach है कि आप realistic conservative resale value लें। बहुत aggressive valuation से net worth artificial रूप से बढ़ सकती है।
EPF, PPF और NPS Net Worth में शामिल होते हैं?
सामान्य personal balance-sheet view में आपके ownership वाले retirement assets को net worth में include किया जा सकता है। SEBI के official Net Worth Calculator में EPF, PPF और NPS स्पष्ट रूप से assets की सूची में शामिल हैं।
लेकिन यहां एक practical difference समझिए: asset होना और immediately accessible होना अलग बातें हैं। किसी retirement account की liquidity, withdrawal rules या lock-in conditions आपकी financial planning पर असर डाल सकती हैं। इसलिए total net worth में include करने के साथ-साथ liquidity profile भी track करें।
क्या Future Salary, Bonus या Inheritance को Net Worth में जोड़ सकते हैं?
नहीं, जब तक वह वास्तव में आपका asset नहीं बन चुका है। अगली salary, expected annual bonus, future promotion, expected inheritance या future business profit को current net worth में जोड़ना सही नहीं है।
उदाहरण:
- अगले 3 महीनों की salary अभी asset नहीं है।
- Expected bonus, जो अभी मिला नहीं है, current asset नहीं है।
- Grandparents से expected inheritance current asset नहीं है।
- Future property appreciation भी current asset value में अनुमान से जोड़ना नहीं चाहिए।
Current net worth को जो आपके पास अभी है और जो अभी outstanding है, उसी के आधार पर रखना ज्यादा disciplined approach है।
Negative Net Worth क्या होती है?
अगर liabilities आपके total assets से ज्यादा हैं, तो net worth negative हो सकती है।
मान लीजिए:
Total Assets = ₹6 लाख
Total Liabilities = ₹9 लाख
Net Worth = ₹6 लाख − ₹9 लाख = −₹3 लाख
Negative net worth का मतलब यह नहीं कि आप financially fail हो गए हैं। Young professionals, students या ऐसे households जिनके पास education loan, personal loan या बड़े शुरुआती debts हैं, उनके लिए यह स्थिति संभव है। Important यह है कि समय के साथ trajectory कैसी है।
Watch Out: Negative net worth को hide करने के लिए assets को inflate करना समस्या को solve नहीं करता। Better strategy है debt outstanding और asset values दोनों को honestly track करना।
क्या High Salary का मतलब High Net Worth है?
नहीं। Income और net worth अलग metrics हैं।
मान लीजिए Person A की monthly take-home salary ₹2 लाख है, लेकिन उसके पास expensive car loan, personal loan और high lifestyle expenses हैं। Person B ₹1.20 लाख कमाता है, लेकिन disciplined saving, investing और low debt की वजह से उसकी net worth ज्यादा हो सकती है।
इसलिए salary आपको बताती है कि आप कितना कमा रहे हैं। Net worth बताती है कि आपने कितना financial value build किया है, debt घटाने के बाद।
क्या एक “Good Net Worth” तय होती है?
एक universal target बताना misleading होगा। “30 साल की age पर इतनी net worth होनी ही चाहिए” जैसे thumb rules कुछ planning discussions में मिलते हैं, लेकिन उन्हें universal financial law की तरह नहीं लेना चाहिए। आपकी city, salary, family responsibilities, inherited property, home loan, बच्चों की education, business ownership और retirement goal सब equation बदल देते हैं।
इससे बेहतर तरीका है कि आप तीन questions पूछें:
- क्या मेरी net worth पिछले 12 महीनों में बढ़ी?
- क्या मेरी high-cost debt कम हो रही है?
- क्या मेरे financial assets, cash reserves और retirement assets मेरे goals के हिसाब से बढ़ रहे हैं?
यानी trend + quality + liquidity केवल एक headline number से ज्यादा useful framework है।
Net Worth बढ़ाने का Practical Framework
Net worth बढ़ती है जब आपकी assets तेजी से बढ़ें, liabilities कम हों, या दोनों का combination हो। इसके लिए कोई secret formula नहीं है, लेकिन चार levers सबसे practical हैं:
| Lever | आप क्या कर सकते हैं? | Effect |
|---|---|---|
| Save More | Income बढ़ने पर savings rate improve करें | Assets build होते हैं |
| Invest Consistently | Goal-based investing और long-term discipline | Financial assets grow हो सकते हैं, लेकिन returns guaranteed नहीं हैं |
| Reduce Debt | High-cost debt और unnecessary borrowing control करें | Liabilities घटती हैं |
| Avoid Asset Overvaluation | Current realistic value पर track करें | Financial picture ज्यादा honest रहती है |
आप अपने monthly budget को इस system से जोड़ सकते हैं। dineshrewale.com की Monthly Budget की practical guide में income, expenses, savings और goals को structure करने का framework दिया गया है।
Net Worth को Improve करने के लिए Debt और Cash Flow दोनों देखें
कई लोग net worth बढ़ाने की कोशिश में सिर्फ investments देखते हैं। लेकिन अगर investment ₹5 लाख बढ़ा और साथ में personal loan ₹4 लाख बढ़ गया, तो net improvement बहुत कम है।
इसीलिए monthly cash flow और annual net worth दोनों track करना चाहिए। आपके लिए useful dashboard कुछ ऐसा हो सकता है:
- Monthly income
- Monthly expenses
- Monthly savings
- Total liabilities
- Total financial assets
- Total net worth
- Liquid net worth
Budgeting पर आपकी existing guide 50-30-20 Rule भी शुरुआती framework के रूप में उपयोगी हो सकती है, लेकिन इसे अपने actual expenses और goals के हिसाब से adapt करना चाहिए।
आपकी Net Worth कितनी बार Calculate करनी चाहिए?
हर दिन net worth देखने की जरूरत नहीं है। Market-linked assets रोज बदल सकते हैं, जिससे short-term noise बढ़ता है। अधिकांश individuals के लिए quarterly या yearly full review काफी practical है।
एक simple annual process:
- एक fixed date चुनें, जैसे 31 March या financial year-end के आसपास कोई consistent date.
- Bank, FD, MF, shares और retirement balances collect करें.
- Property, gold और vehicle की realistic current value review करें.
- सभी outstanding loans और other liabilities update करें.
- Net worth calculate करें.
- पिछले वर्ष से compare करें.
- अगर net worth नहीं बढ़ी, तो reason identify करें: spending, new debt, asset price movement, low savings या कोई one-time expense.
Net Worth Track करते समय 10 Common Mistakes
- Purchase price को current value मानना: पुराने asset का आज का market/resale value अलग हो सकता है.
- Outstanding loan की जगह original loan amount लिखना: liability current outstanding होनी चाहिए.
- Credit-card due भूल जाना: छोटी liability भी balance sheet का हिस्सा है.
- Future bonus जोड़ देना: expected income current asset नहीं है.
- Home value inflate करना: optimistic broker quote और realistic realizable value अलग हो सकती है.
- Car को investment समझना: asset हो सकती है, लेकिन wealth-building asset अलग सवाल है.
- Jewellery को retail bill पर value करना: resale value अलग हो सकती है.
- Total net worth को spendable cash समझना: illiquid assets तुरंत cash नहीं बनते.
- एक साल का number देखकर conclusion निकालना: multi-year trend ज्यादा useful है.
- Methodology बदलते रहना: आज घर include किया, अगले साल exclude कर दिया तो comparison misleading होगा.
Net Worth और Emergency Fund का क्या संबंध है?
Net worth आपको overall financial position दिखाती है, जबकि emergency fund short-term financial shock absorb करने में मदद करता है। इसलिए high net worth होने के बावजूद liquidity कम हो तो practical stress हो सकता है।
उदाहरण के लिए किसी व्यक्ति की net worth ₹75 लाख हो सकती है, लेकिन उसका अधिकांश wealth self-use property में locked हो। ऐसे व्यक्ति के पास अचानक income interruption आने पर पर्याप्त liquid reserve न हो सकता है।
इसलिए total net worth के साथ emergency reserves को अलग line item के रूप में track करना useful है। dineshrewale.com की Emergency Fund कितनी होनी चाहिए? guide इस हिस्से को detail में समझाती है।
Net Worth और Investment Portfolio में फर्क
Investment portfolio आपके investments का collection है। Net worth उससे बड़ा concept है।
मान लीजिए आपके investments ₹15 लाख हैं, लेकिन आपके पास ₹30 लाख का home loan और ₹10 लाख का house equity है। सिर्फ investment portfolio देखकर आपकी financial position अधूरी दिखेगी।
इसी तरह, आपकी net worth ₹1 crore हो सकती है, लेकिन अगर ₹80 लाख self-use home में हैं तो आपका liquid investment portfolio सिर्फ ₹20 लाख के आसपास हो सकता है। इसलिए wealth planning करते समय net worth + asset allocation + liquidity + debt को साथ देखना बेहतर है।
आप asset allocation को और detail में समझने के लिए उम्र और salary के हिसाब से Asset Allocation वाली guide पढ़ सकते हैं।
क्या Net Worth Calculator का इस्तेमाल करना चाहिए?
हाँ, calculator manual calculation को आसान बना सकता है, खासकर जब आपके पास कई bank accounts, investments, properties और loans हों। SEBI Investor का official Net Worth Calculator assets और liabilities को अलग-अलग input लेकर net worth, debt-to-asset ratio और liquidity categories का snapshot देता है।
लेकिन calculator का result उतना ही अच्छा होगा जितना आपका input। गलत property value, पुराना loan balance या inflated gold value डालने पर calculator भी गलत picture देगा।
Net Worth Certificate और Net Worth में क्या फर्क है?
Net worth आपकी financial position का number है। Net worth certificate एक formal document हो सकता है जो assets और liabilities की स्थिति को document करता है, अक्सर specific institutional or loan-related requirements के लिए। Certificate की जरूरत होने पर lender या institution की exact documentation requirements follow करनी चाहिए।
ClearTax के अनुसार net worth certificate assets और liabilities का formal financial statement/document हो सकता है और इसे Chartered Accountant द्वारा certify किया जा सकता है।
एक Simple Net Worth Worksheet बनाइए
आप इसे spreadsheet, notebook या personal finance app में बना सकते हैं:
| Section | Amount |
|---|---|
| Cash + Bank | ₹________ |
| FD/RD | ₹________ |
| Shares + Mutual Funds | ₹________ |
| EPF + PPF + NPS | ₹________ |
| Gold/Silver/Valuables | ₹________ |
| Real Estate | ₹________ |
| Vehicle/Other Assets | ₹________ |
| Total Assets | ₹________ |
| Home Loan | ₹________ |
| Car Loan | ₹________ |
| Personal/Education Loan | ₹________ |
| Credit Card + Other Dues | ₹________ |
| Total Liabilities | ₹________ |
| Net Worth | Total Assets − Total Liabilities |
आपके लिए Net Worth का सही Use क्या है?
Net worth का सबसे अच्छा उपयोग दूसरों से comparison करने के लिए नहीं, बल्कि अपनी financial progress measure करने के लिए करना चाहिए।
एक practical decision framework:
| अगर आपकी स्थिति यह है… | सबसे पहले क्या देखें? |
|---|---|
| Net worth positive लेकिन liquidity बहुत कम | Emergency fund और liquid assets |
| Net worth negative और high-cost debt ज्यादा | Debt reduction + cash-flow control |
| Net worth बढ़ रही है लेकिन mostly self-use property में | Financial assets और retirement corpus |
| Income अच्छी है लेकिन net worth flat है | Savings rate, lifestyle inflation और debt |
| Net worth healthy है लेकिन investments highly concentrated हैं | Asset allocation और concentration risk |
| Net worth तेजी से बढ़ रही है क्योंकि property value estimate बढ़ाया है | Valuation assumptions को conservative तरीके से recheck करें |
Practical Action Checklist
- आज अपने सभी bank balances और deposits collect करें.
- अपने Mutual Funds, shares और retirement account balances update करें.
- Property, gold और vehicle की realistic current value लिखें.
- हर loan का outstanding amount देखें.
- Credit-card due और other pending obligations जोड़ें.
- Total Assets − Total Liabilities calculate करें.
- इसके बाद financial/liquid net worth अलग line में track करें.
- यह worksheet कम से कम साल में एक बार update करें.
- केवल number नहीं, उसकी quality भी देखें: liquidity, debt और concentration.
FAQs: Net Worth से जुड़े 10 Common Questions
1. Net Worth का simple formula क्या है?
Net Worth = Total Assets − Total Liabilities. यही basic personal net worth calculation है।
2. क्या salary net worth में शामिल होती है?
नहीं। Salary income है। जो salary आपने वास्तव में save/invest करके assets बनाए हैं, वे net worth में आते हैं। Future salary current asset नहीं है।
3. क्या self-use घर net worth में शामिल करना चाहिए?
Total net worth में शामिल किया जा सकता है। लेकिन retirement या investable wealth analysis में इसे अलग दिखाना ज्यादा practical हो सकता है।
4. क्या car net worth का हिस्सा है?
हाँ, comprehensive personal balance sheet में current resale value को asset के रूप में शामिल किया जा सकता है। लेकिन car को wealth-generating investment मानना अलग सवाल है।
5. क्या EPF, PPF और NPS net worth में शामिल होते हैं?
हाँ, personal net worth tracking में इन्हें assets के रूप में include किया जा सकता है। SEBI Investor की official calculator भी इन्हें assets के रूप में list करती है।
6. क्या credit-card bill liability है?
हाँ, outstanding credit-card amount liability है। अगर statement due चुकाया जा चुका है तो वह outstanding liability नहीं रहेगी।
7. क्या future bonus को net worth में जोड़ सकते हैं?
नहीं, expected bonus तब तक current asset नहीं है जब तक वह वास्तव में प्राप्त न हो जाए।
8. क्या negative net worth खराब होती है?
Negative net worth एक warning sign हो सकती है, लेकिन इसे context में देखना चाहिए। Young earners के education loans या initial debts हो सकते हैं। महत्वपूर्ण है कि debt trajectory और net worth समय के साथ किस दिशा में जा रहे हैं।
9. Net worth कितनी बार calculate करनी चाहिए?
Most individuals के लिए quarterly या yearly review पर्याप्त है। Full annual review को एक fixed date पर करना सबसे practical है।
10. क्या high net worth का मतलब financial freedom है?
जरूरी नहीं। अगर wealth का बड़ा हिस्सा illiquid property में है, तो total net worth बड़ी हो सकती है लेकिन retirement income या emergency liquidity उतनी मजबूत नहीं हो सकती।
निष्कर्ष: Net Worth आपका Financial Scoreboard है
Net worth कोई ऐसी संख्या नहीं है जिसे देखकर आपको दूसरों से अपनी तुलना करनी चाहिए। इसका असली काम आपको यह दिखाना है कि आप कहाँ खड़े हैं, आपकी liabilities कितनी हैं, आपकी wealth किस तरह के assets में है और पिछले समय में आपकी financial position किस दिशा में गई है।
सबसे simple starting point यही है:
Total Assets − Total Liabilities = Net Worth
लेकिन बेहतर financial planning के लिए वहीं मत रुकिए। Total net worth के साथ financial net worth, liquid assets, debt burden और asset concentration भी देखिए। Self-use house, car, jewellery और retirement assets को consistently track कीजिए और हर साल methodology न बदलें।
जब आप इसे एक बार calculate करना शुरू कर देते हैं, तो monthly budget, emergency fund, investing और debt management के decisions भी ज्यादा स्पष्ट दिखाई देने लगते हैं। आपका लक्ष्य सिर्फ net worth को बड़ा करना नहीं होना चाहिए, बल्कि उसे मजबूत, liquid और goals के अनुरूप बनाना होना चाहिए।
याद रखिए: Income वह पैसा है जो आप कमाते हैं। Net worth वह value है जो liabilities घटाने के बाद आपके पास बचती है। Wealth building की दिशा समझने के लिए दोनों को साथ देखना जरूरी है।
Financial Disclaimer
यह लेख केवल educational और informational purpose के लिए है। Net worth calculation के examples illustrative हैं और आपकी वास्तविक financial position आपकी assets की current valuation, liabilities, ownership structure और उपलब्ध documents पर निर्भर करेगी। Investments का market value बदल सकता है, और किसी भी investment return की guarantee नहीं होती। Tax, loan, property valuation, retirement-account rules या अन्य regulated matters में decision लेने से पहले relevant official source और जरूरत होने पर qualified professional से अपनी specific situation verify करें।