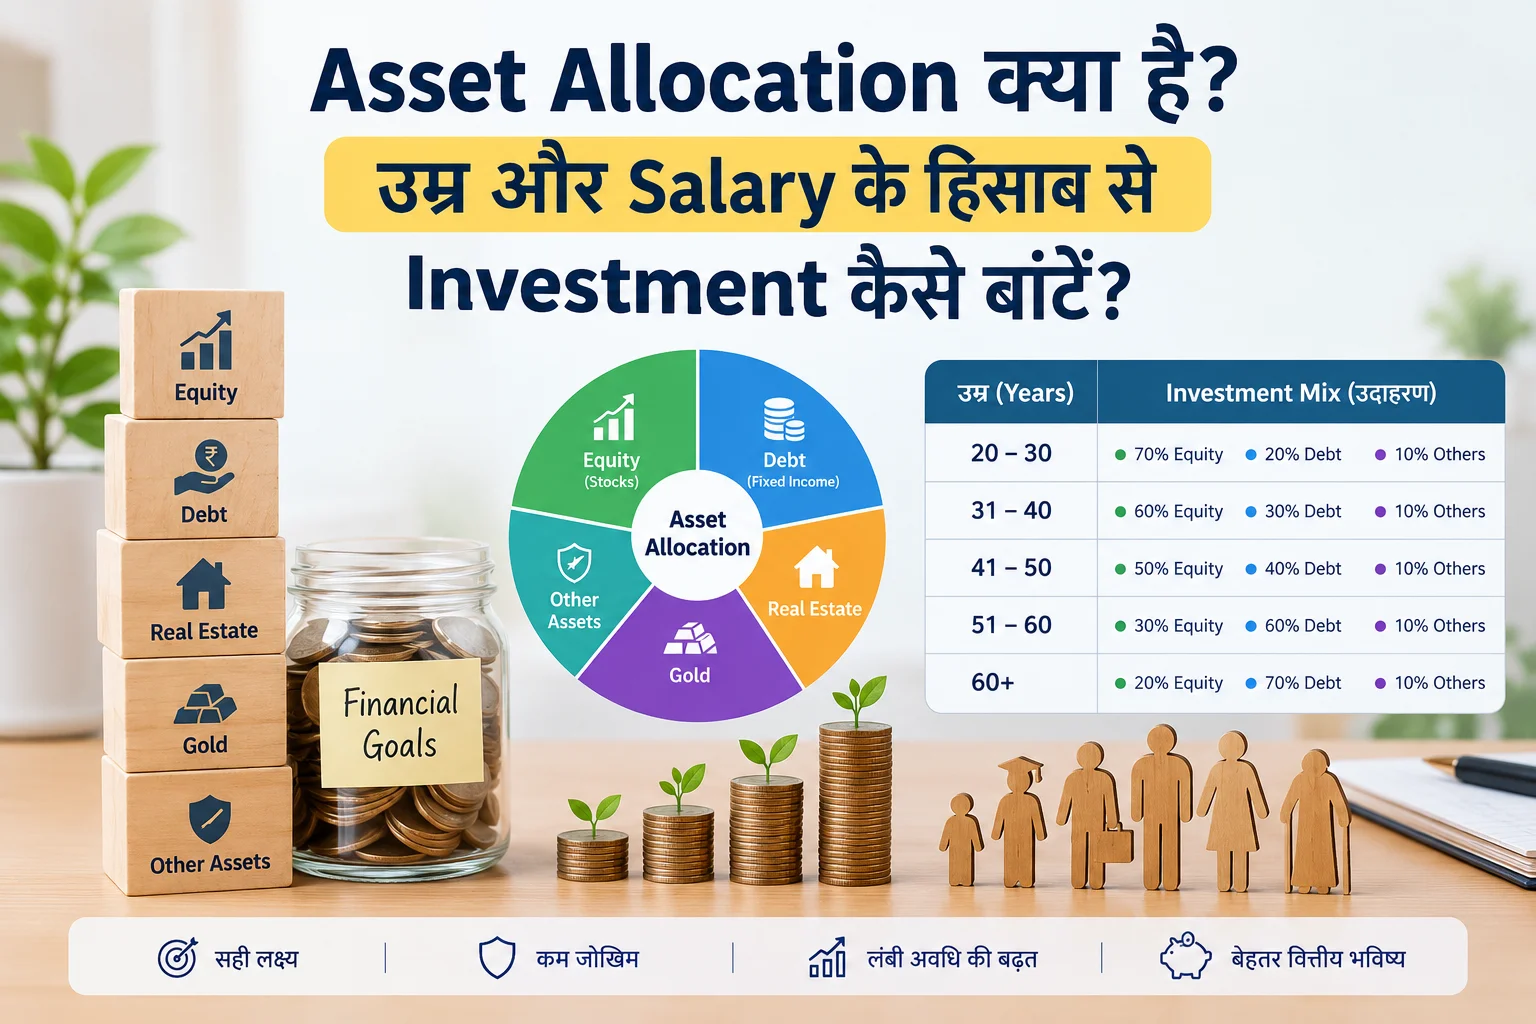
Asset Allocation क्या है? उम्र और Salary के हिसाब से Investment कैसे बांटें?
आपकी salary ₹50,000 हो, ₹1 लाख हो या ₹2 लाख, एक सवाल लगभग हर investor के सामने आता है: हर महीने बचने वाले पैसे को कहाँ invest करें? पूरा पैसा Mutual Funds में डालें? FD और PPF में रखें? Gold कितना हो? और उम्र बढ़ने पर Equity कम करनी चाहिए या नहीं?
यहीं Asset Allocation काम आता है। इसका मतलब सिर्फ Equity और Debt को 70:30 या 60:40 में बांटना नहीं है। असल में Asset Allocation यह तय करने की प्रक्रिया है कि आपके निवेश का कितना हिस्सा अलग-अलग asset classes में होना चाहिए, ताकि आपका portfolio आपके goal, investment horizon, risk tolerance और personal circumstances के साथ मेल खाए। SEBI भी asset allocation को financial goals, risk tolerance और time horizon से जोड़ता है और diversification तथा समय-समय पर rebalancing की सलाह देता है।
समस्या तब शुरू होती है जब आप internet पर कोई एक formula देखकर उसे अपनी पूरी financial life पर लागू कर देते हैं। सबसे popular example है 100 minus age rule। उम्र 30 है तो 70% Equity, उम्र 50 है तो 50% Equity। यह एक starting point हो सकता है, लेकिन यह अपने-आप में complete financial plan नहीं है।
एक 30 साल के व्यक्ति को 3 साल बाद घर खरीदना है तो house down payment का पैसा 70% Equity में रखना समझदारी नहीं होगी। दूसरी तरफ 55 साल का व्यक्ति, जिसके पास pension income और कई वर्षों का investment horizon है, उसे केवल उम्र के आधार पर बहुत कम Equity रखना भी जरूरी नहीं।
इस guide में आप एक practical framework सीखेंगे: उम्र से शुरुआत करें, लेकिन final allocation तय करते समय goal की deadline, investable surplus, emergency fund, debt, insurance, risk tolerance और पहले से मौजूद assets भी देखें।
इससे आप “कौन सा Mutual Fund अच्छा है?” पूछने से पहले यह समझ पाते हैं कि आपके पूरे portfolio को कितना risk लेना चाहिए।
Quick Answer: Asset Allocation कैसे तय करें?
- Asset Allocation का मतलब Equity, Debt, Gold और जरूरत के अनुसार अन्य assets में portfolio को बांटना है।
- सिर्फ उम्र देखकर allocation तय करना सही नहीं है। Goal और time horizon पहले देखें।
- 10 साल या उससे अधिक दूर वाले growth goals में Equity की भूमिका बड़ी हो सकती है, लेकिन short-term goals का पैसा Equity पर निर्भर नहीं होना चाहिए।
- Salary allocation में पहले investable surplus निकालें। Gross salary का कोई fixed percentage सीधे Equity में डालना universal rule नहीं है।
- Emergency Fund को long-term investment portfolio की Equity allocation में न गिनें। उसे liquidity और safety के लिए अलग bucket की तरह देखें।
- घर जैसी बड़ी asset पहले से है तो आपका overall net-worth allocation Equity, Debt, Gold और Real Estate को मिलाकर अलग दिख सकता है।
- Portfolio समय के साथ target ratio से हटे तो rebalancing करें, लेकिन हर market move पर portfolio बदलना जरूरी नहीं है।
Asset Allocation क्या है?
मान लीजिए आपके पास निवेश के लिए ₹10 लाख हैं। आप पूरा पैसा केवल Equity Mutual Funds में लगा सकते हैं। दूसरा option यह है कि ₹7 लाख Equity, ₹2 लाख Debt/Fixed Income और ₹1 लाख Gold जैसी categories में रखें।
यह 70:20:10 एक illustrative asset allocation है।
इसका उद्देश्य किसी एक asset class को “best” घोषित करना नहीं है। अलग assets का व्यवहार अलग हो सकता है।
Equity long-term growth का engine बन सकती है। Debt portfolio को comparatively stable हिस्सा दे सकता है। Gold कुछ परिस्थितियों में diversification दे सकता है।
Real Estate भी एक asset class है, लेकिन उसे liquid portfolio allocation के साथ अलग से देखना अक्सर बेहतर होता है क्योंकि property का ticket size बड़ा और liquidity कम हो सकती है।
SEBI के investor education material के अनुसार asset allocation में time frame, risk tolerance और personal circumstances महत्वपूर्ण variables हैं। इसलिए सही allocation हर व्यक्ति के लिए एक जैसा नहीं हो सकता।
Asset Allocation और Diversification में क्या अंतर है?
इसका मतलब है कि आपके पास 5 Mutual Funds होना जरूरी नहीं कि आपका portfolio diversified हो।
पांचों अगर लगभग एक जैसे Equity segments में invest करते हैं, तो fund count ज्यादा होगा लेकिन वास्तविक diversification उतनी नहीं होगी।
Asset Allocation क्यों जरूरी है?
- Market गिरने पर पूरे portfolio को एक ही दिशा में जाने से रोक सकता है
अगर आपका 100% investable portfolio Equity में है, तो बड़ा market correction आपके पूरे portfolio को प्रभावित करेगा।
Debt और Gold जैसी अलग categories कुछ diversification दे सकती हैं। यह loss को खत्म नहीं करतीं, लेकिन concentration कम कर सकती हैं।
- आपको goal के करीब जाने में मदद मिलती है
जिस पैसे की जरूरत अगले 2-3 साल में है, उसका उद्देश्य long-term wealth creation जैसा नहीं है।
ऐसे goal में capital preservation और liquidity ज्यादा महत्वपूर्ण हो सकते हैं।
वहीं retirement जैसे 20 साल दूर के goal में inflation और long-term growth को ध्यान में रखते हुए Equity की भूमिका बड़ी हो सकती है।
- Market timing की dependency कम होती है
हर बार market गिरने पर Equity बेच देना और market तेज होने पर वापस खरीदना व्यवहारिक रूप से कठिन है।
पहले से तय allocation और disciplined rebalancing आपको headlines के बजाय plan पर टिके रहने में मदद कर सकते हैं।
सबसे Popular Formula: 100 Minus Age Rule
इस rule में सामान्यतः:
100 – आपकी उम्र = Equity allocation
माना जाता है। बाकी हिस्सा Debt या fixed income में रखा जाता है।
उदाहरण:
| उम्र | Approx. Equity | बाकी Debt |
|---|---|---|
| 25 | 75% | 25% |
| 30 | 70% | 30% |
| 40 | 60% | 40% |
| 50 | 50% | 50% |
| 60 | 40% | 60% |
यह formula समझने के लिए useful है क्योंकि उम्र बढ़ने के साथ capital को protect करने की जरूरत बढ़ सकती है।
लेकिन इसे ideal allocation न मानें।
Moneycontrol और Value Research की discussions भी दिखाती हैं कि age-only rules retirement age, income stability, existing assets और goals जैसे factors को ignore कर सकते हैं।
Watch Out: “100 minus age” एक starting formula है, personalized financial plan नहीं। अगर आपका कोई goal 3 साल दूर है, तो उस goal का पैसा केवल इसलिए Equity में नहीं होना चाहिए क्योंकि आपकी उम्र कम है।
SEBI के हिसाब से Asset Allocation में कौन-सी बातें महत्वपूर्ण हैं?
SEBI Investor के अनुसार asset allocation आपके financial goals, risk tolerance और time horizon के आधार पर तय होना चाहिए।
SEBI का official Asset Allocation Calculator यह भी स्पष्ट करता है कि high Equity allocation को automatically high return का synonym नहीं समझना चाहिए और Equity को long-term goals के लिए इस्तेमाल करने की जरूरत होती है क्योंकि market crash के बाद recovery के लिए समय चाहिए।
SEBI investor guidance portfolio को समय-समय पर review और rebalance करने की बात भी करती है, खासकर life events जैसे marriage, children और retirement के आसपास।
Official References
“SEBI Investor: Investment से पहले किन बातों का ध्यान रखें” (https://investor.sebi.gov.in/investment-thingsbeforeinv.html)
“SEBI Asset Allocation Calculator” (https://investor.sebi.gov.in/calculators/Assets_Allocations.html)
उम्र के हिसाब से Asset Allocation: एक Practical Framework
नीचे दिए गए ranges illustrative framework हैं, universal prescription नहीं।
आपका final mix goals, risk tolerance, income stability और existing assets के अनुसार बदल सकता है।
| Life Stage | Illustrative Equity | Illustrative Debt | Gold | मुख्य फोकस |
|---|---|---|---|---|
| 20s से early 30s | 70-80% | 15-25% | 5-10% | Long-term growth, emergency fund, income growth |
| Mid 30s से 40s | 60-75% | 20-30% | 5-10% | Family goals, home, children, retirement |
| 45-55 | 50-65% | 25-40% | 5-10% | Goal protection और retirement readiness |
| 55-65 | 35-55% | 35-55% | 5-10% | Retirement income और sequence risk |
| 65+ | 25-45% | 45-65% | 5-10% | Withdrawal needs, liquidity, longevity risk |
Important: Cash/Emergency Fund को इस Equity-Debt-Gold allocation में जबरदस्ती fit न करें।
Emergency money का काम market return कमाना नहीं बल्कि जरूरत के समय उपलब्ध रहना है।
20s में Asset Allocation कैसी हो सकती है?
आपकी उम्र 25-30 है और retirement 25-35 साल दूर है तो long-term goals के लिए Equity की capacity आम तौर पर ज्यादा हो सकती है।
लेकिन इसका मतलब यह नहीं कि आपकी हर savings Equity में जाएगी।
पहले emergency fund और insurance जैसे protection layers व्यवस्थित करें।
इसके बाद long-term wealth bucket के लिए Equity बड़ा हिस्सा हो सकता है।
Short-term goals जैसे अगले 2 साल में vehicle purchase या education payment के लिए अलग low-volatility bucket रखें।
30s और 40s में क्या बदलता है?
यही वह stage है जहाँ salary बढ़ सकती है, लेकिन साथ में responsibilities भी बढ़ती हैं।
Home loan, children, parents, insurance premiums और lifestyle खर्च portfolio पर दबाव डाल सकते हैं।
इस stage में केवल “मेरी उम्र 35 है, इसलिए 65% Equity” कहना पर्याप्त नहीं है।
बेहतर तरीका यह है कि हर बड़े goal का अपना horizon तय करें।
Retirement 20 साल दूर है तो Equity-heavy allocation हो सकता है।
बच्चे की higher education 4 साल दूर है तो उस goal का allocation काफी conservative हो सकता है।
50s में Asset Allocation कैसे सोचें?
50s में सबसे बड़ी गलती यह मान लेना है कि retirement पास आते ही Equity को पूरी तरह खत्म कर देना चाहिए।
Retirement कई दशकों तक चल सकती है और inflation risk retirement के बाद भी रहता है।
इसलिए allocation को capital preservation और long-term purchasing power दोनों के बीच balance करना पड़ता है।
आपका retirement corpus जितना बड़ा है, income के दूसरे sources जैसे pension, rental income और annuity कितने हैं, और अगले 5-10 साल के खर्च कितने हैं, इन सबका प्रभाव allocation पर पड़ता है।
Salary के हिसाब से Investment Allocation कैसे करें?
यहां एक महत्वपूर्ण बात समझिए:
Salary asset allocation नहीं है; salary आपकी investment capacity तय करती है।
पहले income से essential expenses, debt obligations और protection costs निकालकर investable surplus पहचानें।
फिर उस surplus को goal-wise allocate करें।
Salary ₹30,000 हो तो
मान लीजिए take-home salary ₹30,000 है और essential expenses ₹21,000 हैं।
आपके पास ₹9,000 का potential surplus है।
लेकिन अगर emergency fund नहीं बना है, तो शुरुआत में पूरा ₹9,000 Equity SIP में डालना जरूरी नहीं।
पहले cash reserve build करें।
एक practical sequence हो सकता है:
Emergency Fund → Insurance Protection → High-Cost Debt Repayment → Long-Term Investment
इस तरह आपकी investing speed थोड़ी धीमी हो सकती है, लेकिन financial foundation मजबूत होती है।
Salary ₹50,000 हो तो
मान लीजिए monthly take-home salary ₹50,000 और essential expenses ₹30,000 हैं।
Potential surplus:
₹50,000 – ₹30,000 = ₹20,000
अगर emergency fund पूरा है और ₹20,000 long-term investing के लिए उपलब्ध है, तो 70:20:10 model के अनुसार:
| Asset | Allocation | ₹20,000 Monthly Surplus |
|---|---|---|
| Equity | 70% | ₹14,000 |
| Debt | 20% | ₹4,000 |
| Gold | 10% | ₹2,000 |
| Total | 100% | ₹20,000 |
Calculation
₹20,000 × 70% = ₹14,000
₹20,000 × 20% = ₹4,000
₹20,000 × 10% = ₹2,000
यह सिर्फ illustration है।
अगर आपके पास home purchase का 3-year goal है तो ₹14,000 Equity में भेजना जरूरी नहीं होगा।
Goal bucket के अनुसार allocation बदल सकता है।
Salary ₹1 लाख हो तो
मान लीजिए ₹1,00,000 take-home salary में आपका total planned monthly outflow ₹60,000 है।
Potential surplus:
₹1,00,000 – ₹60,000 = ₹40,000
अगर emergency fund और insurance ठीक हैं और यह पूरा surplus long-term investing के लिए उपलब्ध है, तो 70:20:10 illustration:
| Bucket | Ratio | Monthly Amount |
|---|---|---|
| Equity | 70% | ₹28,000 |
| Debt | 20% | ₹8,000 |
| Gold | 10% | ₹4,000 |
| Total | 100% | ₹40,000 |
यहां सबसे जरूरी बात ratio नहीं, बल्कि यह है कि आपकी investment amount और allocation दोनों आपकी financial situation के साथ बढ़ें।
असली takeaway यह है कि salary बढ़ने पर investment amount बढ़ना चाहिए, लेकिन lifestyle inflation को पूरा surplus खाने नहीं देना चाहिए।
Age + Salary + Goal: तीनों को साथ कैसे जोड़ें?
यह इस article का सबसे practical framework है।
किसी भी investment decision से पहले ये 5 सवाल पूछें:
- यह पैसा कब चाहिए?
2 साल, 5 साल, 10 साल या 20+ साल? - अगर portfolio 30-40% गिर जाए तो क्या मैं goal पूरा कर पाऊंगा?
- मेरी salary कितनी stable है?
Variable income वाले investor को अधिक liquidity की जरूरत हो सकती है। - मेरे पास पहले से क्या assets हैं?
Own house, EPF, PPF, NPS, FDs और existing Mutual Funds भी picture बदलते हैं। - इस goal के समय कितनी राशि चाहिए?
सिर्फ “SIP करना है” पर्याप्त नहीं। Target amount और deadline भी तय होनी चाहिए।
Goal-wise Asset Allocation उम्र से ज्यादा महत्वपूर्ण क्यों हो सकता है?
Goal Horizon General Approach क्यों? 0-3 साल Capital preservation और liquidity पर जोर Short-term market fall से recovery का समय कम हो सकता है 3-7 साल Balanced और goal-specific allocation कुछ Equity संभव हो सकती है, लेकिन पूरी राशि Equity में रखना जरूरी नहीं 7-10 साल Higher growth allocation consider किया जा सकता है लंबे horizon से volatility को absorb करने का अवसर बढ़ता है 10+ साल Long-term Equity की बड़ी भूमिका संभव Inflation और long-term growth needs को ध्यान में रखा जा सकता है
यह कोई fixed regulatory formula नहीं है।
Goal horizon जितना छोटा होगा, Equity risk को justify करना उतना कठिन हो सकता है।
SEBI का asset allocation calculator भी Equity को long-term goals और recovery time के संदर्भ में देखने की सलाह देता है।
Portfolio में Debt में क्या रखा जा सकता है?
Debt bucket में आपके context के अनुसार bank FDs, PPF, suitable government-backed instruments, high-quality bonds, debt mutual funds और EPF जैसे fixed-income exposures शामिल हो सकते हैं।
लेकिन इन सभी में liquidity, tax treatment, tenure और risk अलग-अलग हो सकते हैं।
इसलिए “Debt = हमेशा safe” भी oversimplification है।
उदाहरण के लिए long-term retirement bucket में EPF/NPS/PPF जैसी holdings पहले से बड़ी हैं तो अलग Debt Mutual Fund allocation उतना जरूरी नहीं हो सकता।
दूसरी तरफ self-employed investor के पास EPF नहीं है तो उसे fixed-income allocation को अलग तरीके से build करना पड़ सकता है।
Gold को Asset Allocation में कितना रखें?
Gold को portfolio का core growth engine मानने के बजाय diversification tool की तरह देखना ज्यादा practical हो सकता है।
Illustrative portfolio में 5-10% जैसा allocation कुछ investors के लिए पर्याप्त हो सकता है, लेकिन यह universal rule नहीं है।
आपके पास physical gold, jewellery या other gold exposure पहले से है तो financial portfolio में नया Gold allocation जोड़ते समय total exposure देखना जरूरी है।
Jewellery को investment gold मानना भी हमेशा सही नहीं क्योंकि making charges, purity और resale considerations अलग होते हैं।
Real Estate को Asset Allocation में गिनना चाहिए?
हाँ, net-worth level पर Real Estate एक asset class है।
लेकिन आपके investment portfolio की allocation और household net-worth allocation अलग views दे सकते हैं।
मान लीजिए आपकी net worth का 60% अपने घर में locked है और financial assets का 80% Equity में है।
केवल Mutual Fund portfolio देखकर आपको 80% Equity दिखेगा, लेकिन total household wealth की picture अलग होगी।
इसी कारण home ownership, investment property और rental income को overall financial planning में अलग से include करना चाहिए।
Emergency Fund को Asset Allocation में कैसे देखें?
Emergency Fund का उद्देश्य investment return maximize करना नहीं है।
इसका उद्देश्य है कि job loss, medical expense, urgent repair या income disruption जैसे situations में आपको Equity market के खराब समय में investments बेचने की जरूरत न पड़े।
अगर आप emergency fund को सही तरीके से समझना चाहते हैं, तो हमारी Emergency Fund कितना होना चाहिए? guide भी पढ़ें। इसे long-term investment से अलग safety bucket की तरह सोचें।
Emergency reserve पूरा होने के बाद long-term allocation को अधिक systematically grow करना आसान हो सकता है।
Rebalancing क्या है और कब करना चाहिए?
मान लीजिए आपका target allocation:
- Equity = 70%
- Debt = 20%
- Gold = 10%
आपके पास शुरुआत में ₹5 लाख हैं।
Asset Target % Starting Value Equity 70% ₹3,50,000 Debt 20% ₹1,00,000 Gold 10% ₹50,000
अब मान लीजिए कुछ समय बाद:
- Equity = ₹4,50,000
- Debt = ₹1,00,000
- Gold = ₹50,000
Total portfolio:
₹4,50,000 + ₹1,00,000 + ₹50,000 = ₹6,00,000
अब Equity weight:
₹4,50,000 ÷ ₹6,00,000 × 100 = 75%
Target 70% था, लेकिन अब Equity 75% हो गई।
यानी market movement ने बिना आपकी नई buying के risk profile बदल दी।
यही rebalancing का practical reason है।
आप नई contributions को underweight assets में भेज सकते हैं या जरूरत के अनुसार कुछ holdings rebalance कर सकते हैं।
Tax, exit load, transaction cost और goal proximity को ध्यान में रखकर decision लें।
NPS में Age-Based Asset Allocation कैसे काम करता है?
NPS एक अच्छा example है कि life-cycle investing practically कैसे implement किया जाता है।
PFRDA की current information के अनुसार NPS में Active Choice में Equity allocation की सीमा up to 75% हो सकती है।
Auto Choice में subscriber की उम्र के साथ Equity allocation धीरे-धीरे कम होती है।
Life Cycle 25, Life Cycle 50, Life Cycle 75 और Aggressive life-cycle options अलग risk profiles के लिए उपलब्ध हैं।
इसका मतलब यह नहीं कि NPS की allocation हर व्यक्ति के लिए सही personal portfolio allocation है।
लेकिन यह एक useful demonstration है कि age और life stage के साथ risk exposure बदल सकता है।
Source: PFRDA, NPS All Citizen Model और Asset Allocation
कब Equity Allocation कम करनी चाहिए?
सिर्फ birthday आने पर नहीं।
इन situations में review ज्यादा meaningful हो सकता है:
- Retirement की deadline करीब आ रही हो।
- घर खरीदने या education जैसे बड़े goal की deadline 3-5 साल दूर हो।
- आपकी income unstable हो गई हो।
- आपके पास पर्याप्त emergency reserve नहीं है।
- Debt obligations तेजी से बढ़ गए हों।
- Market rally के बाद Equity portfolio target से बहुत ऊपर चला गया हो।
- आपका risk tolerance बदल गया हो और आप market falls psychologically handle नहीं कर पा रहे हों।
कब Equity Allocation बढ़ाना भी गलत हो सकता है?
एक common mistake है:
“मैं young हूं, इसलिए 90-100% Equity रखना ही चाहिए।”
Age सिर्फ एक input है।
अगर आपको 2 साल में ₹20 लाख की property down payment चाहिए और वही पैसा Equity में है, तो market timing risk आपकी पूरी योजना को प्रभावित कर सकता है।
दूसरी गलती है salary बढ़ने के साथ Equity allocation भी automatically बढ़ा देना।
Salary increase का पहला काम financial resilience और investment amount बढ़ाना हो सकता है, न कि portfolio को अचानक ज्यादा risky बनाना।
Asset Allocation में 7 बड़ी गलतियां
- 100 Minus Age को Universal Rule मानना
यह starting point हो सकता है, final answer नहीं।
- Goal की Deadline Ignore करना
Short-term money को long-term portfolio जैसा treat न करें।
- Emergency Fund को Equity में रखना
Emergency के समय market crash में forced selling का risk बढ़ सकता है।
- बहुत सारे Funds खरीदना
Fund count और diversification एक ही चीज नहीं हैं।
- Existing Assets भूल जाना
EPF, NPS, PPF और property भी overall risk picture बदलते हैं।
- Rebalancing न करना
Market movements target allocation को समय के साथ बदल सकते हैं।
- Market देखकर Allocation बदलना
Crash के बाद Equity zero करना और rally के बाद वापस खरीदना discipline को नुकसान पहुंचा सकता है।
Asset Allocation के लिए एक आसान Decision Framework
| Question | आपका Answer | Allocation पर असर |
|---|---|---|
| Goal कब है? | 0-3 / 3-7 / 7-10 / 10+ years | Short goal में risk कम रखना बेहतर हो सकता है; long goal में growth assets की capacity अधिक हो सकती है |
| Emergency Fund है? | Yes / No | नहीं है तो पहले liquidity और safety पर ध्यान दें |
| Debt कितना है? | EMI और interest cost | High-cost debt होने पर repayment priority हो सकती है |
| Income stable है? | Stable / Variable | Variable income में अधिक liquidity की जरूरत हो सकती है |
| Existing assets? | EPF, PPF, NPS, property, gold | Overall portfolio risk और diversification की तस्वीर बदल सकती है |
| Market fall tolerance? | Low / Medium / High | Allocation आपकी वास्तविक risk capacity और tolerance से match होना चाहिए |
आपके लिए Asset Allocation तय करने की 6-Step Checklist
- हर goal की target amount और deadline लिखें।
- Essential expenses के आधार पर emergency reserve तय करें और उसे अलग रखें।
- High-cost debt और insurance gaps को ignore न करें।
- अपने financial assets और major real-estate exposure की list बनाएं।
- हर long-term goal के लिए Equity/Debt/Gold का target mix तय करें, न कि पूरी life के लिए एक ही ratio।
- साल में कम से कम एक बार portfolio और major life events के बाद review करें।
अपने मौजूदा Portfolio को कैसे Check करें?
एक simple spreadsheet खोलें और हर investment के सामने तीन columns बनाएं:
Asset Class | Current Value | Goal
इसके बाद percentage निकालें।
आपको तुरंत पता चलेगा कि आपके portfolio में वास्तविक risk कहाँ है।
Example
मान लीजिए आपके पास:
- Equity Mutual Funds = ₹8 लाख
- EPF = ₹4 लाख
- PPF = ₹2 लाख
- Gold = ₹1 लाख
- Bank/FD = ₹2 लाख
Total financial assets:
₹8 लाख + ₹4 लाख + ₹2 लाख + ₹1 लाख + ₹2 लाख = ₹17 लाख
Overall financial assets में Equity का हिस्सा:
₹8 लाख ÷ ₹17 लाख × 100 = 47.1%
इसलिए केवल Mutual Fund portfolio देखकर “मेरी Equity 80% है” कहना misleading हो सकता है।
यह calculation आपको product-level नहीं बल्कि portfolio-level thinking सिखाती है।
यही Asset Allocation का असली फायदा है।
आपकी Salary चाहे जो हो, यह Rule ज्यादा महत्वपूर्ण है
Income बढ़ने पर lifestyle को पूरा surplus मत लेने दें।
जब salary ₹50,000 से ₹80,000 और फिर ₹1 लाख होती है, तो investing capacity को भी बढ़ना चाहिए।
इसके लिए step-up SIP useful हो सकता है।
लेकिन allocation हमेशा आपके goals और risk के हिसाब से रहे।
अगर आपकी salary ₹1 लाख है और आपका investable surplus ₹40,000 है, तो ₹40,000 का 70:20:10 split समझने में मदद करता है।
लेकिन यदि अगले 2 साल में घर की down payment चाहिए तो उसी ₹40,000 का बड़ा हिस्सा safer goal bucket में जा सकता है।
Goal बदलता है तो allocation भी बदल सकता है।
₹1 lakh salary पर पूरा cash-flow और investing framework समझने के लिए हमारी ₹1 Lakh Salary वालों का Investment Plan guide देखें।
और अगर आपकी salary ₹50,000 के आसपास है, तो ₹50,000 Salary पर कितना SIP करें? वाली guide भी इसी planning journey को आगे बढ़ाती है।
Asset Allocation और Mutual Fund Selection का संबंध
पहले asset allocation तय करें, फिर product चुनें।
अगर आपके portfolio को 70% Equity की जरूरत है, तो इसका मतलब यह नहीं कि आपको 7 Equity Mutual Funds खरीदने हैं।
कई investors एक ही तरह के funds खरीदकर overlap बढ़ा देते हैं।
उदाहरण के लिए core Equity exposure को simple रखने के लिए Index Fund जैसे option पर विचार किया जा सकता है, लेकिन product suitability अलग investor के लिए अलग होगी।
Index Fund और active Mutual Fund के बीच फर्क समझने के लिए हमारा Index Fund vs Mutual Fund comparison पढ़ें। वहां fund structure और selection को detail में समझाया गया है।
Mutual Fund की cost और plan selection समझने के लिए हमारी Direct vs Regular Mutual Fund guide भी देखें।
ध्यान रखें कि direct/regular choice asset allocation का substitute नहीं है।
Asset Allocation FAQs
1. Asset Allocation क्या है?
Asset Allocation का मतलब आपके investable portfolio को Equity, Debt, Gold और जरूरत के अनुसार अन्य asset classes में तय अनुपात में बांटना है।
अनुपात आपके goals, time horizon, risk tolerance और personal circumstances पर निर्भर करता है।
2. 100 Minus Age Rule क्या है?
यह एक traditional thumb rule है जिसमें आपकी उम्र को 100 से घटाकर approximate Equity allocation निकाला जाता है।
यह starting framework है, universal formula नहीं।
3. 30 साल की उम्र में कितना Equity रखना चाहिए?
एक 30-year-old long-term investor के लिए Equity allocation अपेक्षाकृत high हो सकता है, लेकिन exact percentage goal और risk tolerance पर depend करेगा।
3 साल में चाहिए money को age के आधार पर Equity में नहीं डालना चाहिए।
4. Salary का कितना हिस्सा Equity में invest करना चाहिए?
पहले salary में से essential expenses, debt obligations और protection needs के बाद investable surplus निकालें।
फिर surplus का allocation goals और risk profile के अनुसार करें।
Gross salary का कोई universal Equity percentage नहीं है।
5. क्या Emergency Fund को Debt Allocation में गिन सकते हैं?
Portfolio reporting में इसे separately track करना बेहतर हो सकता है।
इसका उद्देश्य liquidity और capital access है, इसलिए इसे long-term Debt investment bucket के साथ मिलाकर देखना जरूरी नहीं है।
6. Asset Allocation कितनी बार बदलना चाहिए?
हर market movement पर बदलने की जरूरत नहीं।
Periodic review और meaningful allocation drift, retirement proximity, marriage, children, major purchase या income change जैसे life events पर review ज्यादा useful हो सकता है।
7. क्या Gold रखना जरूरी है?
नहीं।
Gold allocation universal requirement नहीं है।
कुछ investors इसे diversification के लिए रखते हैं, लेकिन existing jewellery और other gold holdings को total exposure में include करके decision लेना चाहिए।
8. Retirement के समय Equity पूरी तरह खत्म कर देनी चाहिए?
जरूरी नहीं।
Retirement कई वर्षों तक चल सकती है और inflation risk बना रहता है।
सही mix आपकी withdrawal needs, pension, other income, total corpus और risk tolerance पर निर्भर करेगा।
9. क्या Real Estate भी Asset Allocation का हिस्सा है?
Net-worth level पर हां।
लेकिन self-use house, investment property और liquid financial portfolio अलग-अलग objectives रखते हैं, इसलिए इन्हें एक ही bucket में देखकर decision लेना practical नहीं हो सकता।
10. क्या Asset Allocation Return बढ़ाने की Guarantee देता है?
नहीं।
Asset Allocation risk management, diversification और goal alignment का framework है।
यह market loss या specific return की guarantee नहीं देता।
एक Simple Formula याद रखें
पहले Goal → फिर Time Horizon → फिर Risk → फिर Asset Allocation → फिर Investment Product
बहुत से investors इसका उल्टा करते हैं।
पहले Mutual Fund चुनते हैं, फिर देखते हैं कि उसमें कितना invest करना चाहिए।
बेहतर planning में आपका portfolio किसी एक fund के हिसाब से नहीं बल्कि आपके financial goals के हिसाब से बनता है।
सही Asset Allocation उम्र से शुरू होती है, लेकिन वहीं खत्म नहीं होती
Asset Allocation को सिर्फ “मेरी उम्र 30 है तो 70% Equity” वाली calculation तक सीमित करना आसान है।
लेकिन अच्छे financial planning में सवाल इससे आगे जाता है।
आपकी salary कितनी है, monthly surplus कितना है, emergency fund है या नहीं, loan कितना है, retirement कब है, कौन-सा goal कितनी दूर है, घर और gold जैसी assets पहले से कितनी हैं और market fall आप कितना सह सकते हैं, इन सभी चीजों को साथ देखना पड़ता है।
आपके लिए सबसे useful approach यह हो सकती है कि पूरी financial life के लिए एक permanent ratio बनाने के बजाय goal-wise buckets बनाएं।
Long-term goals में growth के लिए Equity की भूमिका ज्यादा हो सकती है।
Short-term goals में liquidity और capital stability ज्यादा महत्वपूर्ण हो सकती है।
Gold diversification दे सकता है और Debt portfolio का stabilizing component हो सकता है।
फिर समय-समय पर rebalance करके portfolio को वापस intended risk level के करीब लाएं।
और एक बात हमेशा याद रखें:
आपका सबसे बड़ा asset आपकी earning ability है।
Salary बढ़ाने, खर्च नियंत्रित करने, adequate emergency fund बनाने और disciplined investing को साथ लेकर चलना किसी single “perfect” asset allocation से ज्यादा powerful financial system बन सकता है।
Author, Methodology and Last Updated
Author: Dinesh Rewale
Methodology: यह article SEBI Investor guidance, SEBI Asset Allocation Calculator, PFRDA की current NPS asset-allocation information और Indian personal-finance search landscape के review पर आधारित educational framework है। Age और salary examples illustrative calculations हैं, personalized portfolio recommendations नहीं।
Last Updated: 10 September 2026
Financial Disclaimer
यह लेख केवल educational और informational purpose के लिए है। यहां दिए गए Equity, Debt, Gold और age/salary-based allocation ranges illustrative हैं और किसी व्यक्ति के लिए personalized investment advice, guaranteed return या “best” portfolio का दावा नहीं करते।
Mutual Funds, stocks और अन्य market-linked investments में market risk रहता है और past performance future returns की guarantee नहीं है।
निवेश का निर्णय लेने से पहले अपने financial goals, cash-flow, risk tolerance, tax situation और existing assets का मूल्यांकन करें। आवश्यकता होने पर SEBI-registered Investment Adviser से व्यक्तिगत सलाह लें।
Sources
- “SEBI Investor: Factors to Consider Before Investing” (https://investor.sebi.gov.in/investment-thingsbeforeinv.html)
- “SEBI Investor: Asset Allocation Calculator” (https://investor.sebi.gov.in/calculators/Assets_Allocations.html)
- “SEBI Financial Education: Asset Allocation Strategy” (https://www.sebi.gov.in/sebi_data/investors/financial_literacy/Financial%20Education%20Part%20A.pdf)
- “PFRDA: NPS All Citizen Model, Investment Choices and Asset Allocation” (https://www.pfrda.org.in/en/schemes/national-pension-system/nps-for-all-citizen-models)
- “PFRDA: NPS for Corporates and Life-Cycle Allocation” (https://www.pfrda.org.in/en/schemes/national-pension-system/nps-for-corporates)
- “Value Research: How do I decide my asset allocation?” (https://www.valueresearchonline.com/stories/50737/how-do-i-decide-my-asset-allocation/)
- “Moneycontrol: 100 Minus Age Rule discussion” (https://www.moneycontrol.com/news/business/personal-finance/beware-of-using-the-100-minus-age-thumb-rule-for-equity-allocation-6237581.html)