NPS Swasthya vs Health Insurance: Claim Process 2026
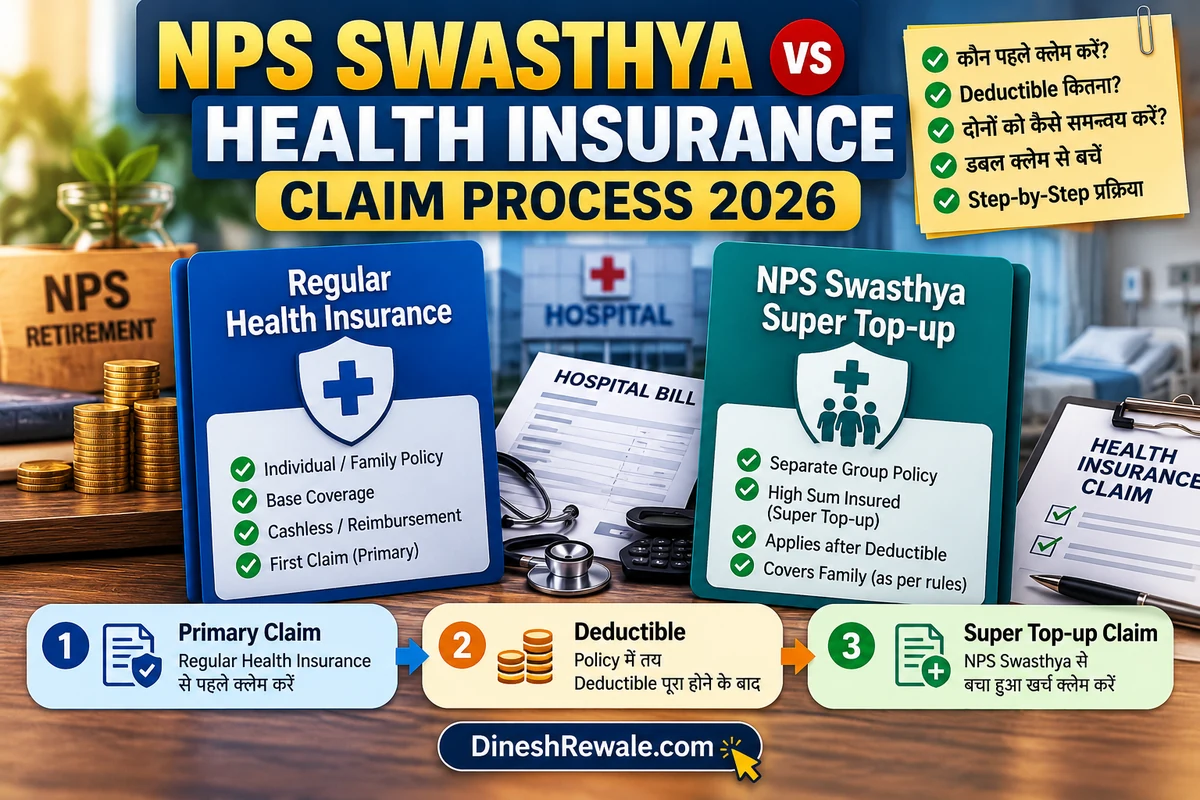
अगर आपके पास regular health insurance और NPS Swasthya दोनों हैं, तो दोनों policies की जानकारी hospital/TPA को शुरू में दें. आम तौर पर एक indemnity health policy को primary claim के लिए चुनकर बाकी eligible bill के लिए NPS Swasthya की super top-up policy में claim/coordination request की जा सकती है. लेकिन NPS Swasthya की deductible, admissible expenses, sum insured और claim procedure आपके Certificate of Insurance और Customer Information Sheet (CIS) के अनुसार ही लागू होंगे.
सबसे जरूरी clarification: NPS Swasthya कोई health insurance rider नहीं है. यह NPS के तहत एक specific-purpose pension scheme है, जिसके साथ अलग super top-up group health insurance policy अनिवार्य रूप से जुड़ी होती है. इसका investment account और insurance policy कानूनी व operational रूप से अलग हैं. PFRDA की Operational Guidelines 18 September 2026 को जारी हुईं और official FAQ 8 October 2026 तक updated है.
इस guide में claim का सही क्रम, regular policy के साथ deductible कैसे पूरा हो सकता है, cashless और reimbursement में क्या करें, उदाहरण, documents checklist और claim reject होने पर complaint route समझाया गया है.
NPS Swasthya और Regular Health Insurance में क्या अंतर है?
| Point | Regular Health Insurance | NPS Swasthya Insurance |
|---|---|---|
| क्या है? | अलग individual/family health policy | NPS Swasthya से जुड़ी अलग super top-up group policy |
| Claim कब उपयोगी? | Policy terms के अनुसार admissible hospital खर्च पर | Policy year में applicable annual aggregate deductible पूरा होने के बाद, policy terms के अधीन |
| Deductible | आपकी policy में जो copay/deductible है | चुने हुए option के अनुसार annual aggregate deductible |
| किसके लिए cover? | आपकी policy schedule में दर्ज members | Standard family floater में subscriber, spouse और अधिकतम 2 dependent children; parents शामिल नहीं |
| क्या एक ही खर्च दो बार मिल सकता है? | नहीं, indemnity claim वास्तविक admissible खर्च से अधिक नहीं हो सकता | बाकी admissible unpaid खर्च के लिए claim करें; same expense का duplicate reimbursement नहीं |
NPS Swasthya के standard insurance framework में entry age 18–70 वर्ष है और renewal policy terms के अधीन 85 वर्ष तक चल सकता है. वास्तविक coverage, waiting periods, exclusions और insurer का नाम अपनी policy documents में check करें. PFRDA की NPS Swasthya official guide पढ़ें.
2026 में NPS Swasthya के Deductible और Cover Options
PFRDA की official NPS Swasthya FAQ में नीचे दिए annual aggregate deductible और family-floater sum insured के combinations बताए गए हैं. Enrolment से पहले applicable option और premium disclose होना चाहिए.
| Annual Aggregate Deductible | Family Floater Sum Insured |
|---|---|
| ₹10,000 | ₹1 लाख |
| ₹50,000 | ₹5 लाख |
| ₹1 लाख | ₹10 लाख |
| ₹3 लाख | ₹30 लाख |
Annual aggregate deductible का मतलब: deductible हर अलग claim पर फिर से लागू होना जरूरी नहीं है. Policy terms के अधीन, covered family members के admissible healthcare expenses policy year के दौरान cumulative रूप से गिने जा सकते हैं. इसीलिए पिछले claims के bills और settlement records सँभालना जरूरी है.
इन amounts को universal choice या guaranteed payout न समझें. आपका actual policy option, premium, deductible, exclusions और coverage policy schedule तथा CIS से confirm होगा. Official reference: PFRDA NPS Swasthya FAQ (updated 8 October 2026).
क्या Regular Health Insurance से पहले NPS Swasthya Claim करना चाहिए?
हर situation में एक जैसा उत्तर नहीं है. Practical तौर पर, अगर आपकी existing regular health policy है, तो अक्सर पहले उसी policy को primary claim के लिए इस्तेमाल करना आसान रहता है और उसके बाद applicable shortfall के लिए NPS Swasthya super top-up insurer/TPA से coordination माँगा जाता है. लेकिन इसे सभी policies के लिए अनिवार्य कानूनी क्रम न मानें.
IRDAI के multiple-policy norms के अनुसार, indemnity-based health insurance रखने वाला policyholder किसी policy के तहत claim settlement चुन सकता है. यदि चुनी हुई primary policy का उपलब्ध cover admissible bill से कम है, तो policy conditions के अनुसार primary insurer दूसरी policies की details लेकर बाकी admissible amount के settlement के लिए coordination करता है. NPS Swasthya की specific super top-up policy का claim route अपने Certificate of Insurance और TPA से confirm करें.
NPS Swasthya और Regular Policy का Claim कैसे करें? 7 Steps
Step 1: Admission से पहले दोनों policies के details निकालें
अपने regular health insurance card/e-card के साथ NPS Swasthya का Certificate of Insurance, insurer और TPA contact details, sum insured और deductible option तैयार रखें. PFRDA के नियमों के अनुसार NPS Swasthya subscriber को Certificate of Insurance और Customer Information Sheet जैसे documents दिए जाने चाहिए.
Step 2: Hospital network और cashless facility verify करें
Hospital के insurance/TPA desk से पूछें कि regular insurer और NPS Swasthya insurer में cashless facility उपलब्ध है या नहीं. Network hospital होना अकेले approval की guarantee नहीं है. दोनों insurers/TPAs से pre-authorisation की requirement, deductible documentation और claim intimation की समय-सीमा पूछें.
Step 3: Regular policy को primary claim के रूप में process कराने का अनुरोध करें
Hospital desk और insurer को बताएं कि आपके पास दूसरी health insurance policy भी है. Policyholder जिस indemnity policy को primary claim के लिए चुनता है, उसे बताएं और दूसरी policy छिपाएँ नहीं. Regular insurer से pre-authorisation, approval amount और क्या-क्या non-payable/deductible है, यह स्पष्ट कराएँ.
Step 4: NPS Swasthya insurer/TPA को समय पर inform करें
उसी समय NPS Swasthya policy के insurer या TPA से claim intimation की requirement पूछें. उनसे लिखित में confirm करें कि deductible पूरा करने के लिए उन्हें कौन-से records चाहिए और क्या primary insurer की pre-authorisation/final settlement के बाद claim submit करना है. सिर्फ यह मानकर न चलें कि दोनों companies का system आपस में स्वतः जुड़ जाएगा.
Step 5: Discharge पर पूरा claim record लें
Hospital से detailed final bill, discharge summary, prescriptions, test reports, paid receipts और claim documents की copy लें. Primary insurer के cashless approval/final settlement letter या reimbursement settlement advice को सुरक्षित रखें. इसमें यह स्पष्ट होना चाहिए कि कितना भुगतान हुआ, कितना balance रहा और कौन-सा खर्च admissible या non-payable बताया गया.
Step 6: Deductible cross होने का proof लगाकर super top-up claim करें
NPS Swasthya insurer/TPA को अपना claim form, hospital records, primary insurer का settlement statement और policy year के पहले के relevant medical claims के bills/settlement letters दें. Annual aggregate deductible policy year में cumulative हो सकता है, इसलिए एक ही hospitalization का bill ही नहीं, उस policy year में पहले हुए eligible expenses के proof भी उपयोगी हो सकते हैं.
PFRDA की FAQ यह भी स्पष्ट करती है कि NPS Swasthya का deductible subscriber के अपने funds, NPS Swasthya account या दूसरी insurance policy से पूरा किया जा सकता है, अथवा इनका combination इस्तेमाल हो सकता है. फिर भी, कौन-सा expense admissible है और कौन-सा proof जरूरी है, यह applicable insurance policy के नियमों से तय होगा.
Step 7: Cashless न मिले तो reimbursement route अपनाएँ
अगर cashless facility उपलब्ध नहीं है या approval नहीं मिला, तो insurer की policy-specific reimbursement process follow करें. Required deadline के अंदर claim intimation और documents submit करें, originals/receipts की जरूरत पूछें और submission acknowledgement लें. एक ही bill की पूरी रकम दोनों insurers को अलग-अलग reimbursement के लिए claim न करें. हर insurer को दूसरी policy और पहले मिले भुगतान की पूरी जानकारी दें.
Example: ₹5 लाख Hospital Bill में Claim Coordination
मान लें कि hospital का bill ₹5,00,000 है. उदाहरण के लिए, regular policy ₹3,00,000 pay करती है और बाकी ₹2,00,000 में से कुछ या पूरा खर्च admissible है. आपकी NPS Swasthya policy में ₹1 लाख annual aggregate deductible और ₹10 लाख sum insured का option है.
| Item | Example amount / action |
|---|---|
| Hospital bill | ₹5,00,000 |
| Regular policy payment | ₹3,00,000 (illustrative) |
| Potential balance before checking deductions | ₹2,00,000 |
| NPS Swasthya deductible | ₹1,00,000 annual aggregate, subject to eligible expenses/policy terms |
| Next action | Submit balance bill, primary settlement letter and previous eligible expense records to NPS Swasthya insurer/TPA for adjudication. |
यह payout guarantee नहीं है. यह सिर्फ claim-coordination का illustration है. Super top-up insurer कितना भुगतान करेगा, यह admissible expenses, already paid amounts, deductible satisfied होने, policy exclusions, sub-limits और sum insured पर निर्भर करेगा. कुल indemnity payment वास्तविक admissible खर्च से अधिक नहीं हो सकती.
Claim के लिए कौन-से Documents तैयार रखें?
- NPS Swasthya Certificate of Insurance और Customer Information Sheet (CIS).
- Regular health insurance policy schedule/e-card और policy number.
- Hospital admission note, discharge summary और treating doctor’s records.
- Detailed itemised final bill और payment receipts.
- Investigation reports, prescriptions और procedure/operation notes, जैसा applicable हो.
- Regular insurer का pre-authorisation, final settlement letter या reimbursement advice.
- Policy year में पहले हुए claims के bills और settlement proofs, यदि annual aggregate deductible calculate करने के लिए जरूरी हों.
- Claim forms, KYC/bank details और any additional document specifically requested by the insurer.
Original documents की आवश्यकता policy के अनुसार बदलती है. Original submit करने पर acknowledgement लें और अपने पास legible copies रखें.
अगर Insurance Claim Reject हो जाए तो क्या करें?
- Rejection letter में exact reason पढ़ें: deductible पूरा न होना, waiting period, exclusion, non-disclosure, incomplete documents या policy eligibility जैसे कारणों में अंतर समझें.
- Insurer/TPA से calculation और policy clause का reference लिखित में माँगें. यदि पहले के eligible claims deductibles में count नहीं किए गए, तो supporting settlement documents के साथ review माँगें.
- NPS Swasthya से संबंधित grievance के लिए Pension Sahayak पर संबंधित stakeholder, जिसमें Pension Fund, HBA या insurer शामिल हो सकता है, के खिलाफ grievance lodge करें.
- सामान्य health-insurance grievance हो तो insurer के grievance officer को पहले लिखें. जरूरत पड़ने पर IRDAI के Bima Bharosa portal पर complaint route देखें.
Insurance claim reject होने का मतलब अपने-आप यह नहीं कि NPS Swasthya corpus से healthcare expense की अनुमति भी reject हो जाएगी. PFRDA FAQ के अनुसार, eligible healthcare expense से जुड़ा permitted withdrawal अलग component है और उसके लिए NPS Swasthya guidelines के नियम लागू होते हैं.
NPS Swasthya Healthcare Withdrawal और Insurance Claim में फर्क
| Feature | Insurance Claim | NPS Swasthya Healthcare Withdrawal |
|---|---|---|
| किसके नियम? | Insurance policy और insurance law | NPS Swasthya Guidelines |
| कितना मिल सकता है? | Deductible, admissible expense और sum insured के अधीन | Eligible healthcare expense के लिए subscriber की contributions का अधिकतम 25%, applicable rules के अधीन |
| पैसा कहाँ जाता है? | Cashless में hospital; reimbursement policy के अनुसार | निर्धारित process के अनुसार hospital/provider या eligible entity को सीधे |
| Insurance rejection का असर? | Policy-specific appeal/review route लागू | Eligible expense withdrawal को अलग guidelines के अनुसार assess किया जा सकता है |
Partial withdrawal में minimum waiting period नहीं बताया गया है और eligible expenses के लिए withdrawal count पर fixed limit नहीं है, लेकिन हर withdrawal applicable conditions तथा 25% contribution limit के अधीन है. Permitted amount सीधे hospital/provider या eligible entity को prescribed process से settle होता है; इसे unrestricted cash reimbursement न समझें.
Quick Checklist: Hospital में Admit होने से पहले
- दोनों policies के insurer/TPA helpline numbers phone में रखें.
- NPS Swasthya का deductible, family floater sum insured और policy year confirm करें.
- Hospital को दोनों policies के बारे में बताकर cashless/pre-authorisation route पूछें.
- सभी claims में bills, previous claim settlements और deductible-related records रखें.
- दोनों insurers के forms में दूसरी policy disclose करें और duplicate claim न करें.
- Emergency treatment delay न करें; जितनी जल्दी practical हो, insurer/TPA को policy process के अनुसार inform करें.
FAQs: NPS Swasthya Claim Process
1. क्या NPS Swasthya regular health insurance का replacement है?
नहीं. NPS Swasthya एक specific-purpose NPS pension scheme है जिसके साथ अलग super top-up group health policy रहती है. इसे अपने base health insurance की जगह मानकर न चलें.
2. क्या regular health insurance का पैसा NPS Swasthya deductible पूरा कर सकता है?
PFRDA की 8 October 2026 updated FAQ के अनुसार, deductible subscriber के अपने funds, NPS Swasthya account, दूसरी insurance policy या इनके combination से पूरा किया जा सकता है. Actual calculation और proof applicable Insurance Policy के अनुसार confirm करें.
3. क्या हर claim के लिए पूरा deductible दोबारा देना होगा?
Standard framework में annual aggregate deductible covered family के admissible healthcare expenses को policy year में cumulative रूप से देखता है, subject to policy terms. पिछली eligible expenses/claims के records इसलिए जरूरी हैं.
4. क्या पहले regular policy में claim करना जरूरी है?
किसी भी situation के लिए ऐसा universal order न मानें. Practical तौर पर regular indemnity policy को primary claim के लिए चुनना उपयोगी हो सकता है, लेकिन NPS Swasthya insurer/TPA से अपने Certificate of Insurance के मुताबिक procedure और deductible proof confirm करें. दोनों policies disclose करें.
5. अगर insurer claim reject कर दे, तो क्या NPS Swasthya account से payment मिल सकती है?
संभव है कि कोई eligible healthcare expense insurance policy में payable न हो, फिर भी उसे NPS Swasthya corpus से consider किया जा सके. यह automatic approval नहीं है; withdrawal eligibility, limit और prescribed process लागू होंगे.
6. NPS Swasthya में claim और withdrawal के लिए कौन-सी official site देखें?
Scheme rules और FAQs के लिए PFRDA NPS Swasthya page देखें. Enrolment/claim documents में दिए insurer, TPA और Pension Fund contacts का उपयोग करें. Scheme-related grievance के लिए Pension Sahayak उपलब्ध है.
काम की Related Guides
- NPS Swasthya 2026: ₹1,000 निवेश और ₹30 लाख तक Health Cover
- Corporate Health Insurance की limit खत्म होने पर क्या करें?
- EPF + NPS से Retirement Corpus बनाने की planning
- NPS vs PPF: Retirement के लिए कौन बेहतर?
- Retirement Planning: 60 से 80 साल तक healthcare और दूसरे खर्च
निष्कर्ष
Regular health insurance और NPS Swasthya की insurance policy को साथ इस्तेमाल करने के लिए claim शुरू करने से पहले दोनों insurers/TPAs को inform करें, deductible और annual policy year confirm करें तथा primary claim का settlement record सुरक्षित रखें. NPS Swasthya की super top-up policy eligible balance खर्च को deductible पूरा होने के बाद policy conditions के अनुसार consider कर सकती है. Healthcare withdrawal एक अलग विकल्प है और उसका पैसा prescribed process के अनुसार सीधे provider को settle होता है.
लेखक: Dinesh Rewale
Dinesh Rewale personal finance, retirement planning और insurance से जुड़ी practical जानकारी आसान हिंदी में साझा करते हैं. नए guides और updates के लिए Facebook पर Dinesh Rewale से जुड़ें.
Disclaimer: यह लेख सामान्य जानकारी के लिए है, व्यक्तिगत financial या insurance advice नहीं. Claim approval, deductible calculation, exclusions, waiting periods और settlement आपके Certificate of Insurance, Customer Information Sheet, applicable insurance policy तथा वर्तमान नियमों पर निर्भर करते हैं. Claim submit करने से पहले insurer/TPA से लिखित पुष्टि करें.