NPS क्या है? Retirement के लिए कितना निवेश करें?
Retirement की planning जितनी जल्दी शुरू की जाए, उतना ही आसान होता है future में बड़ा corpus बनाना। लेकिन शुरुआत से पहले यह समझना जरूरी है कि NPS क्या है, इसमें पैसा कैसे invest होता है और retirement के समय corpus का इस्तेमाल कैसे किया जाता है।
National Pension System (NPS) भारत का retirement-focused, defined-contribution pension system है, जिसे Pension Fund Regulatory and Development Authority (PFRDA) regulate करता है। इसमें आपका contribution चुने गए pension fund और asset allocation के अनुसार market-linked investments में लगाया जाता है, इसलिए return fixed या guaranteed नहीं होता। PFRDA की current information के अनुसार eligible Indian citizens 18 से 85 वर्ष की उम्र के बीच NPS में voluntary रूप से शामिल हो सकते हैं।
इस guide में आप NPS का structure, Tier-I और Tier-II, tax benefits, investment choices और अपनी income तथा retirement goal के हिसाब से contribution तय करने का practical तरीका समझेंगे।
NPS क्या है?
NPS यानी National Pension System एक long-term retirement savings system है। Working years में आप इसमें नियमित contribution करते हैं और वह पैसा PFRDA के नियमों के अनुसार selected pension fund तथा asset classes में invest होता है।
NPS का उद्देश्य retirement के लिए एक disciplined corpus तैयार करना है। इसका structure long-term wealth accumulation के साथ retirement के बाद pension income की जरूरत को भी ध्यान में रखता है। PFRDA के अनुसार NPS account portable है, इसलिए नौकरी या location बदलने पर account की continuity बनी रह सकती है।
NPS में कौन निवेश कर सकता है?
All Citizen Model के तहत eligible Indian citizens NPS को voluntary retirement account के रूप में इस्तेमाल कर सकते हैं। PFRDA की current जानकारी 18 से 85 वर्ष की age eligibility बताती है। Account online eNPS platform या registered Points of Presence के माध्यम से खोला जा सकता है।
NPS Tier-I और Tier-II में क्या अंतर है?
| Feature | Tier-I | Tier-II |
|---|---|---|
| मुख्य उद्देश्य | Retirement account | Optional investment account |
| Withdrawal | Rules और exit conditions के अनुसार | अधिक flexible |
| Tax benefit | Applicable tax rules के अनुसार | सामान्यतः contribution पर tax benefit नहीं |
| Eligibility | Primary NPS account | Active Tier-I account के साथ |
Retirement planning के लिए मुख्य account Tier-I है। Tier-II को optional investment account के रूप में देखा जा सकता है।
NPS में पैसा कहाँ invest होता है?
NPS का return PPF या fixed deposit जैसा predetermined interest नहीं है। आपका contribution selected asset allocation के अनुसार market-linked investments में जाता है। PFRDA के current All Citizen framework में equity, corporate bonds और government securities जैसे asset classes उपलब्ध हैं।
Active Choice
Active Choice में subscriber asset allocation खुद चुन सकता है। Current framework के अनुसार equity exposure अधिकतम 75% तक हो सकता है, जबकि corporate bonds और government securities के लिए prescribed limits उपलब्ध हैं।
Auto Choice
अगर आप allocation खुद manage नहीं करना चाहते, तो Auto Choice में life-cycle approach उपलब्ध है। इसमें आपकी उम्र के साथ asset allocation बदलता है और equity exposure धीरे-धीरे कम हो सकता है।
Retirement के लिए NPS में कितना निवेश करें?
यह सवाल केवल salary देखकर तय नहीं किया जा सकता। सही contribution आपकी उम्र, retirement age, आज के खर्च, future lifestyle, existing corpus, EPF/PPF investments और retirement तक बचे वर्षों पर निर्भर करता है।
शुरुआत के लिए नीचे दिया गया benchmark इस्तेमाल किया जा सकता है। यह कोई सरकारी rule नहीं है, बल्कि personal planning का practical starting point है:
| उम्र | Retirement savings का शुरुआती benchmark | Planning focus |
|---|---|---|
| 20–29 | Income का लगभग 10–15% | Time और compounding का फायदा |
| 30–39 | लगभग 15–20% | Contribution को salary के साथ बढ़ाना |
| 40–49 | लगभग 20–30% | Retirement gap पर ज्यादा ध्यान |
| 50+ | Goal gap के अनुसार अधिक | Shortfall को तेजी से भरना |
ये universal percentages नहीं हैं। आपके पास पहले से EPF, PPF, mutual funds या अन्य retirement assets हैं, तो NPS contribution कम रखना भी पर्याप्त हो सकता है। वहीं retirement के लिए savings कम है, तो contribution अधिक रखना पड़ सकता है।
₹5,000, ₹10,000 और ₹15,000 monthly NPS investment से कितना corpus बन सकता है?
नीचे की calculation केवल illustration है। इसमें 10% annual return assumption लिया गया है और monthly contribution नियमित माना गया है। NPS returns market-linked हैं, इसलिए actual corpus इससे कम या ज्यादा हो सकता है।
| Monthly investment | 20 साल | 25 साल | 30 साल | 35 साल |
|---|---|---|---|---|
| ₹5,000 | लगभग ₹38.3 लाख | लगभग ₹66.9 लाख | लगभग ₹1.14 करोड़ | लगभग ₹1.91 करोड़ |
| ₹10,000 | लगभग ₹76.6 लाख | लगभग ₹1.34 करोड़ | लगभग ₹2.28 करोड़ | लगभग ₹3.83 करोड़ |
| ₹15,000 | लगभग ₹1.15 करोड़ | लगभग ₹2.01 करोड़ | लगभग ₹3.42 करोड़ | लगभग ₹5.74 करोड़ |
इस example से यह समझना आसान है कि retirement planning में time horizon और regular contribution दोनों अहम हैं। छोटी monthly amount भी लंबी अवधि में compounding की वजह से बड़ा corpus बना सकती है, लेकिन return assumption को guaranteed नहीं मानना चाहिए।
अगर salary ₹50,000 है तो NPS में कितना डालें?
मान लीजिए आपकी monthly take-home salary ₹50,000 है। एक शुरुआती planning benchmark के तौर पर ₹5,000 यानी salary का लगभग 10% retirement savings के लिए अलग रखा जा सकता है। समय के साथ income बढ़ने पर contribution ₹7,500 या ₹10,000 तक बढ़ाने का target रखा जा सकता है, अगर आपका overall budget और goals इसकी अनुमति देते हैं।
सिर्फ salary के percentage पर फैसला न लें। Emergency fund, health insurance, life insurance, high-interest debt और short-term financial goals को भी साथ में देखें। ऐसा contribution चुनें जिसे आप लंबे समय तक लगातार जारी रख सकें।
Salary बढ़ने पर NPS contribution कैसे बढ़ाएं?
Step-Up approach retirement planning को ज्यादा practical बना सकती है। उदाहरण के लिए आप आज ₹5,000 monthly से शुरू करते हैं और हर साल salary increment का एक हिस्सा NPS contribution में जोड़ते हैं। इससे monthly budget पर अचानक बड़ा pressure नहीं आता और investment income growth के साथ आगे बढ़ता रहता है।
NPS में tax benefit कितना मिलता है?
NPS का tax treatment आपके tax regime और contribution के type पर निर्भर करता है। Income Tax Department की AY 2026-27 guidance के अनुसार old tax regime में employee contribution पर Section 80CCD(1) के applicable rules के तहत deduction और Section 80CCD(1B) के तहत अलग से अधिकतम ₹50,000 की additional deduction उपलब्ध है, subject to conditions.
Employer contribution अलग provision के अंतर्गत आता है। Income Tax Department की current guidance के अनुसार Section 80CCD(2) के तहत new tax regime में employer contribution के लिए salary की 14% तक deduction limit उपलब्ध है, subject to applicable conditions and tax rules। Old tax regime में employer category के आधार पर prescribed limits अलग हो सकती हैं।
इसलिए NPS को केवल tax saving product समझकर चुनना सही नहीं है। Retirement goal और investment suitability को पहले देखें, फिर applicable tax benefit को planning में शामिल करें।
Retirement पर NPS का पूरा पैसा मिलता है?
सामान्य NPS exit में retirement corpus को lump sum और retirement-income options के बीच बांटा जाता है। PFRDA के current All Citizen Model framework के अनुसार normal exit 60 वर्ष की उम्र या 15 वर्ष की applicable vesting period के बाद हो सकता है। सामान्य तौर पर अधिकतम 80% तक lump sum लिया जा सकता है और कम-से-कम 20% corpus annuity के लिए इस्तेमाल किया जाता है। हालांकि ₹12 लाख तक के कुछ corpus के लिए special withdrawal options उपलब्ध हैं। उदाहरण के तौर पर ₹8 लाख तक corpus में 100% lump sum या approved payout options मिल सकते हैं, जबकि ₹8 लाख से अधिक और ₹12 लाख तक के corpus के लिए निर्धारित lump-sum और systematic withdrawal/annuity options लागू हो सकते हैं।
उदाहरण के लिए, ₹1 करोड़ corpus होने पर current normal-exit framework में अधिकतम ₹80 लाख तक lump sum और कम-से-कम ₹20 लाख annuity के लिए रखा जा सकता है। Annuity से मिलने वाली pension चुने गए annuity option, prevailing annuity rates और applicable terms पर निर्भर करेगी।
क्या NPS retirement के लिए पर्याप्त है?
NPS retirement portfolio का एक important हिस्सा हो सकता है, लेकिन हर व्यक्ति के लिए यह अकेला retirement investment होना जरूरी नहीं है। Retirement में आपका खर्च inflation, healthcare, housing और lifestyle के साथ बदल सकता है।
इसीलिए NPS को EPF, PPF, mutual funds, bank deposits और दूसरे long-term investments के साथ overall retirement plan में देखना अधिक practical है।
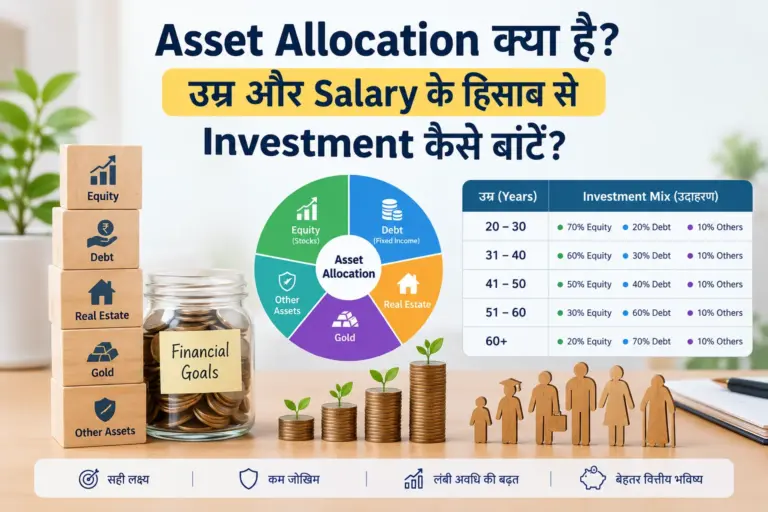
PPF की detailed guide के लिए PPF क्या है? Interest, Tax और Maturity पूरी जानकारी पढ़ें। Monthly investment horizon समझने के लिए SIP में कितने साल तक Invest करना चाहिए? और portfolio allocation के लिए Asset Allocation क्या है? उम्र और Salary के हिसाब से Investment कैसे बांटें? उपयोगी हैं।
Retirement के लिए NPS investment तय करने का आसान तरीका
1. Retirement age तय करें
पहले यह तय करें कि आप किस उम्र के आसपास retire होना चाहते हैं। Retirement age कम होने पर investment period छोटा होगा और required corpus बढ़ सकता है।
2. आज के expenses लिखें
आपको आज घर चलाने के लिए जितना खर्च करना पड़ता है, उसे retirement expense target न मानें। Inflation के कारण future में उसी lifestyle की कीमत ज्यादा हो सकती है।
3. Existing corpus जोड़ें
EPF, PPF, mutual funds, deposits और अन्य retirement savings को एक जगह लिखें। फिर देखिए कि NPS से कितना additional corpus बनाना है।
4. Contribution को हर साल review करें
Income बढ़ती है तो retirement contribution भी बढ़ाने की कोशिश करें। Annual review से contribution को बदलती salary और goals के साथ aligned रखा जा सकता है।
NPS के प्रमुख फायदे
1. Disciplined retirement saving
NPS का retirement-focused structure आपको long-term corpus build करने के लिए regular investing की आदत बनाने में मदद कर सकता है।
2. Asset diversification
NPS में equity, corporate bonds और government securities जैसे asset classes का उपयोग किया जा सकता है। इससे एक ही asset class पर पूरा निर्भर रहने की जरूरत नहीं होती।
3. Tax planning में उपयोगिता
Applicable tax regime और contribution structure के अनुसार NPS tax benefits दे सकता है। विशेष रूप से eligible taxpayers के लिए 80CCD provisions planning का एक हिस्सा हो सकते हैं।
NPS की सीमाएँ भी समझें
- Returns fixed नहीं हैं: NPS market-linked है, इसलिए return हर समय समान नहीं रहेगा।
- Liquidity limited है: Tier-I retirement-focused account है और withdrawals rules के अधीन होते हैं।
- Annuity requirement: सामान्य exit conditions में corpus का एक हिस्सा annuity में लगाया जाना पड़ सकता है।
- Inflation risk: future में बड़ा corpus भी inflation के कारण कम purchasing power दे सकता है।
NPS शुरू करने से पहले 5 बातें जरूर देखें
- आपका retirement corpus target कितना है?
- EPF, PPF और अन्य retirement investments में पहले से कितनी बचत है?
- Monthly contribution लंबे समय तक sustainable है?
- आपका selected asset allocation आपकी risk capacity से मेल खाता है?
- आपके लिए applicable tax regime और NPS tax provisions क्या हैं?
अक्सर पूछे जाने वाले सवाल
NPS क्या है?
NPS यानी National Pension System एक defined-contribution retirement savings system है, जिसे PFRDA regulate करता है। इसमें contribution selected pension fund और asset allocation के अनुसार market-linked investments में जाता है।
NPS में हर महीने कितना निवेश करना चाहिए?
कोई fixed amount सभी के लिए सही नहीं है। शुरुआती benchmark के तौर पर young investors income का लगभग 10–15% retirement savings के लिए रख सकते हैं, लेकिन final contribution age, goal, existing corpus और अन्य investments को देखकर तय करना चाहिए।
क्या ₹5,000 monthly NPS पर्याप्त है?
₹5,000 से शुरुआत की जा सकती है, लेकिन यह पर्याप्त है या नहीं, यह retirement तक बचे समय और target corpus पर निर्भर करेगा। Long horizon में compounding का फायदा बड़ा हो सकता है, जबकि कम समय में higher contribution की जरूरत पड़ सकती है।
क्या NPS में 100% equity में invest कर सकते हैं?
Common NPS schemes के Active Choice framework में equity allocation अधिकतम 75% तक हो सकता है। हालांकि, PFRDA के current Multiple Scheme Framework (MSF) में कुछ high-risk schemes equity exposure 100% तक offer कर सकती हैं। इसलिए 100% equity की उपलब्धता चुनी गई NPS scheme पर निर्भर करती है।
क्या retirement पर NPS का पूरा पैसा मिलता है?
सामान्य exit में current All Citizen Model framework के तहत आम तौर पर अधिकतम 80% तक lump sum और कम-से-कम 20% annuity का प्रावधान है। ₹12 लाख तक के कुछ corpus के लिए special lump-sum और systematic withdrawal options भी उपलब्ध हैं। लागू exit category और current rules को transaction के समय verify करना जरूरी है।
निष्कर्ष
NPS क्या है? इसे सरल भाषा में समझें तो यह retirement के लिए long-term, market-linked और pension-oriented savings system है। इसमें कितना निवेश करना चाहिए, यह आपकी salary से ज्यादा आपके retirement goal, age, time horizon और existing retirement assets पर निर्भर करता है।
अगर आप early stage पर हैं, तो छोटी amount से शुरुआत करके हर साल contribution बढ़ाना practical हो सकता है। अगर retirement नजदीक है और corpus में gap बड़ा है, तो contribution और overall asset allocation की दोबारा समीक्षा करना जरूरी है।
NPS को अकेले product की तरह देखने के बजाय अपने complete retirement plan का हिस्सा मानें।
आधिकारिक संदर्भ
PFRDA: NPS All Citizen Model | PFRDA: All Citizen Exit Information | Income Tax Department: AY 2026-27
Disclaimer: यह लेख केवल सामान्य informational और educational purpose के लिए है। NPS के returns market-linked होते हैं और guaranteed नहीं हैं। Tax rules, exit rules, annuity conditions, contribution provisions और अन्य regulations समय के साथ बदल सकते हैं। Corpus illustrations केवल assumptions पर आधारित estimates हैं, इन्हें guaranteed return या assured pension न समझें। निवेश, tax planning या retirement decision लेने से पहले लागू official rules और अपनी व्यक्तिगत financial स्थिति की समीक्षा करें।