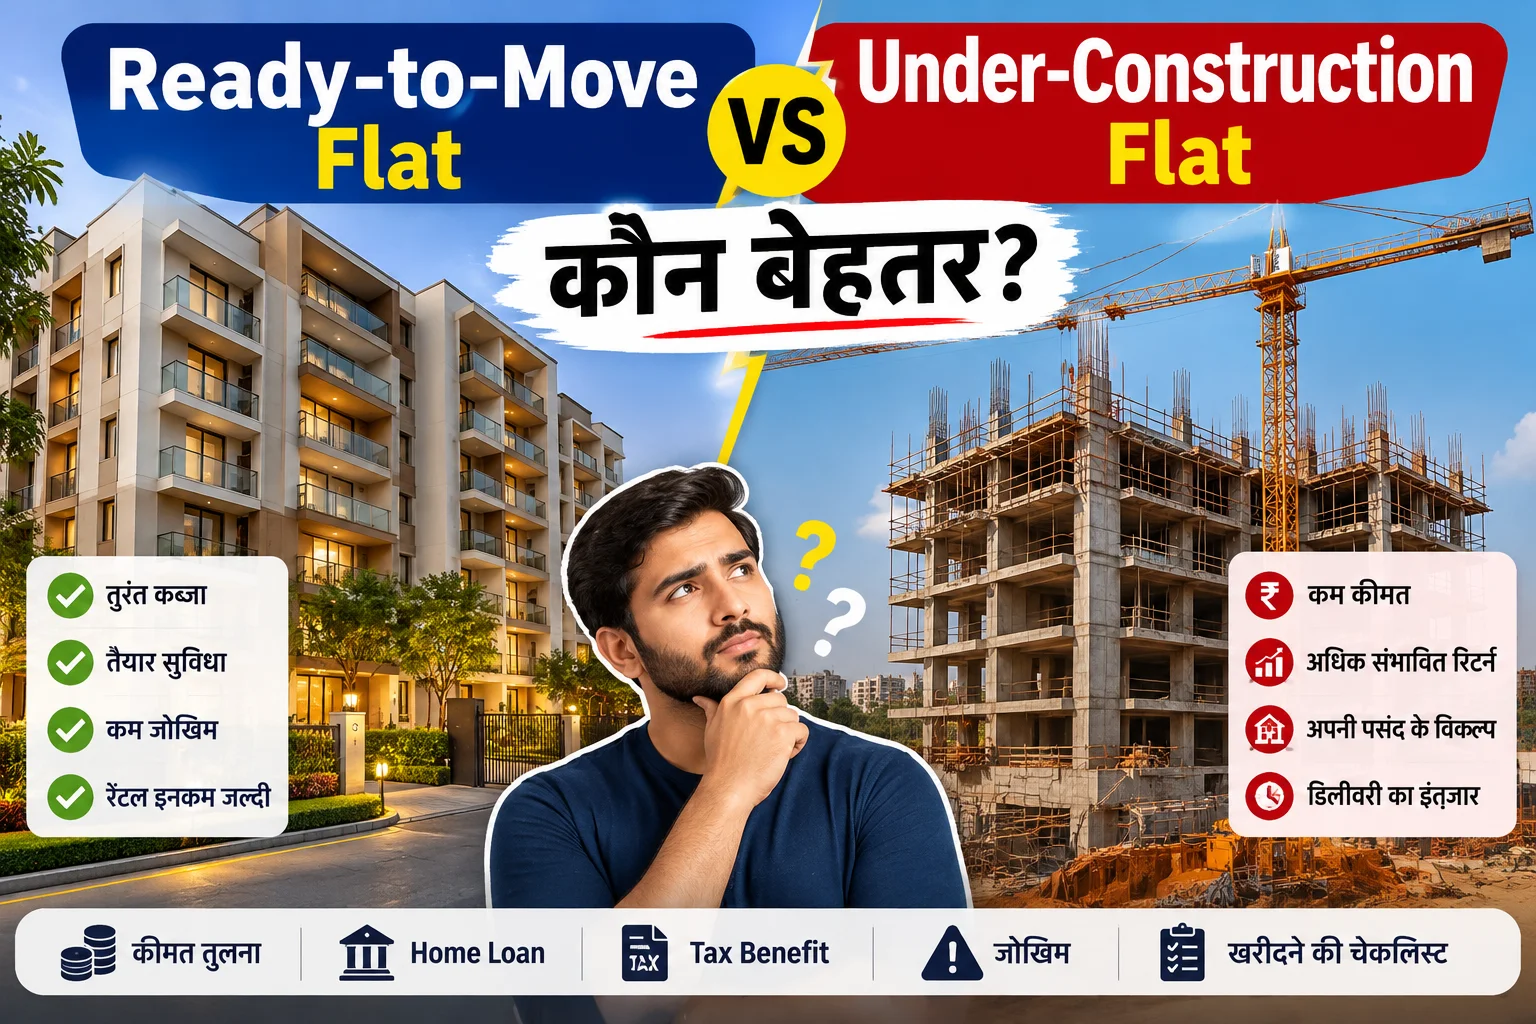
Ready-to-Move vs Under-Construction Flat: कौन बेहतर?
घर खरीदते समय brochure पर सबसे पहले दो numbers दिखते हैं: flat की कीमत और possession की तारीख। इसी जगह से “Ready-to-Move vs Under-Construction Flat: कौन बेहतर?” वाला सवाल शुरू होता है। लेकिन असली फैसला केवल ₹/sq ft या builder की शुरुआती price देखकर नहीं किया जा सकता।
Ready-to-Move flat में आप लगभग वही घर देख सकते हैं जिसे खरीदने जा रहे हैं। Construction का बड़ा हिस्सा पूरा हो चुका होता है, waiting risk कम होता है और आप possession के बाद जल्दी shift, rent या resale की planning कर सकते हैं। दूसरी तरफ Under-Construction flat में payment अक्सर construction progress के साथ जुड़ी होती है, choice और payment flexibility कुछ projects में बेहतर हो सकती है, लेकिन completion delay, rent burden, pre-EMI/interest, specification changes और developer execution जैसे risks भी जुड़ते हैं।
सबसे जरूरी बात यह है कि Ready-to-Move हमेशा महंगा और Under-Construction हमेशा सस्ता नहीं होता। कई बार Under-Construction का advertised price कम दिखता है, लेकिन GST, 18-24 महीने का rent, financing cost और opportunity cost जोड़ने पर अंतर बहुत छोटा हो जाता है। दूसरी तरफ Ready-to-Move flat का premium कभी-कभी उस certainty के लिए भुगतान होता है जो आपको तुरंत मिल रही है।
इस guide में हम India के context में दोनों options को price, GST, cash flow, home loan, possession, RERA, legal checks, tax timing और real-world scenarios के आधार पर compare करेंगे। Maharashtra के buyers के लिए MahaRERA verification को अलग से शामिल किया गया है, क्योंकि सिर्फ “project registered है” कहना पर्याप्त नहीं है। Project progress, approvals और completion-related documents भी देखने जरूरी हैं।
Quick Answer: कौन सा Flat आपके लिए बेहतर हो सकता है?
- Ready-to-Move तब practical हो सकता है जब आपको जल्दी घर में shift होना है, rent जारी नहीं रखना चाहते और exact flat को खरीदने से पहले देखना महत्वपूर्ण है।
- Under-Construction तब consider किया जा सकता है जब project अच्छी तरह verified हो, builder का execution record भरोसेमंद हो और price advantage इतना हो कि waiting तथा financing costs के बाद भी meaningful बचत रहे।
- सिर्फ brochure price नहीं, Total Effective Cost compare करें: property price + GST/other applicable charges + waiting rent + financing cost + possession-related uncertainty.
- Ready-to-Move में भी “ready” शब्द पर्याप्त नहीं है। OC/Completion-related approvals, title, dues और agreement documents verify करना जरूरी है।
- Under-Construction में RERA registration number, promised completion date, project updates और agreement terms को official portal पर cross-check करें।
- अगर आपकी cash flow tight है, तो delayed possession का rent + loan burden बहुत बड़ा issue बन सकता है।
Ready-to-Move और Under-Construction Flat में अंतर क्या है?
Ready-to-Move flat आम तौर पर वह residential unit है जिसका construction substantially complete हो चुका है और lawful occupation के लिए जरूरी approvals, जैसे applicable Occupancy Certificate/Completion Certificate, उपलब्ध हैं। Exact requirement local authority और project structure पर निर्भर करती है। Builder का “ready possession” label अकेले legal proof नहीं है।
Under-Construction flat वह unit है जिसका project अभी construction stage में है और buyer को future completion तथा possession का इंतजार करना पड़ता है। ऐसी purchase में agreement में possession date, payment schedule, specifications, escalation clauses और default-related provisions को ध्यान से पढ़ना ज्यादा महत्वपूर्ण हो जाता है।
Ready-to-Move vs Under-Construction Flat: 12-Point Comparison
| Factor | Ready-to-Move | Under-Construction |
|---|---|---|
| Possession | जल्दी मिल सकता है, subject to valid approvals | Future date पर, project completion पर निर्भर |
| Exact Flat Inspection | Actual unit देखने की सुविधा | अक्सर sample flat, plans और specifications पर निर्भर |
| Construction Delay Risk | बहुत कम, यदि completion और approvals verified हैं | मुख्य risks में से एक |
| GST | Completion certificate/first occupation की स्थिति पर निर्भर; qualifying completed sale पर GST नहीं लग सकता | Applicable residential construction GST लग सकता है, project category के अनुसार |
| Rent Burden | Shift करने पर rent जल्दी बंद हो सकता है | Possession तक rent जारी रह सकता है |
| Home Loan Disbursement | अक्सर faster/full disbursement structure | Construction-linked disbursement common |
| Pre-EMI/Interest | Disbursement के तुरंत बाद normal EMI structure शुरू हो सकता है | Staged disbursement के कारण pre-EMI/interest burden बन सकता है |
| Choice of Unit | Available inventory तक सीमित | Early booking में options ज्यादा मिल सकते हैं |
| Customization | निर्माण पूरा होने के कारण सीमित | Early-stage project में कुछ customisation options हो सकते हैं, project rules पर निर्भर |
| Resale/Rental Start | Earlier start possible | Possession तक wait |
| Cash Flow Certainty | Comparatively clearer | Construction-linked payments और delay risk के कारण less certain |
| Main Risk | Higher purchase price, hidden repair/fit-out issues, document gaps | Delay, execution, specification changes, financing and developer risk |
Practical Tip: Price comparison हमेशा “आज कितना दूँगा?” से नहीं, बल्कि “Possession तक मेरे pocket से कुल कितना जाएगा?” से शुरू करें।
1. Price: क्या Under-Construction flat सच में सस्ता होता है?
कई projects में Under-Construction unit का headline price Ready-to-Move property से कम दिख सकता है। इसके पीछे launch pricing, construction-stage payment plans, inventory strategy या location-specific demand जैसे कई कारण हो सकते हैं। लेकिन यह कोई universal rule नहीं है। Premium projects में Under-Construction unit भी महंगा हो सकता है।
इसलिए दो flats compare करते समय carpet area, floor, view, parking, floor-rise, amenities, maintenance deposit, club charges और other project-specific costs को समान basis पर लाना जरूरी है। ₹5 लाख कम quoted price देखकर फैसला करना गलत हो सकता है, अगर दूसरे flat में कुछ charges पहले से included हों।
2. GST: Ready-to-Move और Under-Construction में बड़ा फर्क
GST के rules में सबसे महत्वपूर्ण distinction यह है कि qualifying transaction में apartment/building की sale completion certificate जारी होने के बाद और first occupation के context के अनुसार GST treatment अलग हो सकता है। GST Council की real-estate framework में new residential projects के लिए affordable category पर 1% और अन्य residential apartments पर 5% effective GST without ITC की व्यवस्था बताई गई है, subject to the applicable conditions and notifications. पुराने/transition cases और specific transaction structures का treatment अलग हो सकता है।
इसलिए किसी project में “5% GST लगेगा” या “GST नहीं लगेगा” सुनकर तुरंत total cost तय न करें। Agreement, invoice structure, completion status और applicable GST provisions verify करें।
GST का simple example
मान लीजिए Under-Construction flat का quoted base price ₹72 लाख है और illustrative assumption के रूप में 5% GST लागू है।
GST = ₹72,00,000 × 5% = ₹3,60,000
Price + GST = ₹75,60,000
अब अगर possession में 24 महीने बाकी हैं और आप ₹25,000 monthly rent देते हैं:
Waiting Rent = ₹25,000 × 24 = ₹6,00,000
तो केवल इस illustration में, stamp duty, registration, interiors और financing cost जोड़ने से पहले effective cash outflow का एक हिस्सा ही ₹81,60,000 हो जाता है। यानी ₹72 लाख का headline price देखने पर जो saving दिखाई दे रही थी, वह waiting cost जोड़ने के बाद बदल गई।
यह केवल calculation example है। GST rate applicability project और transaction facts पर निर्भर है, और rental cost आपके actual rent पर निर्भर करेगी।
3. Possession Risk: Under-Construction में सबसे महत्वपूर्ण सवाल
Under-Construction property में आपका सबसे बड़ा non-price risk delay है। Delay का impact सिर्फ possession date आगे बढ़ने तक सीमित नहीं रहता। अगर आप अभी rent पर रह रहे हैं, तो rent बढ़ सकता है। Home loan disbursement होने पर interest या pre-EMI burden बन सकता है। Interior planning और relocation भी बार-बार बदल सकती है।
RERA framework में promoter द्वारा agreement में तय possession timeline का महत्व है। यदि promoter specified terms के अनुसार possession नहीं देता, तो applicable statutory remedies, including refund/interest provisions, facts और buyer choice के आधार पर लागू हो सकते हैं। इसलिए agreement for sale में promised date और applicable clauses को पढ़ना बेहद जरूरी है।
RERA पर क्या check करें?
- Project का official RERA registration number.
- Promoter का नाम और project status.
- Declared completion date और available project updates.
- Approvals और project-related disclosures.
- Latest progress, completion percentage और relevant certificates.
- Agreement for Sale में possession date और delay clauses.
Maharashtra में buyer MahaRERA portal पर project registration और available project updates verify कर सकता है। MahaRERA अपने portal पर project details और completion-related updates को public visibility के लिए उपलब्ध कराता है।
4. Home Loan: Ready-to-Move और Under-Construction में cash flow कैसे बदलता है?
Home Loan comparison में सिर्फ sanctioned amount और EMI देखना पर्याप्त नहीं है। Under-Construction property में lender अक्सर construction progress के अनुसार amount disburse करता है। Disbursed amount पर interest/pre-EMI की calculation हो सकती है। Actual structure lender और loan agreement पर निर्भर करता है।
Ready-to-Move property में, अगर documentation और disbursement तेजी से पूरा होता है, तो ownership और repayment timeline comparatively clearer हो सकती है। इसका मतलब यह नहीं कि Ready property में loan cost कम ही होगी। Rate, tenure, loan amount और lender terms फिर भी decisive factors हैं।
Home Loan EMI का illustrative calculation
मान लीजिए loan amount ₹60 लाख, annual interest rate 8.5% और tenure 20 साल है। Monthly reducing-balance EMI formula के अनुसार EMI लगभग ₹52,069 आती है।
Formula: EMI = P × r × (1+r)n / ((1+r)n − 1)
यहाँ P = ₹60,00,000, r = 8.5%/12 और n = 240 months.
Illustration में total payment लगभग ₹1.25 करोड़ और total interest लगभग ₹64.97 लाख बनता है, यदि rate पूरे 20 साल तक 8.5% ही रहे।
यह example बताता है कि flat price का छोटा अंतर भी long-term financing cost के सामने बहुत बड़ा या बहुत छोटा हो सकता है। वास्तविक floating-rate loan में rate बदल सकता है, इसलिए यह guaranteed final cost नहीं है।
Watch Out: Under-Construction project में “EMI बाद में शुरू होगी” सुनकर total interest zero न समझें। Disbursement schedule और pre-EMI terms lender से लिखित रूप में समझें।
5. Waiting Cost: यही वह हिस्सा है जिसे कई buyers miss करते हैं
किसी Under-Construction flat को “₹8 लाख सस्ता” देखकर खुश होना आसान है। कठिन हिस्सा यह समझना है कि possession तक आपको rent, travel, maintenance और finance-related outflow कितना होगा।
| Cost Head | Illustrative Amount | क्या देखना है |
|---|---|---|
| Quoted price difference | −₹8.00 लाख | क्या same carpet area और specifications हैं? |
| GST difference | +₹3.60 लाख | Applicable project treatment verify करें |
| Rent for 24 months | +₹6.00 लाख | ₹25,000/month assumption |
| Financing/pre-EMI | +₹X | Actual disbursement schedule से निकालें |
| Other holding costs | +₹X | Travel, storage, temporary shifting, etc. |
ऊपर की table में X को जानबूझकर fixed नहीं रखा गया है, क्योंकि financing और temporary housing cost buyer-specific होती है। यही discipline आपको false precision से बचाता है।
6. Pre-EMI का practical example
मान लीजिए 24 महीने की construction period में आपकी cumulative disbursed loan amount का average ₹30 लाख रहा और illustrative annual interest rate 8.5% रही। Simple approximation से:
Approx. interest = ₹30,00,000 × 8.5% × 2 = ₹5,10,000
यह actual lender calculation नहीं है। यह सिर्फ यह समझाने के लिए है कि construction period का financing cost meaningful हो सकता है। Real loan में disbursement महीने-दर-महीने बदल सकता है, interest daily/monthly methodology और lender terms पर निर्भर हो सकता है, और normal EMI structure अलग हो सकता है।
7. Ready-to-Move में आपको क्या advantage मिलता है?
Exact flat को देख सकते हैं
Room size, view, sunlight, ventilation, common areas, lift movement और actual finishing का अंदाजा sample flat की तुलना में ज्यादा स्पष्ट हो सकता है।
Possession uncertainty कम होती है
Construction risk का बड़ा हिस्सा पीछे रह जाता है। फिर भी OC/Completion documents और legal handover verify किए बिना “ready” label पर भरोसा नहीं करना चाहिए।
Rent जल्दी बंद हो सकता है
जो buyer अभी rented home में रह रहा है, उसके लिए immediate shift एक practical financial benefit हो सकता है। लेकिन moving, interiors और maintenance की लागत भी budget में रखें।
Immediate use या rental
Self-use के लिए shift जल्दी हो सकता है। Rental investment के case में tenant search, maintenance और local demand को अलग से evaluate करना होगा। Ready property में rent generation का इंतजार construction completion तक नहीं रहता।
8. Under-Construction में क्या benefits हो सकते हैं?
Payment schedule comparatively staged हो सकता है
Construction-linked plan में पूरा purchase price एक ही समय पर pay नहीं करना पड़ सकता। लेकिन schedule contract और lender funding structure पर निर्भर करता है, इसलिए cash flow calendar पहले बनाएं।
Choice और launch-stage inventory
Early stage में floor, facing या unit selection के options ज्यादा मिल सकते हैं। यह project की inventory पर निर्भर करता है। “Early booking = cheap” को automatic rule न मानें।
Future-ready project features
कुछ buyers newer amenity package, planned township infrastructure या newer building specifications के लिए Under-Construction project चुनते हैं। लेकिन promised amenity और delivered amenity एक ही चीज नहीं हैं। Agreement तथा sanctioned plan से verify करें कि क्या committed है।
9. Total Effective Cost Framework: यही सही comparison है
दो flats compare करने के लिए यह framework उपयोगी है:
Total Effective Cost = Purchase Consideration + Applicable Taxes/Charges + Waiting Cost + Financing Cost + Possession/Setup Cost
Ready-to-Move के लिए waiting cost अक्सर छोटी होती है, जबकि Under-Construction के लिए waiting rent और pre-EMI अलग line items बन सकते हैं। दूसरी तरफ Ready flat में upfront premium, renovation या immediate fit-out cost अधिक हो सकती है।
एक practical decision matrix
| आपकी स्थिति | पहले क्या compare करें? |
|---|---|
| अभी rent बहुत ज्यादा है | Waiting months × rent + financing cost |
| नौकरी/शहर बदलने की संभावना है | Lock-in, resale liquidity और possession timeline |
| Budget tightly stretched है | All-in cost, EMI stress और contingency reserve |
| Builder नया है | Track record, RERA data, approvals और agreement terms |
| परिवार को तुरंत घर चाहिए | Actual possession readiness और OC/Completion documents |
| Investment उद्देश्य है | Entry price, rental demand, exit liquidity और holding period |
10. Tax angle: Under-Construction में tax benefit कब मिलेगा?
Home-loan tax treatment में timing महत्वपूर्ण है। Income Tax Department के current guidance के अनुसार old tax regime में self-occupied property पर housing-loan interest deduction section 24(b) के तहत conditions के अधीन ₹2 लाख तक हो सकती है और eligible housing-loan principal payment section 80C की overall ₹1.5 लाख limit में आ सकता है। Tax treatment taxpayer की regime, property use और अन्य conditions पर निर्भर करता है।
Under-Construction property में pre-construction interest का treatment अलग होता है। Eligible cases में यह acquisition/construction पूरा होने के बाद five equal instalments में claim किया जाता है, subject to the law and applicable conditions. इसलिए “loan लिया = उसी साल पूरा interest deduction” मानना सही नहीं है।
Current tax rules बदल सकते हैं, इसलिए filing के समय Income Tax Department की latest guidance और आपका specific assessment जरूरी है।
11. Maharashtra Buyers के लिए MahaRERA checklist
अगर property Maharashtra में है, तो project का MahaRERA record जरूर देखें। सिर्फ registration number देखकर आगे न बढ़ें। उपलब्ध project information से कम-से-कम ये points verify करें:
- Project name और promoter details.
- Registered completion date और latest updates.
- Construction progress और available completion information.
- Uploaded approvals/certificates जहां relevant हों.
- Litigation/encumbrance disclosures जहां available हों.
- Agreement में promised possession date.
- Completed project होने पर OC/Completion-related documents की consistency.
भारत के दूसरे राज्यों में संबंधित state RERA authority के official portal का इस्तेमाल करें। RERA registration को title search का substitute नहीं मानें। Independent legal due diligence अलग से जरूरी है।
12. Ready-to-Move खरीदते समय कौन से legal checks करें?
- Title और ownership chain का independent legal verification.
- Applicable approvals और occupancy/completion documents.
- Property tax, maintenance और utility dues.
- Society formation/association और transfer process.
- Parking rights और agreement में उसका treatment.
- Actual carpet area और promised specifications.
- Encumbrance, mortgage release और seller/builder dues.
- Agreement for Sale/Conveyance और applicable registration documents.
इस process के लिए हमारी Flat Buying in Mumbai checklist भी उपयोगी reference है।
13. Under-Construction खरीदते समय कौन सी गलतियां महंगी पड़ सकती हैं?
सिर्फ brochure price देखना
Price comparison में GST, rent, financing और all-in charges जोड़ें।
Possession date को verbal promise मानना
Agreement for Sale में date और delay provisions पढ़ें। Marketing timeline और contractual timeline एक जैसे हो सकते हैं, लेकिन verify करना जरूरी है।
“RERA registered” को complete due diligence समझना
RERA registration useful public information देता है, पर title, bank lien, local approvals और technical quality के लिए अलग checks जरूरी हो सकते हैं।
Pre-EMI का impact भूल जाना
Loan disbursal schedule लिखित रूप में समझें और delayed possession scenario में cash-flow buffer रखें।
Emergency fund पूरा down payment में लगा देना
घर खरीदते समय cash reserve खत्म करना risky हो सकता है। Emergency Fund vs FD जैसी planning को purchase decision के साथ जोड़कर देखें।
14. Salary और affordability का connection
Flat की खरीद तभी comfortable होती है जब EMI आपकी broader financial life को damage न करे। Home Loan लेने से पहले EMI को salary के संदर्भ में देखना जरूरी है, लेकिन केवल किसी fixed percentage को universal rule न मानें। आपके existing loans, dependents, insurance, savings, school expenses और job stability भी matter करते हैं।
Home Loan EMI Salary का कितना % होना चाहिए? वाली हमारी guide में इसी affordability angle को detail में समझाया गया है।
15. Ready-to-Move vs Under-Construction: किस buyer को क्या देखना चाहिए?
अगर आप first-time homebuyer हैं
पहले legal clarity, monthly cash flow और exact possession requirement समझें। Sample flat से ज्यादा important actual delivery capability और documents हैं।
अगर आप family के साथ तुरंत shift होना चाहते हैं
Ready-to-Move option practical हो सकता है, खासकर जब current rent significant है। लेकिन “ready” की legal readiness verify करें।
अगर आप 2-3 साल wait कर सकते हैं
Under-Construction option consider किया जा सकता है, लेकिन price advantage को waiting cost और financing cost से adjust किए बिना conclusion न निकालें।
अगर आपका budget stretch हो रहा है
Cheaper-looking Under-Construction deal आपको ज्यादा comfortable तभी बनाएगी जब total cash flow वास्तव में manageable हो। Down payment के बाद emergency reserve बचना भी जरूरी है।
अगर investment के लिए खरीद रहे हैं
Possession timeline, rental demand, vacancy risk, resale liquidity, location fundamentals और total acquisition cost को साथ रखें। केवल future price appreciation की expectation पर calculation न बनाएं।
16. “कितना सस्ता होना चाहिए?” एक useful break-even calculation
मान लीजिए उसी location और comparable specification में Ready-to-Move flat ₹80 लाख का है। Under-Construction flat का base price ₹72 लाख है। Illustrative 5% GST और 24 महीने का ₹25,000 monthly rent मानें।
Under-Construction base price = ₹72.00 लाख
GST = ₹3.60 लाख
Waiting rent = ₹6.00 लाख
Illustrative effective cost before financing/registration = ₹81.60 लाख
यहाँ ₹8 लाख की apparent price saving खत्म होकर ₹1.60 लाख का higher pre-financing outflow बन गया। इसलिए Under-Construction deal को justify करने के लिए आपको सिर्फ ₹8 लाख headline discount नहीं, बल्कि waiting और financing costs के बाद बचने वाला real advantage देखना चाहिए।
Expert Insight: “Discount” को property decision का output न मानें। पहले Effective Cost निकालें, फिर risk premium और liquidity को अलग से discuss करें।
17. Home Loan planning को property decision से जोड़ें
Flat खरीदना isolated transaction नहीं है। Down payment के बाद आपके पास emergency fund, registration expenses, interiors, moving cost और other near-term goals के लिए liquidity बचनी चाहिए। इसी कारण home-buying budget बनाते समय monthly budget और long-term asset allocation पर भी नजर रखें।
आप Home Loan लेने से पहले 15 जरूरी बातें और Loan पहले चुकाएं या Investment करें? जैसी related guides को भी साथ में पढ़ सकते हैं।
18. 10-Point Flat Buying Checklist
- Carpet area और total consideration same basis पर compare करें.
- GST applicability written breakup में लें.
- Stamp duty और registration अलग calculate करें.
- Parking, floor-rise, maintenance deposit और other charges verify करें.
- Under-Construction हो तो RERA registration और latest updates check करें.
- Possession date agreement में देखें.
- Ready-to-Move हो तो OC/Completion-related documents verify करें.
- Home Loan disbursement और pre-EMI structure लिखित में समझें.
- Waiting rent और relocation cost को total cost में जोड़ें.
- Down payment के बाद emergency reserve और other financial goals सुरक्षित रखें.
FAQs: Ready-to-Move vs Under-Construction Flat
क्या Ready-to-Move flat पर GST नहीं लगता?
Qualifying sale में, जहाँ completion certificate जारी हो चुका हो और transaction prescribed completed-property conditions को meet करती हो, GST लागू नहीं हो सकता। लेकिन project की exact status और agreement facts verify करना जरूरी है।
Under-Construction flat पर GST कितना है?
Current residential real-estate framework में qualifying affordable homes के लिए 1% और अन्य residential apartments के लिए 5% effective rate without ITC का framework है, subject to applicable conditions, notifications और project facts।
क्या Under-Construction flat हमेशा सस्ता होता है?
नहीं। कई projects में headline price कम हो सकता है, लेकिन GST, waiting rent, financing cost और other charges के बाद effective cost अलग हो सकती है।
Under-Construction flat में सबसे बड़ा risk क्या है?
Delayed possession एक प्रमुख risk है। इसका असर rent, interest/pre-EMI, relocation planning और overall cash flow पर पड़ सकता है।
RERA registration होने से project safe हो जाता है?
RERA registration important transparency और disclosure framework देता है, लेकिन यह title verification, technical inspection और सभी commercial risks का substitute नहीं है। Independent due diligence जरूरी है।
OC और “ready possession” एक ही चीज हैं?
नहीं। Builder का ready-possession claim और competent authority से applicable occupancy/completion approval अलग concepts हो सकते हैं। Possession से पहले relevant documents verify करें।
Under-Construction home loan में pre-EMI क्या है?
Construction-linked disbursement structure में lender द्वारा पहले से disbursed amount पर interest/pre-EMI payable हो सकता है। Exact terms loan agreement और lender process पर निर्भर करते हैं।
Tax benefit Under-Construction property में कब मिलता है?
Tax treatment timing और property use पर निर्भर करता है। Pre-construction interest eligible cases में possession/acquisition के बाद five equal instalments में claim किया जाता है, subject to applicable law and conditions.
अगर Ready flat थोड़ा महंगा है, तो क्या उसका premium देना समझदारी है?
यह buyer की situation पर निर्भर है। Compare करें कि higher price के बदले आपको rent saving, earlier use, lower delay uncertainty और exact-unit visibility कितनी मिल रही है।
Under-Construction property खरीदने से पहले सबसे पहले क्या check करें?
RERA status, promoter disclosures, agreement for sale, promised possession date, payment schedule, approvals, title due diligence और total effective cost को एक साथ check करें।
निष्कर्ष
“Ready-to-Move vs Under-Construction Flat: कौन बेहतर?” का एक universal answer नहीं है। सही विकल्प आपकी cash flow, waiting tolerance, family requirement, loan structure, project quality और total effective cost पर निर्भर करता है।
Ready-to-Move option में certainty और immediate usability का value होता है। Under-Construction option में potential pricing advantage और staged payment जैसी बातें attractive हो सकती हैं, लेकिन आपको construction और possession risk के लिए तैयार रहना पड़ता है।
सबसे practical rule यह है: headline price नहीं, possession तक की total financial picture compare करें. अगर Under-Construction flat का real saving GST, rent और financing cost जोड़ने के बाद भी meaningful बचता है और project due diligence मजबूत है, तो वह एक viable option हो सकता है। अगर waiting cost और uncertainty आपके budget या life stage पर भारी पड़ रही है, तो Ready-to-Move की higher upfront price अलग तरीके से justify हो सकती है।
Final decision से पहले agreement, current lender terms, official RERA records, tax rules और property documents को independently verify करें।
Author: Dinesh Rewale
Dinesh Rewale एक independent content creator और blogger हैं, जो personal finance, business, investments, technology, real estate और current affairs को आसान, reader-friendly भाषा में समझाने पर ध्यान देते हैं.
Facebook: https://www.facebook.com/profile.php?id=61574859401427
Financial Disclaimer
यह लेख सामान्य educational और informational purpose के लिए है। Property prices, GST treatment, RERA disclosures, lender policies, interest rates, tax provisions और project approvals बदल सकते हैं। इस लेख के calculations illustrative assumptions पर आधारित हैं और personalized financial, legal या tax advice नहीं हैं। Property खरीदने से पहले latest agreement, official RERA portal, applicable government notifications, lender documents और independent legal/tax advice की जांच करें।